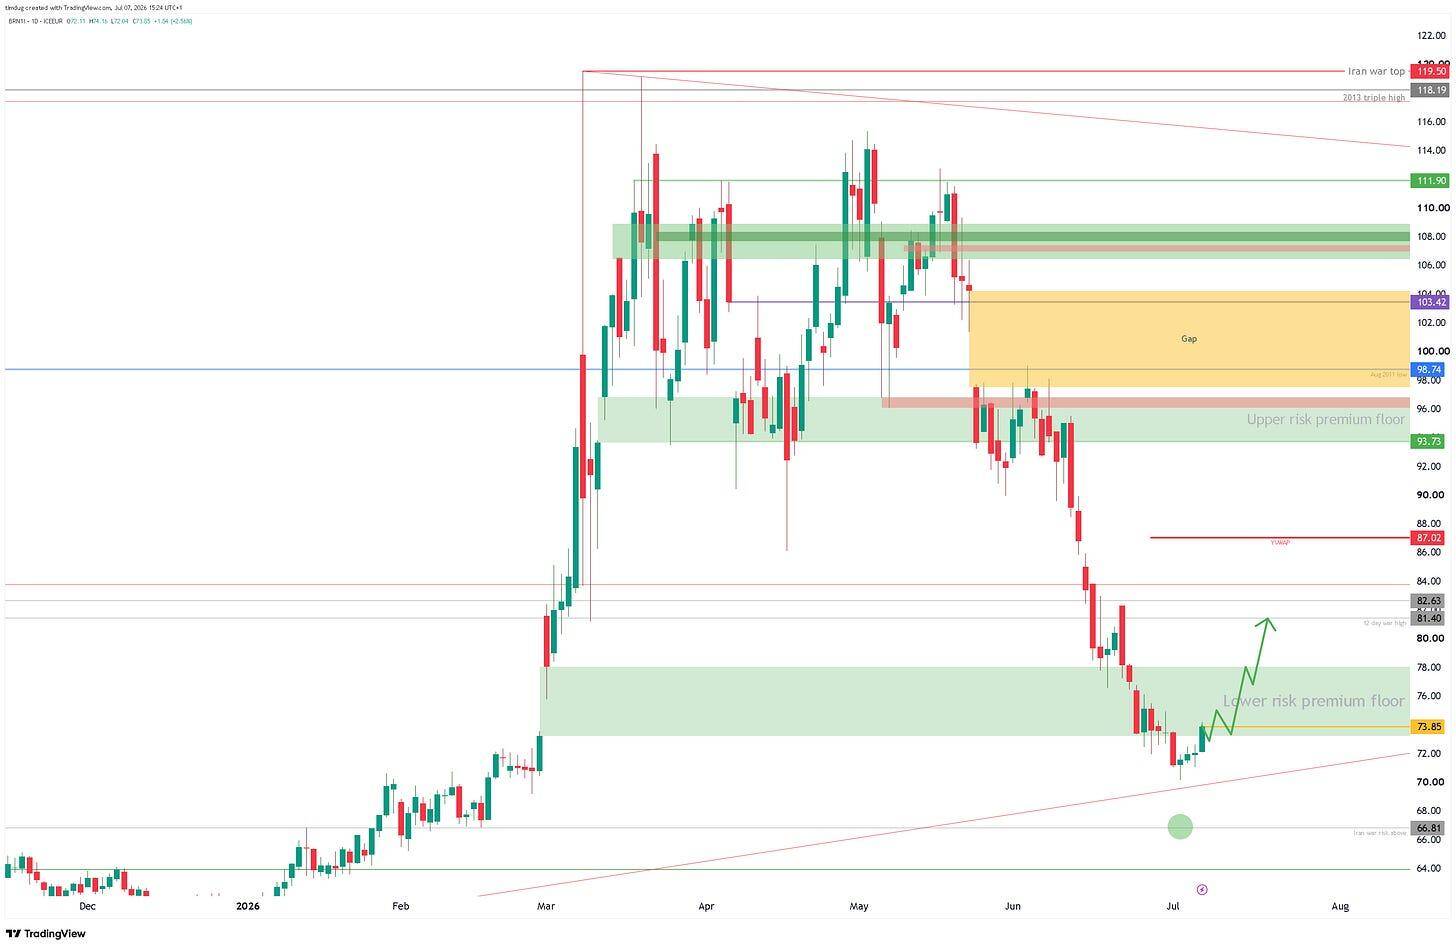
Healing has started! Risks remain in second order consequences. I’m going to show below in inventories how the global picture currently looks. This will be significant going forward. The reason for which, is that I suspect we are supplied at one level right now, however should China return to market, this will turn on a dime. Sure, ‘it’s over’ is now fully priced. But in the greater context, we have just departed the zone of first order consequences and are about to enter the second order consequences world. This is where the more interesting trades will be.
Some updates from Monday eve/Tuesday morning:
- The IRGC has struck several vessels transiting via the southern route. This has apparently not affect normal passage via the ‘Northern route’, closer to Iranian shores. It is best to monitor this for further escalation through this week. Brent is up 1.2% as of midday London.
- Saudi is stated to be expanding its East West pipeline by +2mb/d to increase exports via The Red Sea. Due to the current situation, Aramco had already pushed this pipeline from 5-7mb/d, utilising existing NGL (Natural Gas Liquids?) pipelines that got repurposed. Adding another 2mb/d from my analysis would require an actual new pipe to be laid. If this is the case, we are looking at a 3-5 years to completion. The original pipe was commissioned in 1979 in 2yrs, under a different regulatory and standards regime.
- One thing to note on the headline of 7mb/d is the true capacity of the pipeline, however the Yanbu port loading capacity is 4mb/d.
- Refineries at Yabu can take roughly 1-2mb/d of this. (SAMREF 400k + YASREF 405k + Yanbu refinery 240k). So after refinery draw, its about 5-6mb/d that gets to loading. In short, Yanbu port OR refiners will have to scale up capacity to match with an additional 2mb/d pipeline and none of it happens in the next 3 years.
Now to this week’s report.
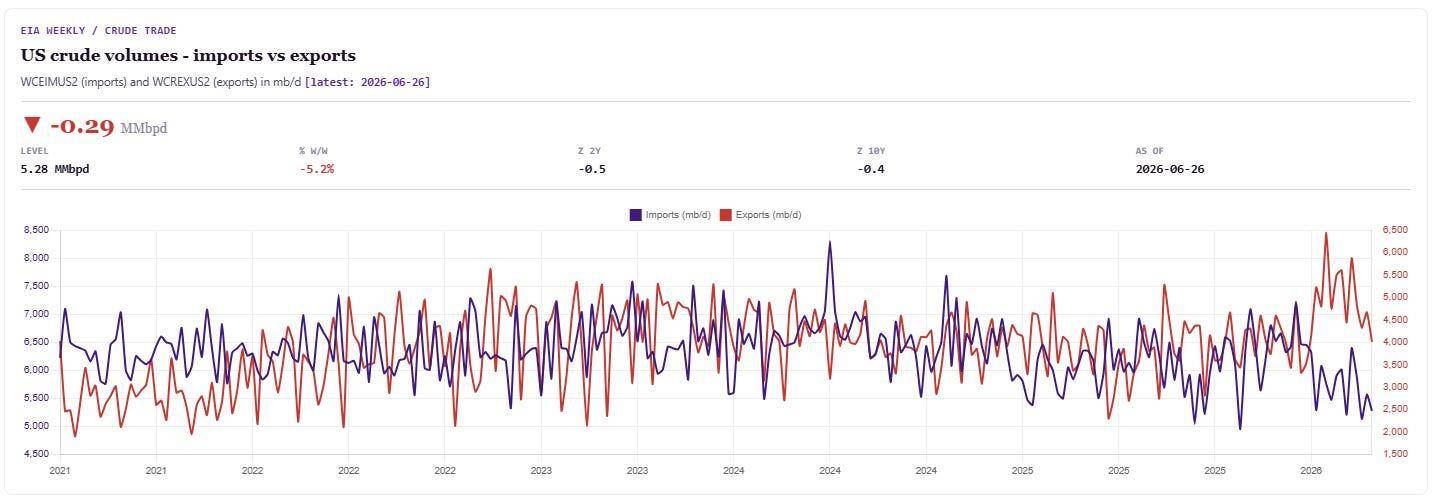
For all of the bluster of the war, the simple fact is the strategic stocks into market were and are well supplied since mid-May in the G7. See where they are at right now below in ‘Global stocks’.
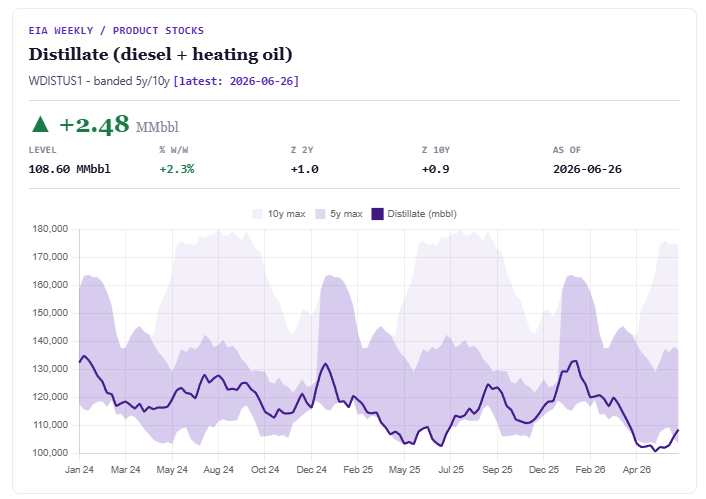
This remains to be the case, however should there be another prolonged closure, these reserves will be released again but at greatly reduced levels. We are continuing to draw down on commercial stocks at Cushing WoW; however, refiners are flat out meeting demand for product. The distinction between ‘meeting’ and ‘trying to meet’ here is significant. The largest upside risk to oil prices is where we see distillates start to draw rather than build. In speaking to this fear, the latest EIA data was a distillate build.
As is with these types of situations in markets, the horror show becomes the greatest talking point and therefore, the greatest fallacy. This happens by way of everything under the known sun getting priced in immediately, then the risk gets priced out. To explain this in easier terms.
Once the market knew there was 400mb of strategic reserves to be released, it could not achieve any new high until those reserves were 100% drawn down, or the war took a much more aggressive form. Risk occurred and was dealt with. So the trade becomes sell the headline. Sure, it becomes a mainstay talking point for weeks and months while it gets worked out, but talking heads don’t make good trades.
Brent Oil Price Forecast
Every new Brent Oil analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Brent Oil forecastsNegotiations / The Article 13 Gate
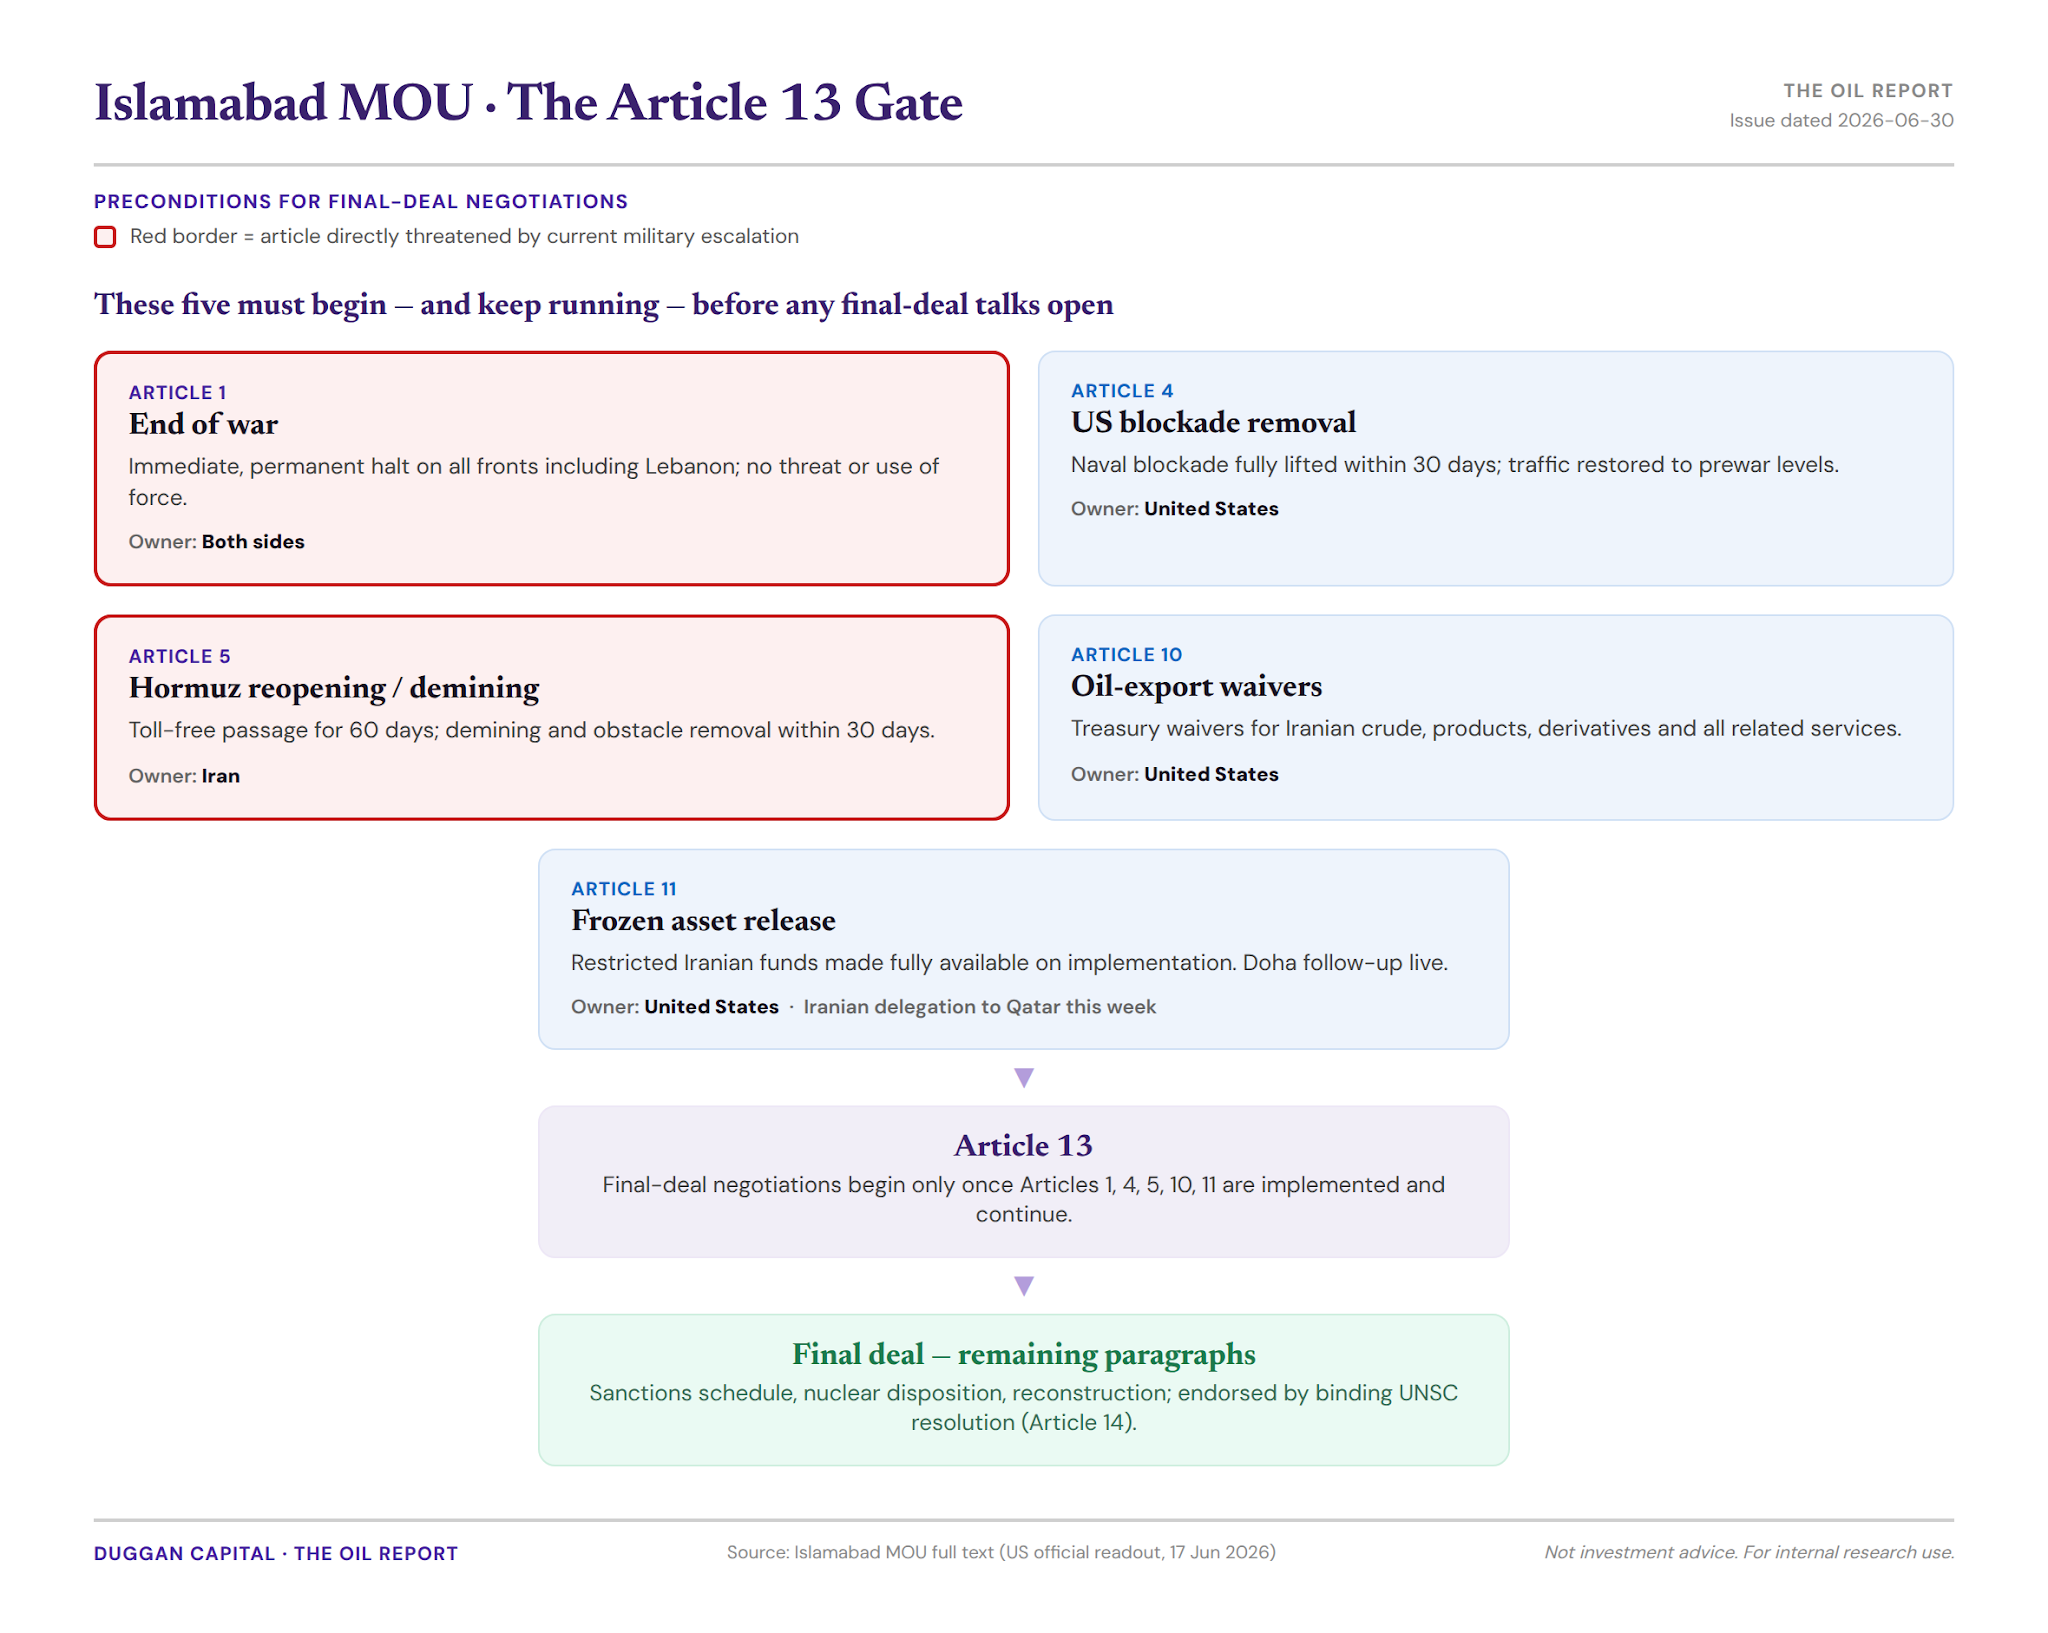
After signing this MOU, Iran and The US have made very good headway towards their MoU goals. Articles 4, 5, 10 are all but complete, with Article 11 currently under discussion on the final $6billion in Doha. This is strong progress. 3 steps forward have led to one step back and forth regarding the closure of Hormuz. Essentially, Israel are trying to keep article 1 open with war in Lebanon, thus then upholding the possibility of closure of the straits again (Art 5). At the time of writing this, Israeli fighter jets carried out an airstrike on the town of Baraachit in southern Lebanon, according to Press TV/The four.
- Article 1 — End of war. Both sides declare immediate and permanent termination of military operations on all fronts including Lebanon, and undertake not to initiate any war or military operation against each other, refraining from the threat or use of force. This is the one “Operation Blue and White” and the late-June US strikes/Iranian missile retaliation directly threaten. Military Times
- Article 4 — US naval blockade removal. Immediately on signing, the US begins removing its naval blockade and any impediments against Iran, and fully ends the blockade within 30 days; vessel traffic restored in proportion to prewar levels; US removes forces from Iran’s proximity within 30 days after the final deal. US obligation.
- Article 5 — Hormuz reopening / Iran demining. Iran arranges safe passage of commercial vessels toll-free for 60 days only; traffic starts immediately; demining and removal of technical/military obstacles instated within 30 days; Iran to negotiate future Hormuz administration with Oman. Iran obligation — and the 30-day demining clock is the one your project memory flags against the Pentagon’s 6-month assessment.
- Article 10 — Treasury oil-export waivers. Immediately on signing and until sanctions termination, US Treasury issues waivers for export of Iranian crude, petroleum products and derivatives, plus all associated banking, insurance, and transportation services. US obligation — this is the one that actually puts Iranian barrels back on the water legally.
- Article 11 — Frozen asset release. US makes Iran’s frozen/restricted funds fully available upon implementation; procedures agreed bilaterally during negotiations; funds usable for any beneficiary designated by Iran’s central bank. This is what the MFA said the Doha delegation is going to Qatar to follow up on.
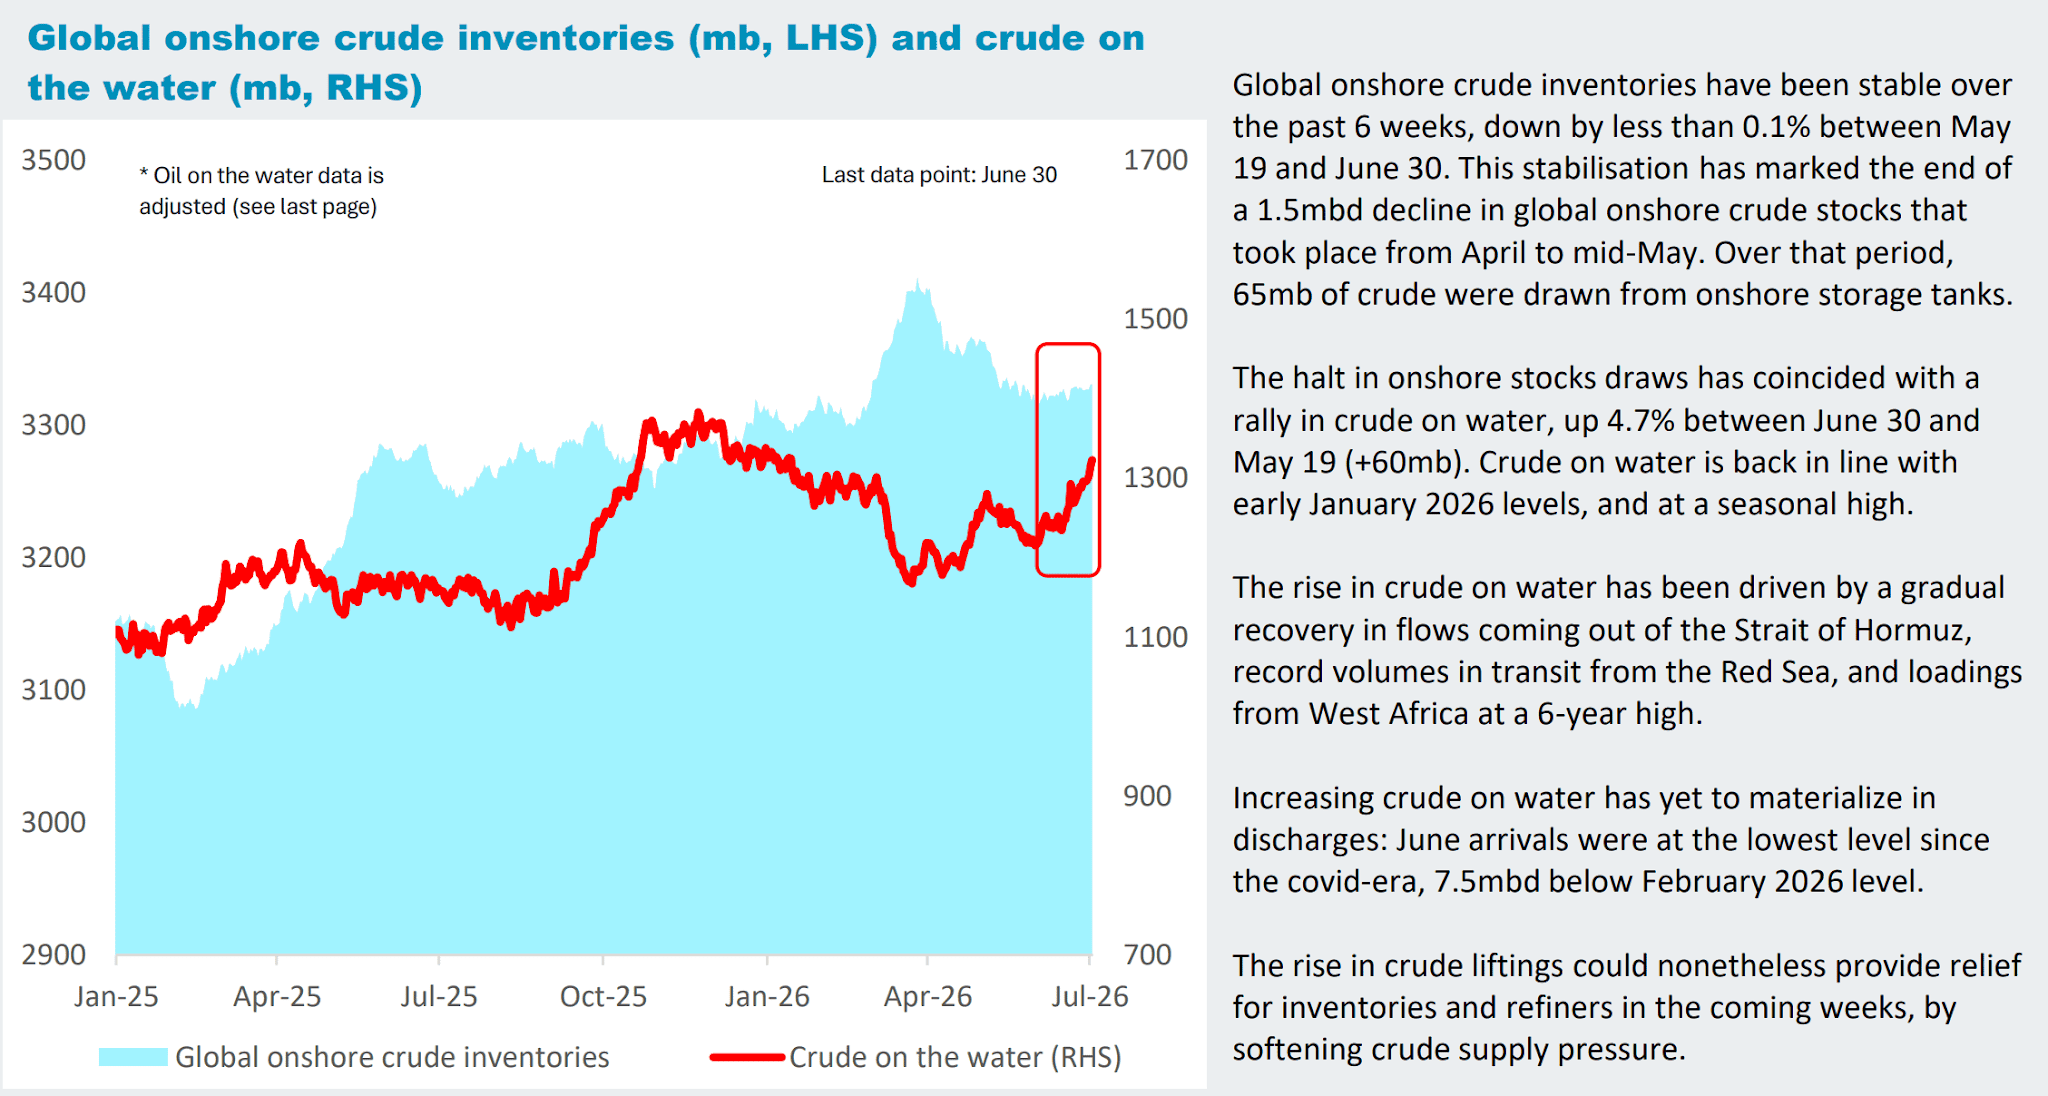
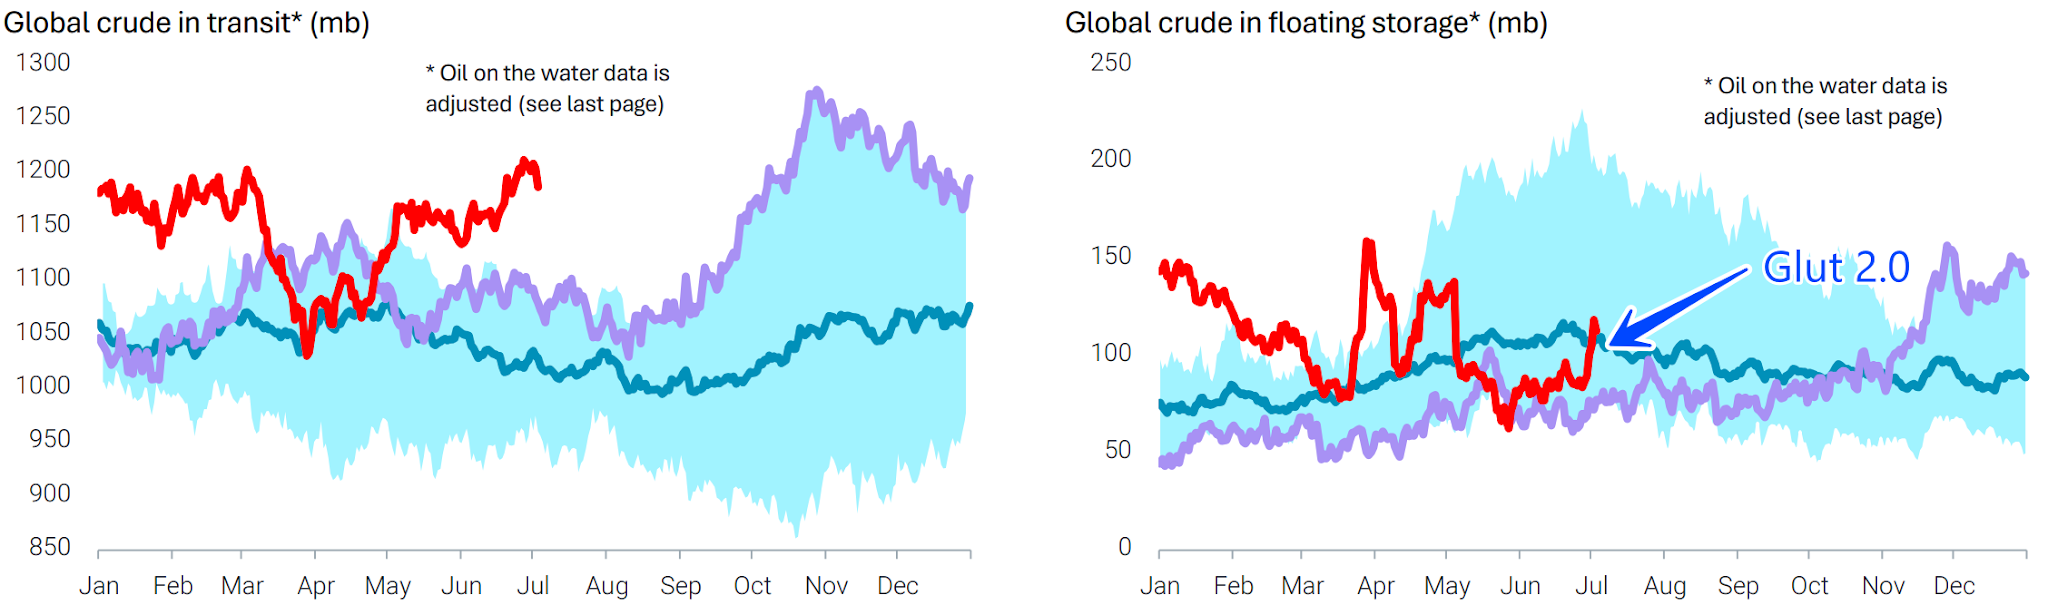

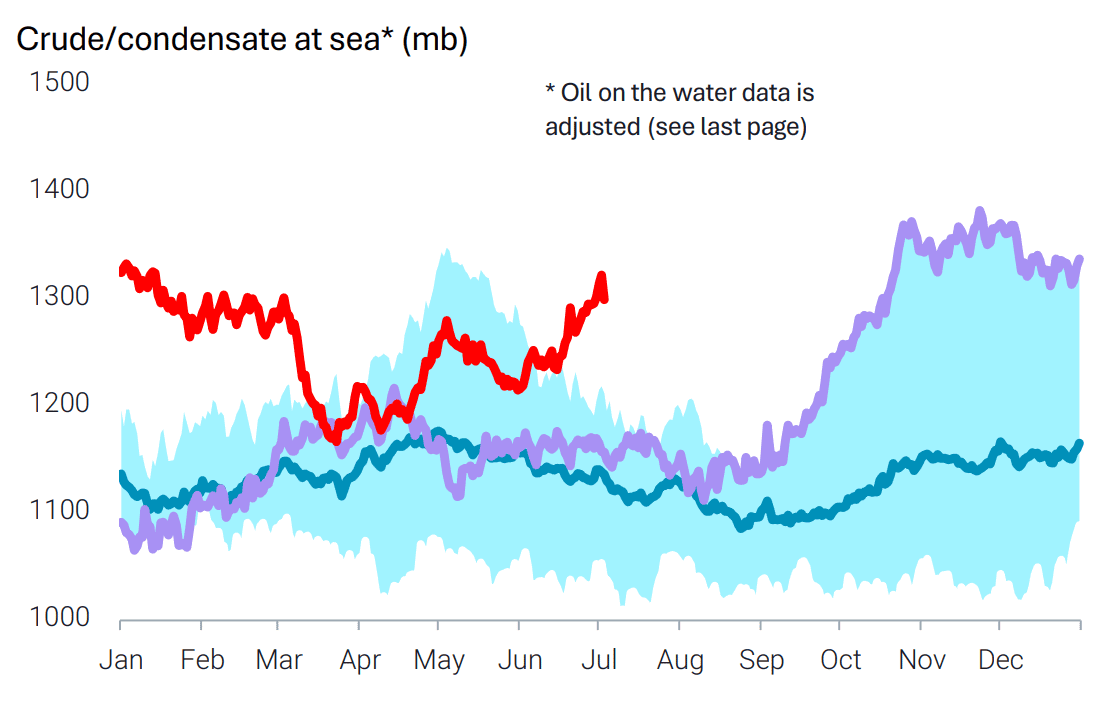
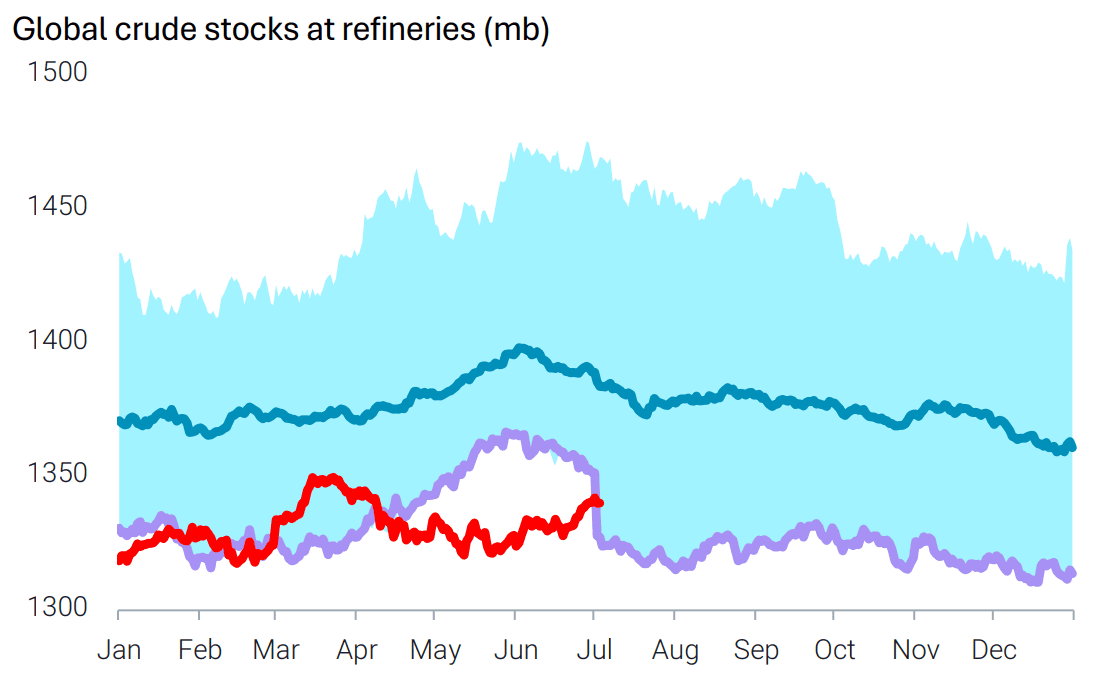
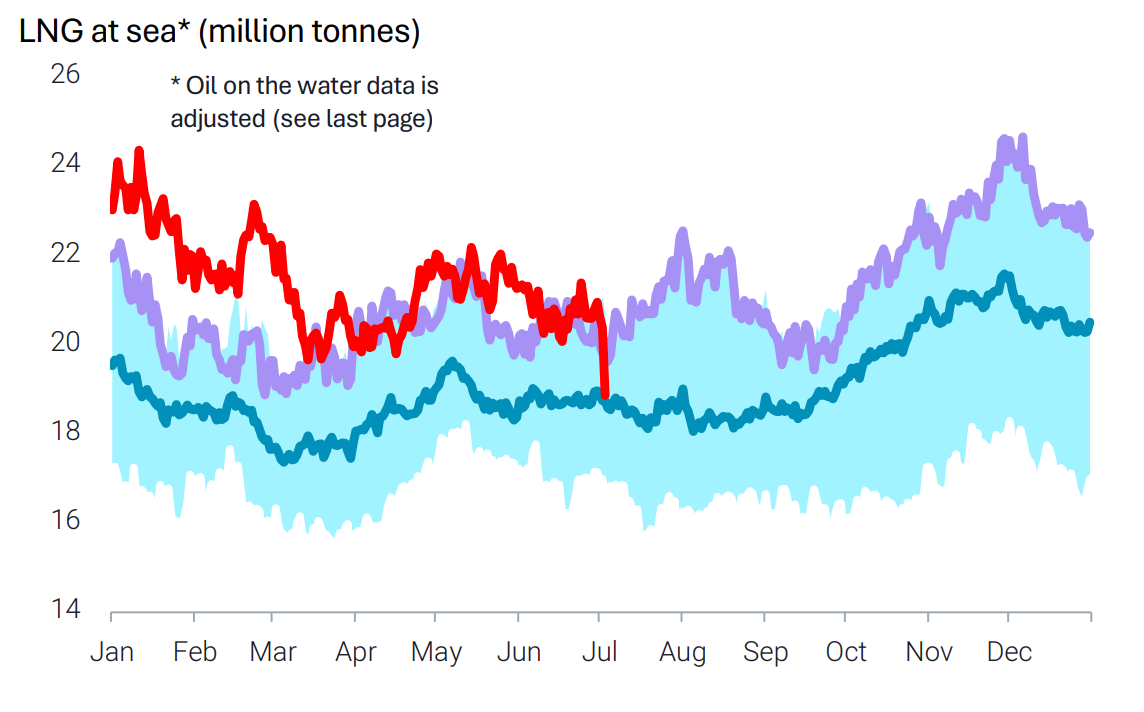
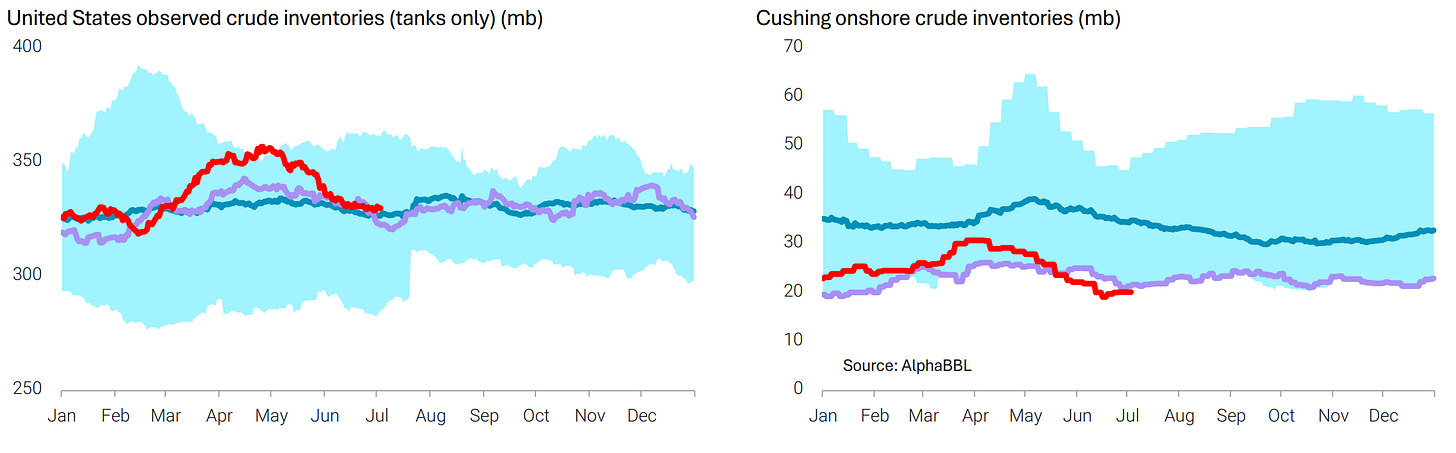
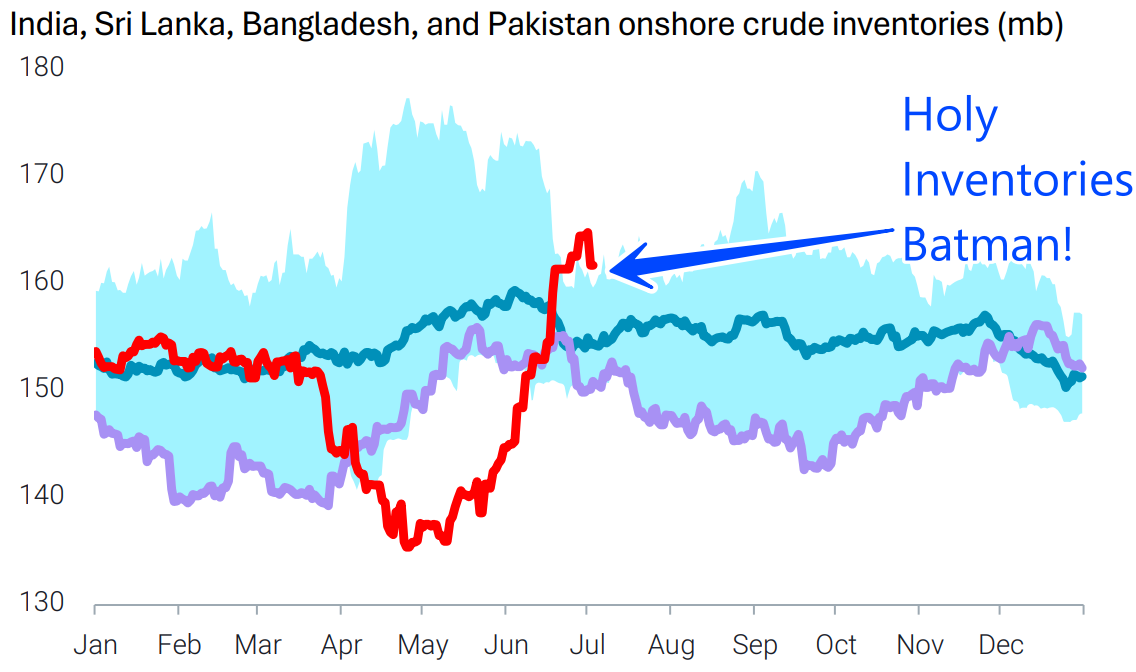
Source: Vortexa
China
Continuing on from above, I respect Nuttall, however I just don’t see 450mb to China been lost. Imports cut 4.5mb/d x 30 days= 147mb. If we want to say they cut imports from day 1 of the war, it’s the 450mb figure, but they did not. He also claims that transportation demand dropped. Maybe it did, given the spread of NEV v ICE cars on the road there.
Either which way, it’s academic. China are down on imports and they have Iranian ships that fled out of SOH to supply them. The fact is though that they are not offloading currently for fear of being on the wrong side of the sanctions which are ment to be now lifted. Kplr AND Vortexa information noted that China’s June import drop was demand destruction.
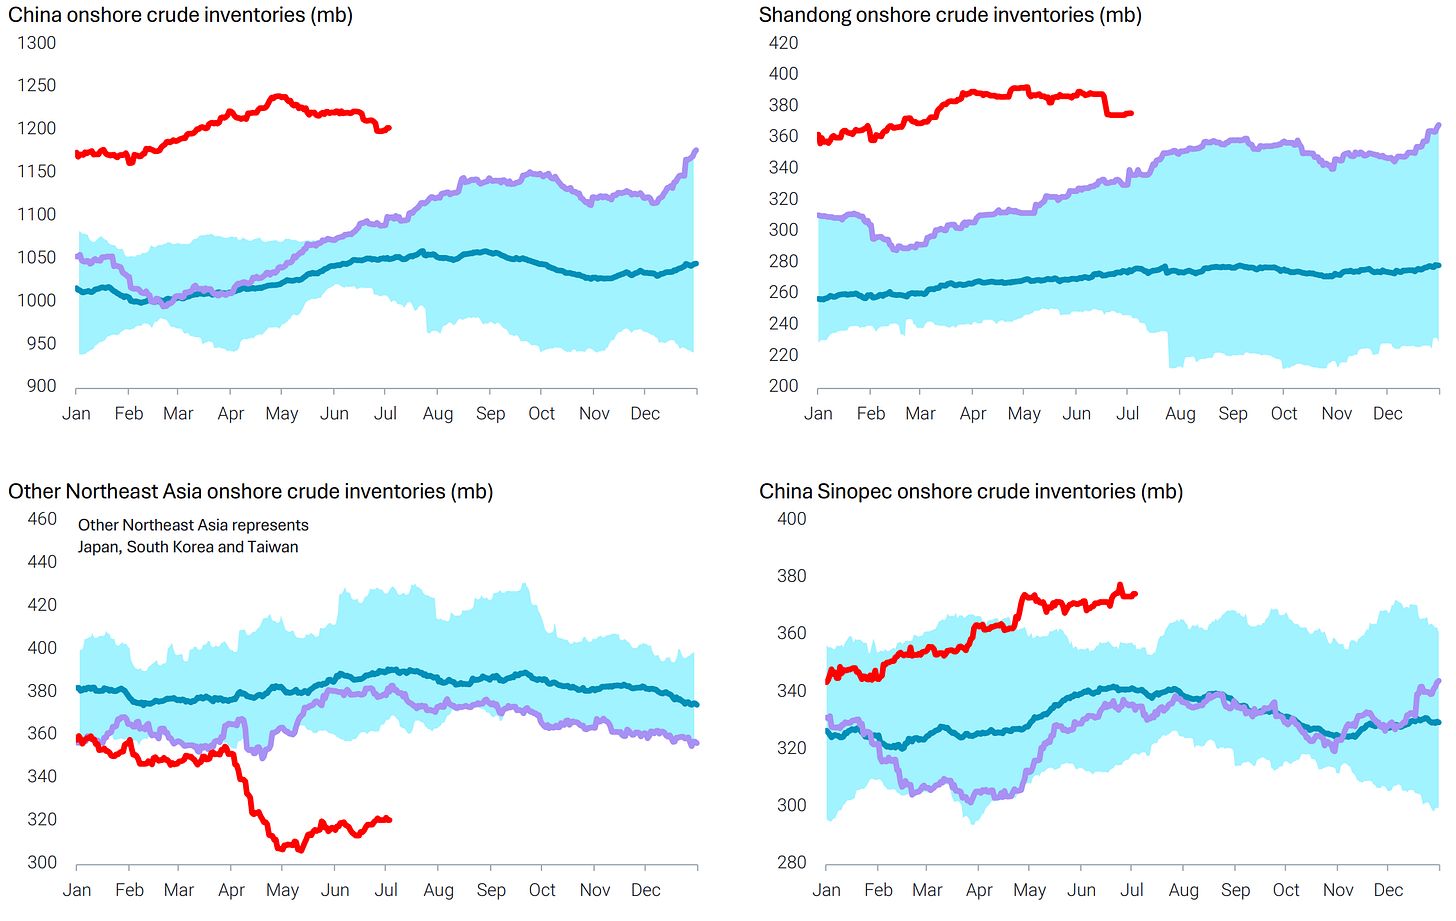
China implemented a rationing of oil from the very start. So this led to a lesser drawdown on stockpiles, both strategic and commercial. An austerity type move, with 1.3billion barrels of the black stuff (not Guinness) sitting in reserves.
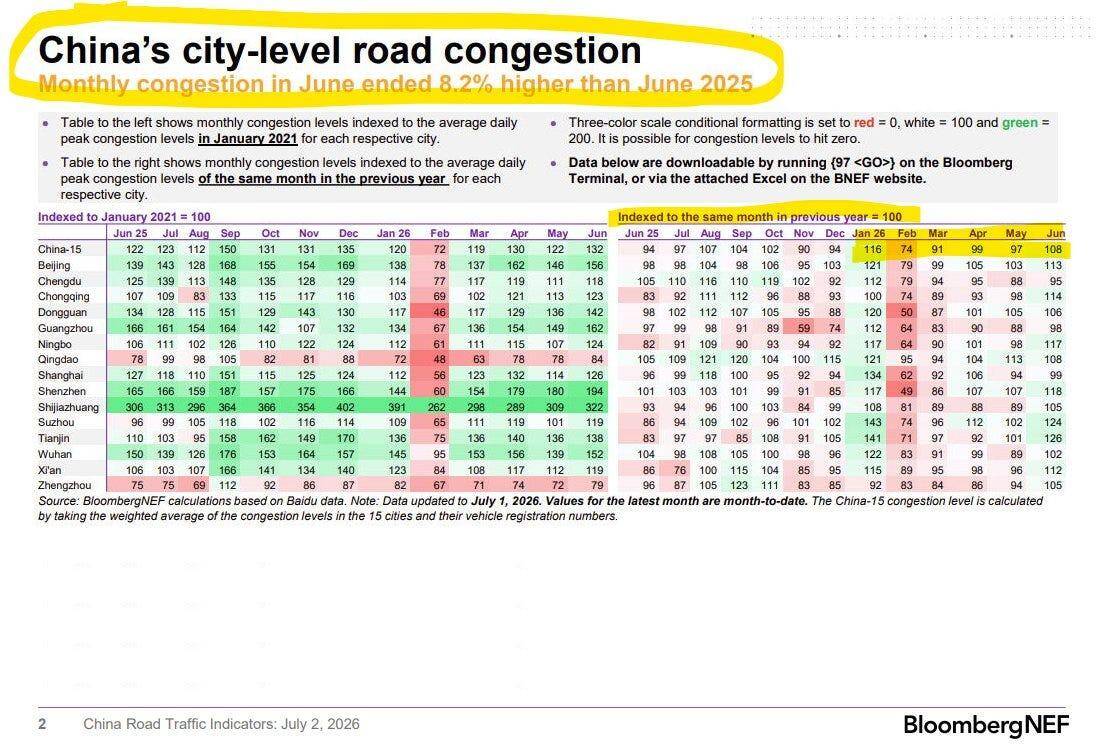
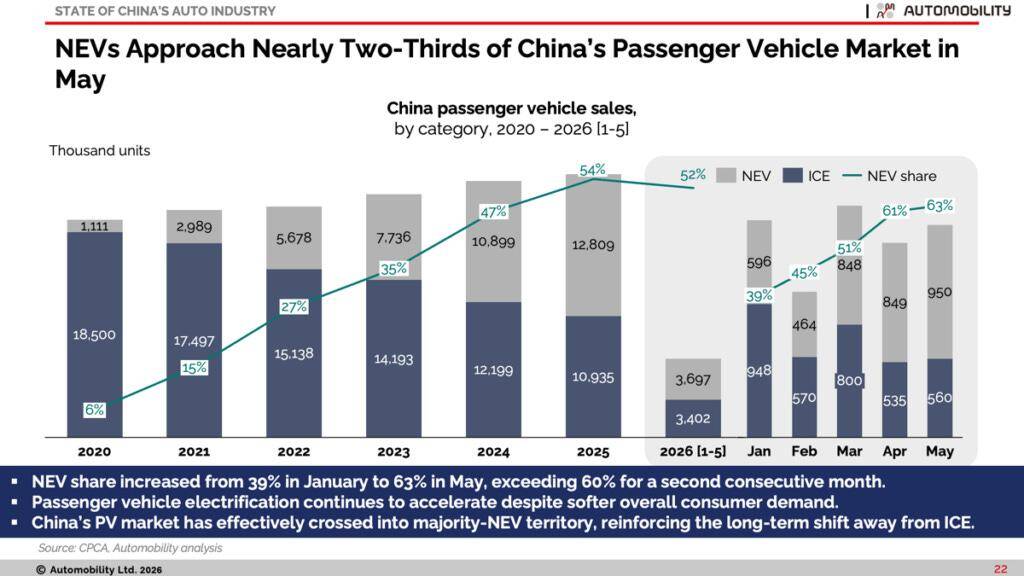
Goldman Sachs Samantha Dart has argued publicly that China’s grand strategy is now to ditch crude and pivot to coal and solar, and it squares with everything visible in the capital flows: enormous coal investment on top of reserves China already sits on. The car market tells the same story. NEV’s (New Energy Vehicles) hit 63% of passenger vehicle sales in May and have crossed into majority-NEV territory for a second straight month, outpacing internal combustion for the year to date. The barrels China isn’t importing aren’t deferred demand waiting to snap back – they’re structural. Anyone modelling a Chinese restock as the bull case is fading the wrong signal. I’m wrong if Kpler and Vortexa show July-August imports rebounding as margins recover – but the congestion, the inventory stack, and the NEV curve all point the other way.
NEV (New energy Vehicles) are now outpacing ICE (internal combustion engines) for the YTD 2026 and were 4% higher than ICE vehicles last year. This is Grettas dream!
The Net Net
The system is healing. It might not look like that when you look at the Cushing chart or the US SPR charts, but more than ample volumes are flowing out of either strategic reserves or Hormuz. The risks: Gas volumes at a global level have taken a sharp pullback. Refined products are kinda tight and Israel is intent on blowing up the situation again. The risks were skewed to the downside after the initial sticker shock of the closure of The SOH, however now, the risks are firmly to the upside. What would be a major catalyst?
- A breakdown of the MoU negotiations. 30% probable IMO
- China returning full flight to the market 55% probable next 30 days IMO
- Both happening at the same time. 7% IMO.
If Samantha Dart is right in her assumption, China will NOT return to the crude market at levels seen before. I buy it. I see it and this fits perfectly with my research in Coal investments and demand in Asia. Net net? This is still an upside driver, should it actualise but won’t be surprised if it doesn’t happen in 2026. The market is firmly expecting their return though.
Commitment Of Traders Report
MM pressed shorts +11.3% (+23k) this week while trimming longs -4.0% (-12k). MM are MAXED out on their shorts. I feel a short squeeze coming. Add to this OR
(Other Reportables) PUKED longs -19.2% (-48k).
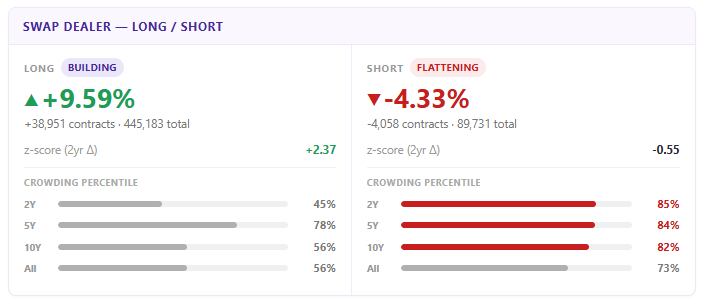
That moved MM from 1.4:1 long to 1.2:1 long – at the 35th percentile (2yr) on the long side. OI contracted -6.0% (-230k) – net unwind, not rotation. Fresh participants left the market this week. SD (Swappies) added longs +9.6% (+39k), with SD shorts at the 85th percentile (extreme hedging-cover regime intact) and longs at the 46th.
The read: I feel strongly that there is a short squeeze at play now from the MM being at 98th% 2yr crowded short. See below.
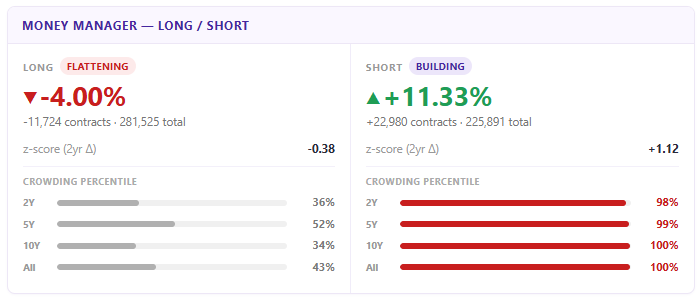
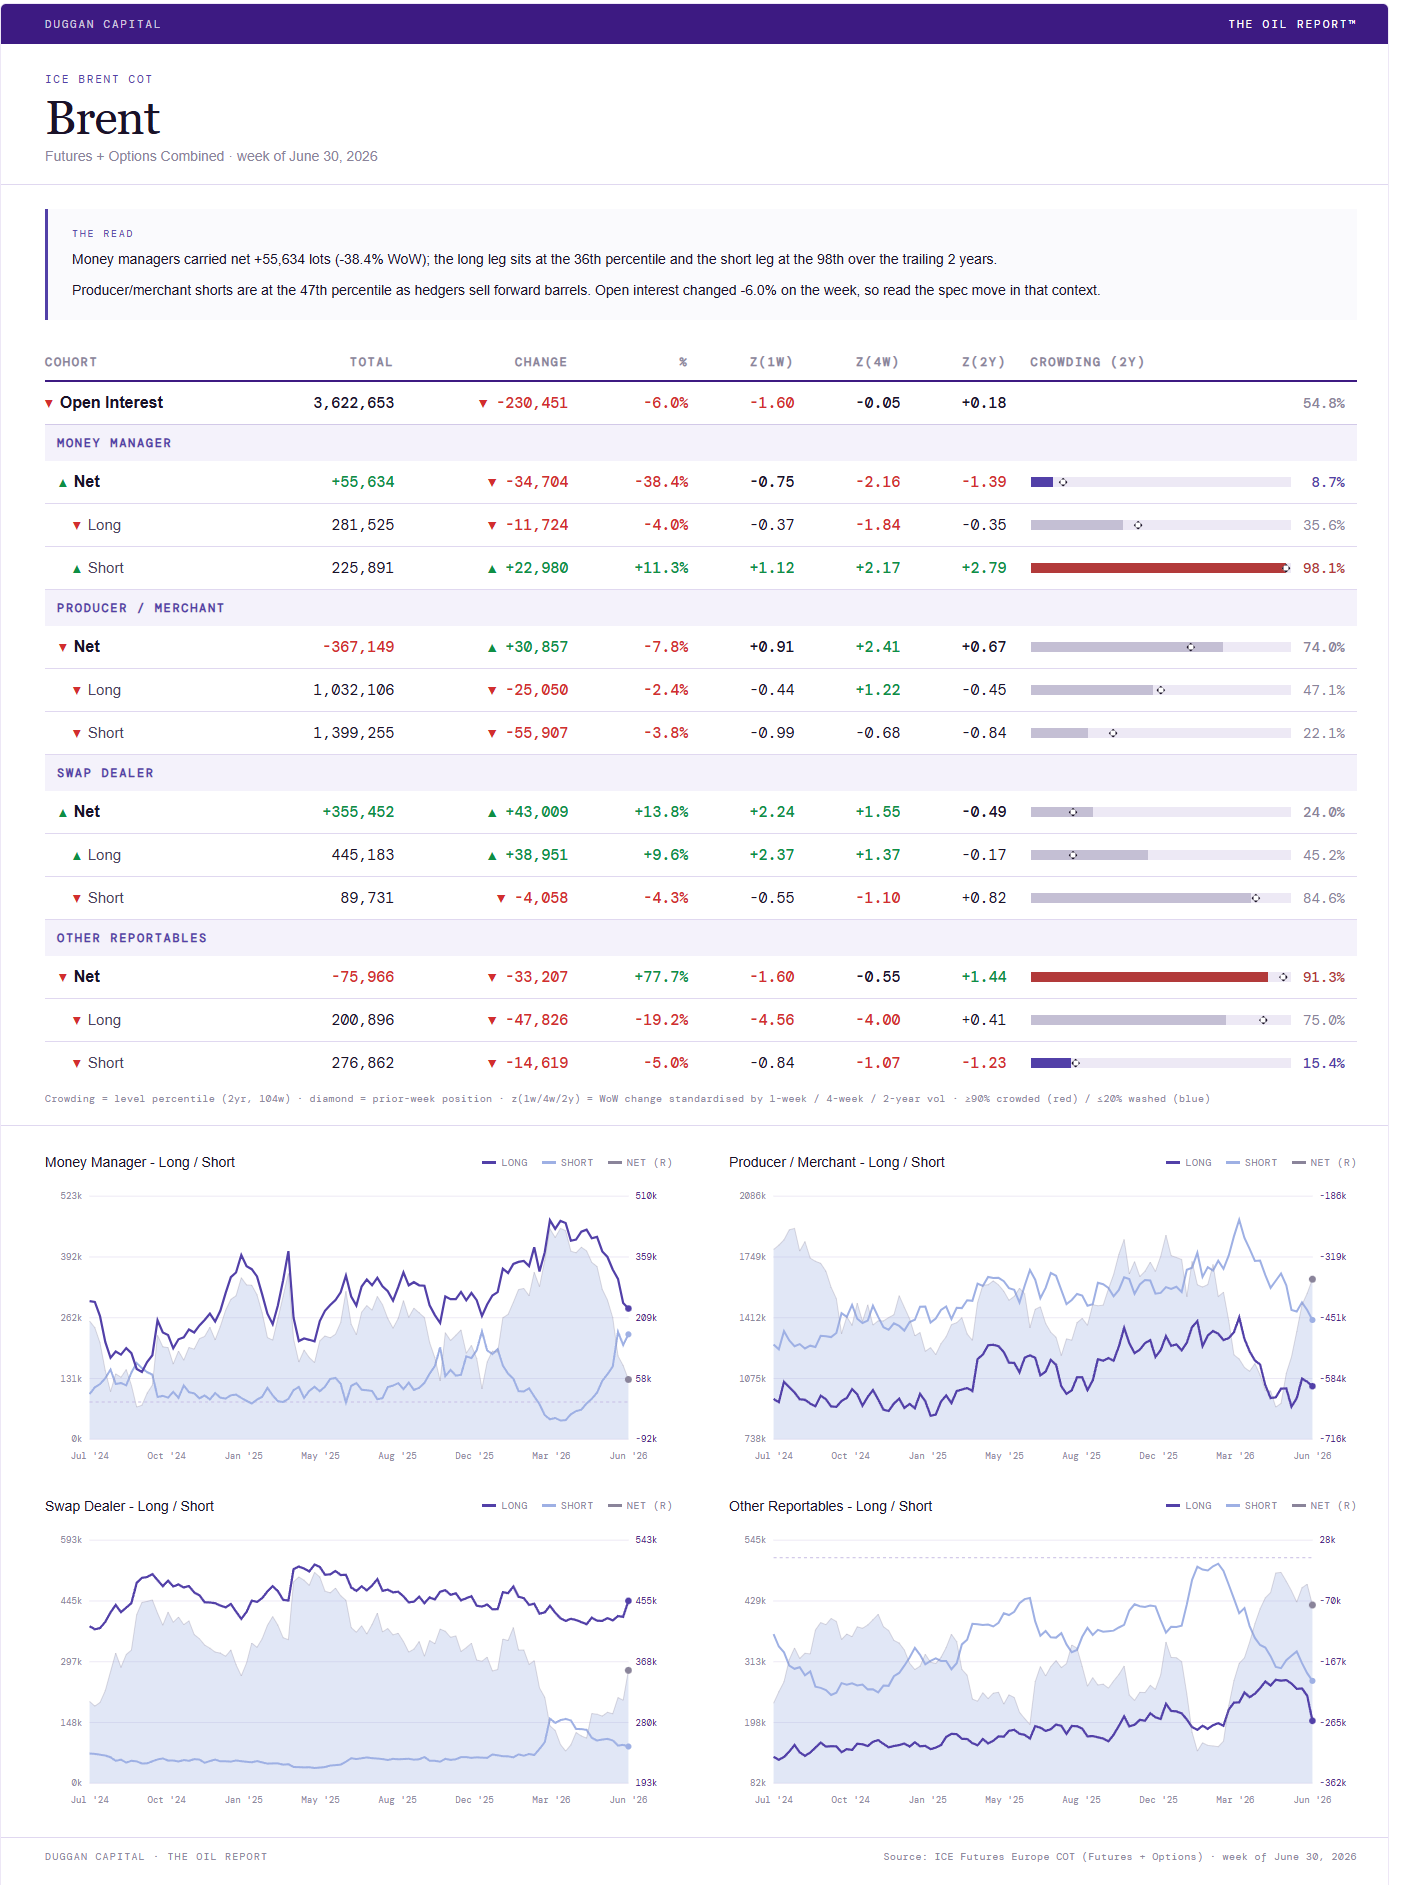
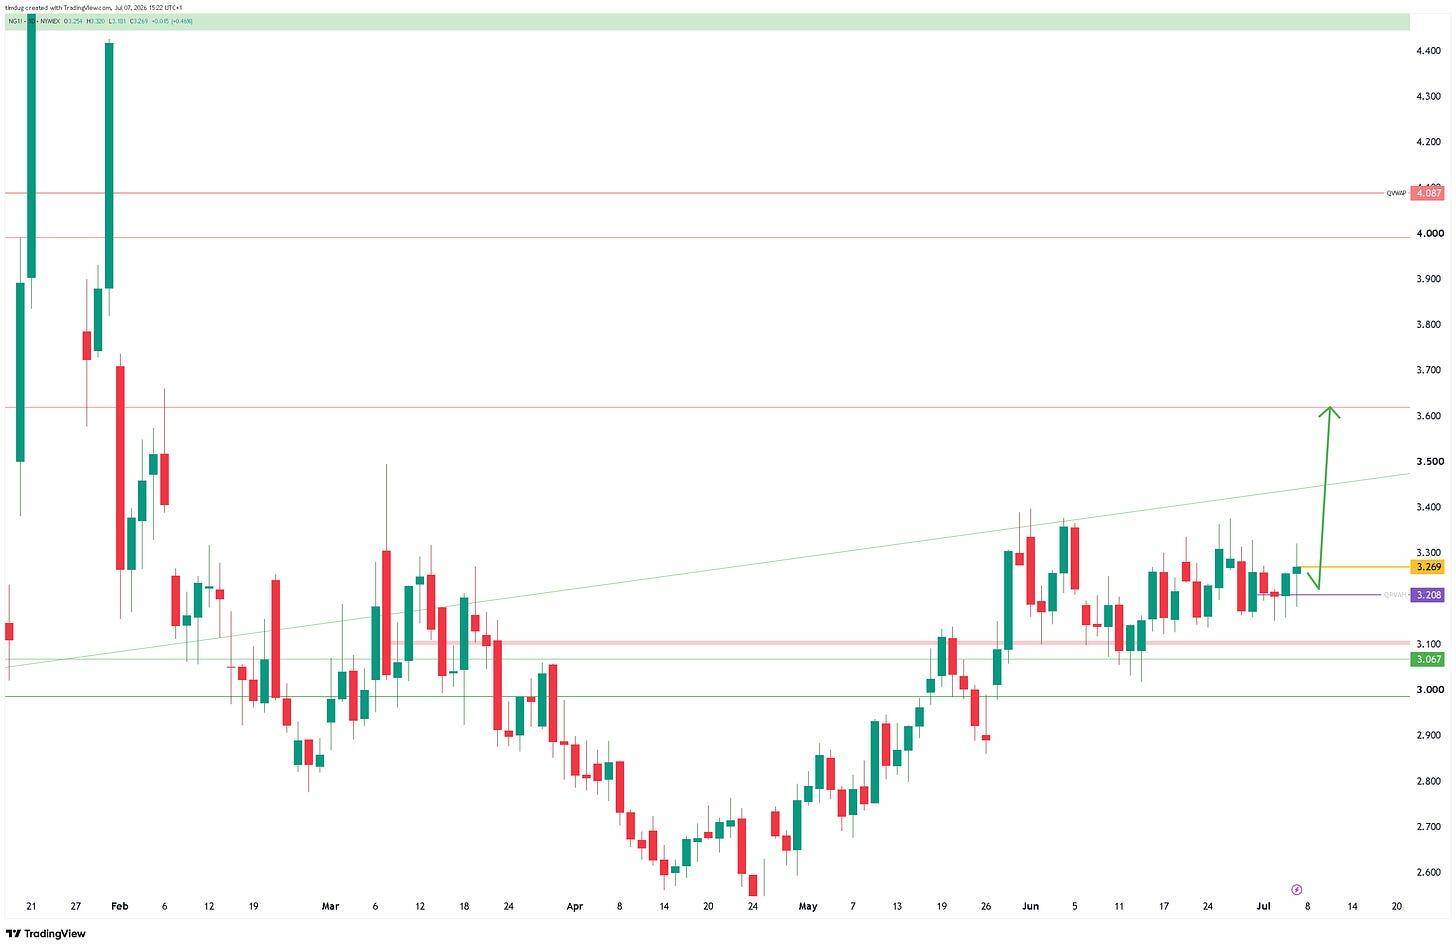
As per the COT, it looks like Money Managers are short as hell here. Pressing another 11% 23k contracts last week. Also, now that OR (Other Reportables) have had a legitimate puke out -19.23% (47k contracts last week) the run way might be clear from this upside.