


Crude finished last week firmer, capping what has been one of the most volatile weeks in oil market history. We saw the 2nd largest intraday move, a 32.05% ($32 day) range day, April 17th 2020 (a $52 range day) being the largest.
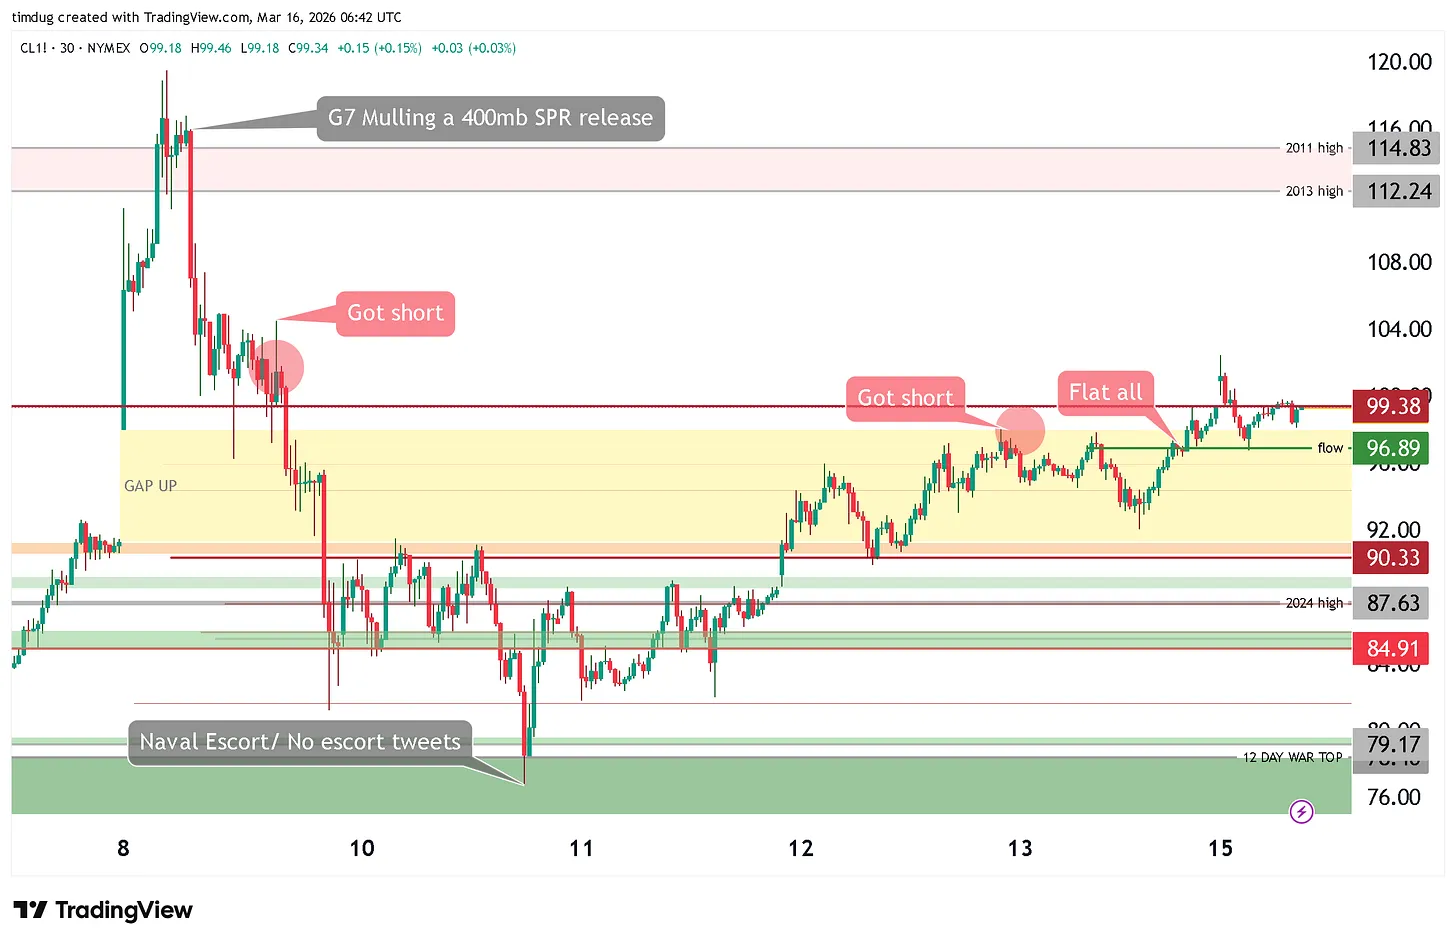
The market focused squarely on whether tensions would de-escalate and on the operational status of the Strait of Hormuz, which for all practical purposes continues to function as though it were closed. Any softness seen on price was lifted into the Friday close, as traders continued to price in upside risk signaled by the Naval expeditionary force deployment to the area.
From the U.S. side, rhetoric and action remain aggressive and mixed on the potential duration of hostilities. We are being told this is ‘not a war’. Trump said the U.S. would escort vessels through Hormuz, offering little indication that tensions are easing. This is the largest concentration of U.S. air and naval power in the Middle East since the 2003 Iraq invasion. Polymarket odds for U.S. troops on the ground in Iran rose to roughly 40% by month-end, now settling to 30%- Monday 6am GMT.
We must remain exposed to further upside for the foreseeable future- the reasons and catalysts are outlined below. Otherwise, you are short volatility of the situation, which in itself is not a bad bet, but you must be relatively fast in banking, as the situation can reprice vol back in quite fast.
More Supply Absorbed
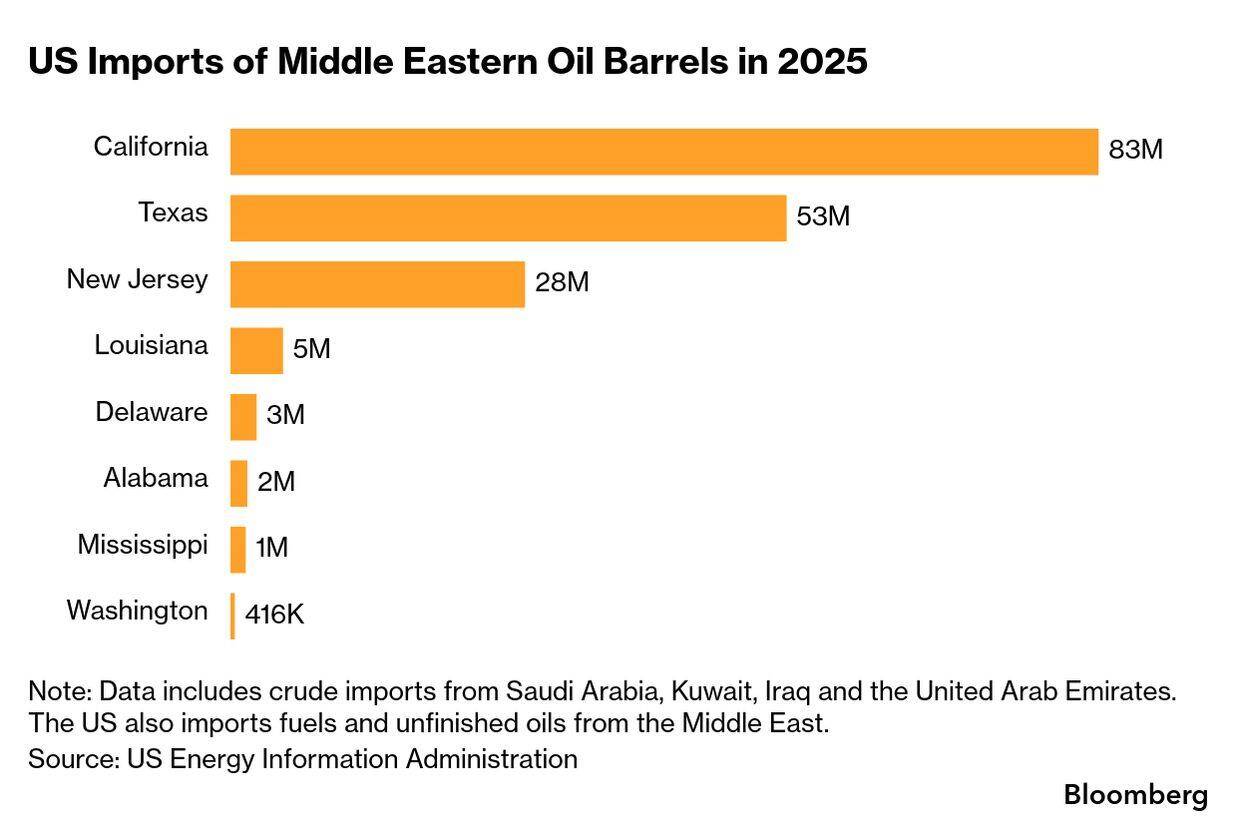
As we all know, The G7 agreed on its largest SPR release in history of 400mb. And as well also all know by now, it has been thin gruel for end use energy consumers in the past week. Prices rose with little foresight on easing of the situation and restarts in production and shipping now running at least a 4 week lead time.
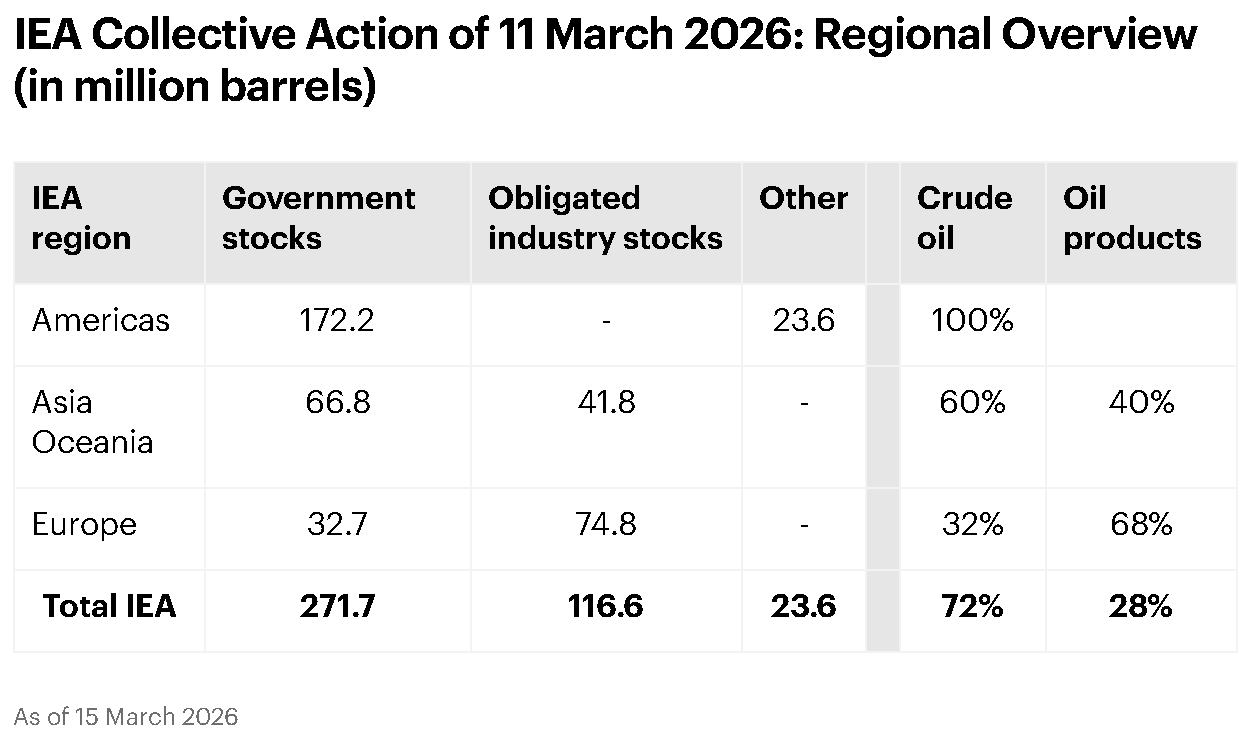
I put a note out in Substack Friday about supply. In Trump 1.0, he was ‘draining the swamp’, in Trump 2.0, he is draining ‘The Glut’.
- G7+400MB spread over next 90 days.
- OPEC now targeted output +206k bpd for March
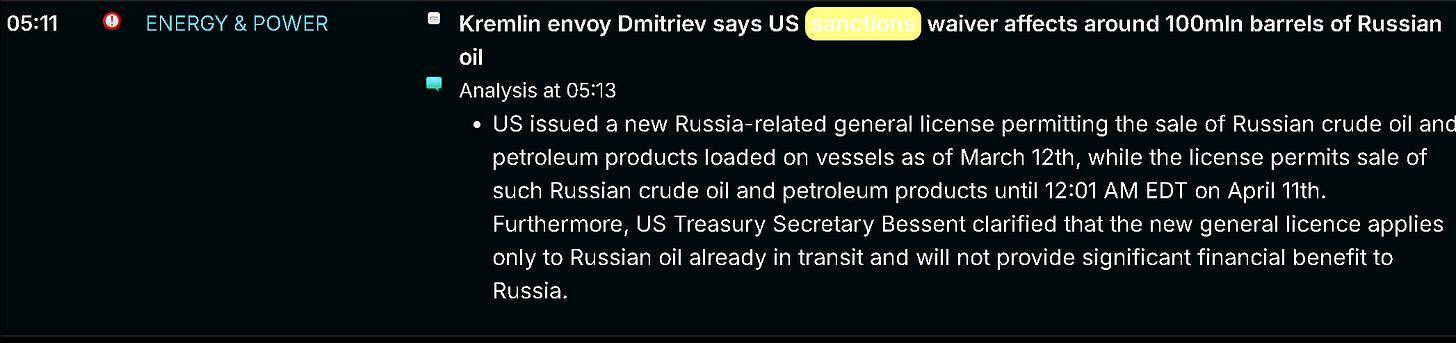
- Russian floating ‘Glut’ stocks to now transit freely and land +100m barrels minimum.
Tally, 500mb+ and increased OPEC flows serve to put bulls on notice and entice bears to sell long duration risk.
Brent Oil Price Forecast
Every new Brent Oil analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Brent Oil forecasts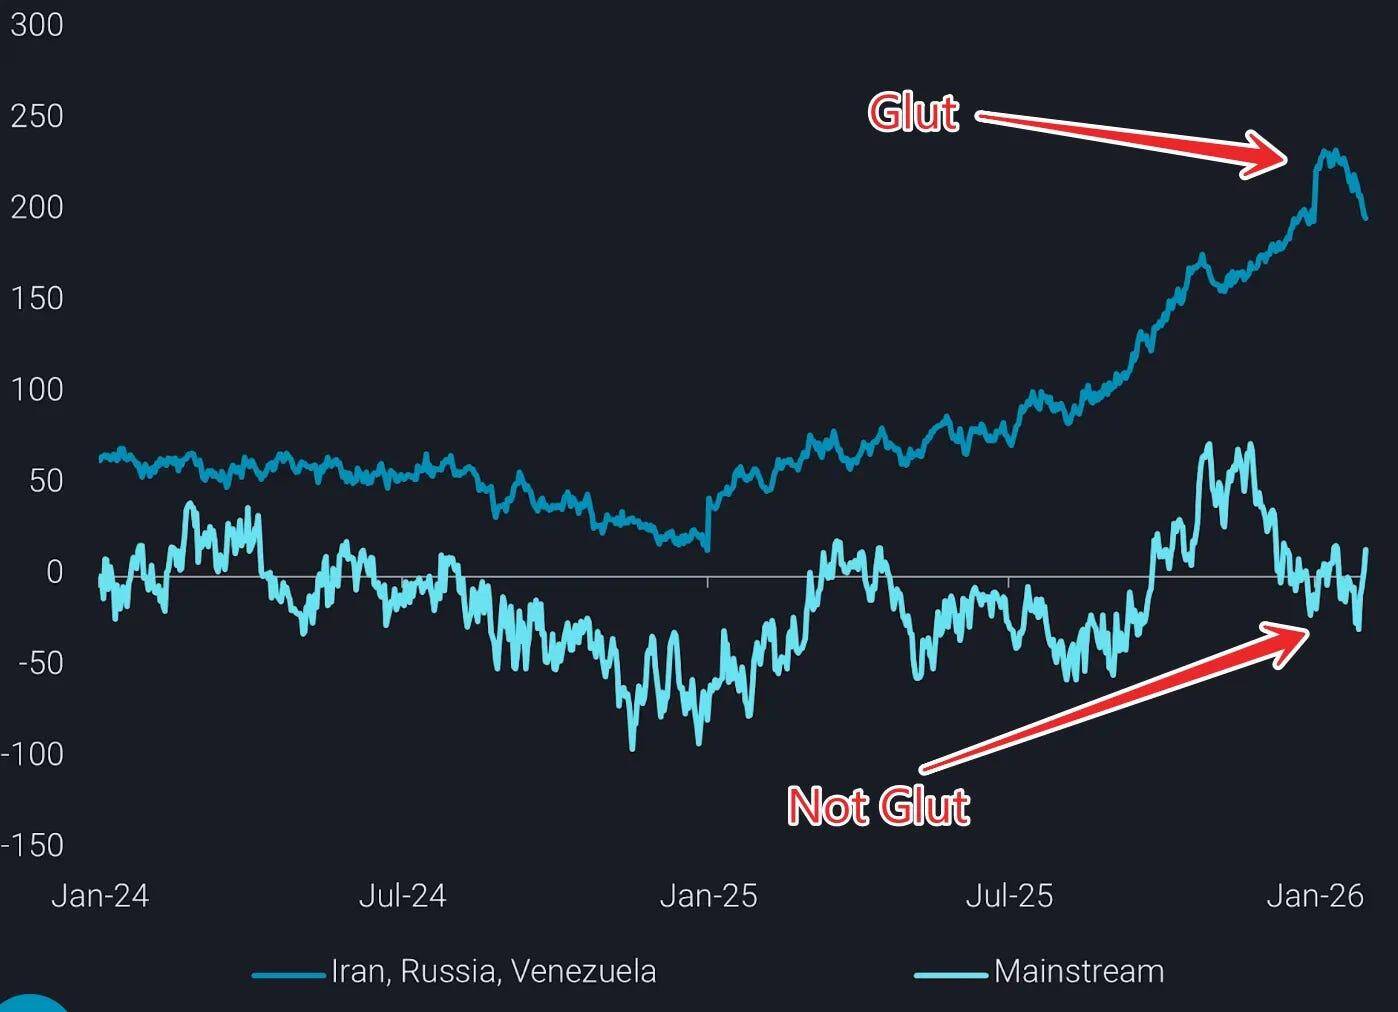
Don’t Get Too Excited About Ship Escort
This is the risk that we can not price out. YES, One would like to sell futures and buy dated here but there is too much that may come. Maverick, Goose and the boys are going to make sure there is safe passage. The only problem is that we must see this work first, rather than price out risk. I see this as the major point of hostile escalation over the coming weeks. Expect conflict on the water to serve as a moderate continuing bid on front month prices. Expect the Houthis to launch attacks on vessels that are now re-routing to collect oil from the Saudi East-west pipeline. This will occur in the Straits of Mandeb.
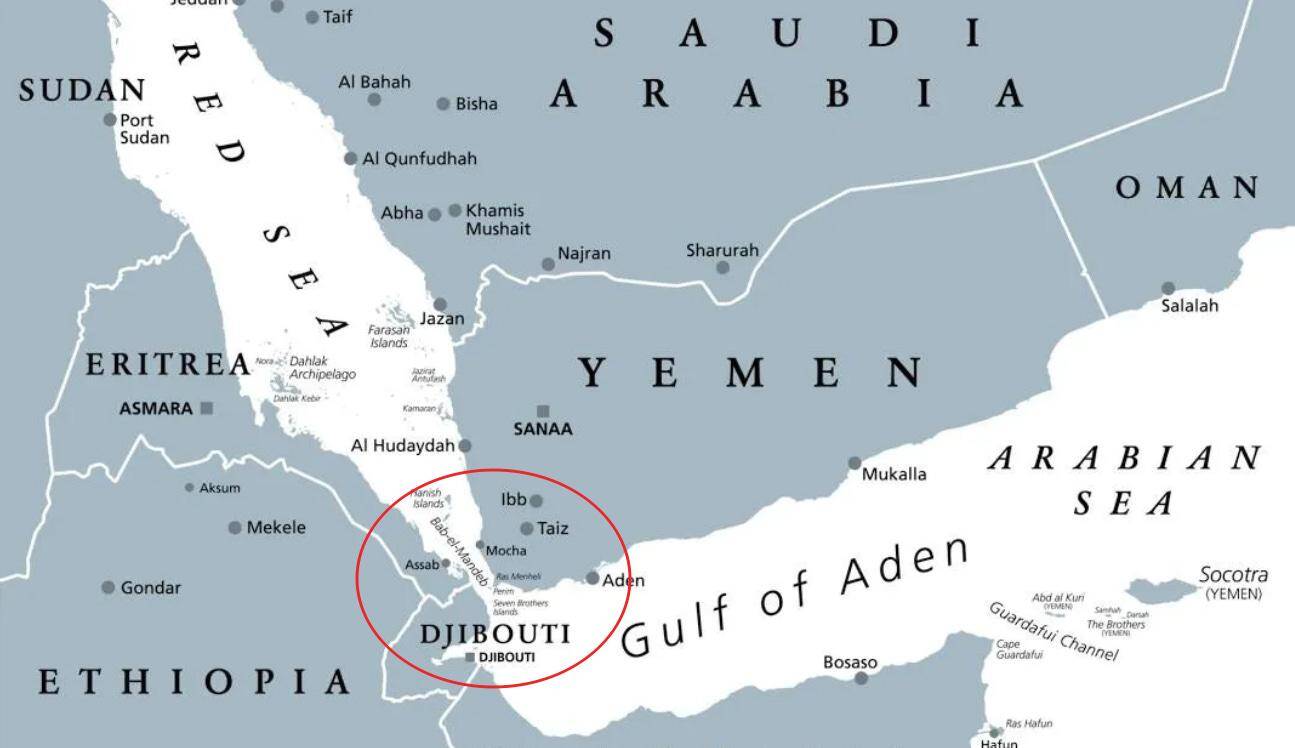
Don’t even get me started on the headlines about mines being laid in the straits- a story that was like whack-a-mole all last week. Reports came in each day, when finally an Iranian official came out stating they were not laying mines in The Straits and Trump said they had taken out small boats that had attempted to lay mines.
The Forbidden Island- Khrag Island
Known as the ‘Forbidden Island’ due to strict military control, this ancient coral outcrop processes 90 percent of Iran’s crude exports while guarding millennia of human history.
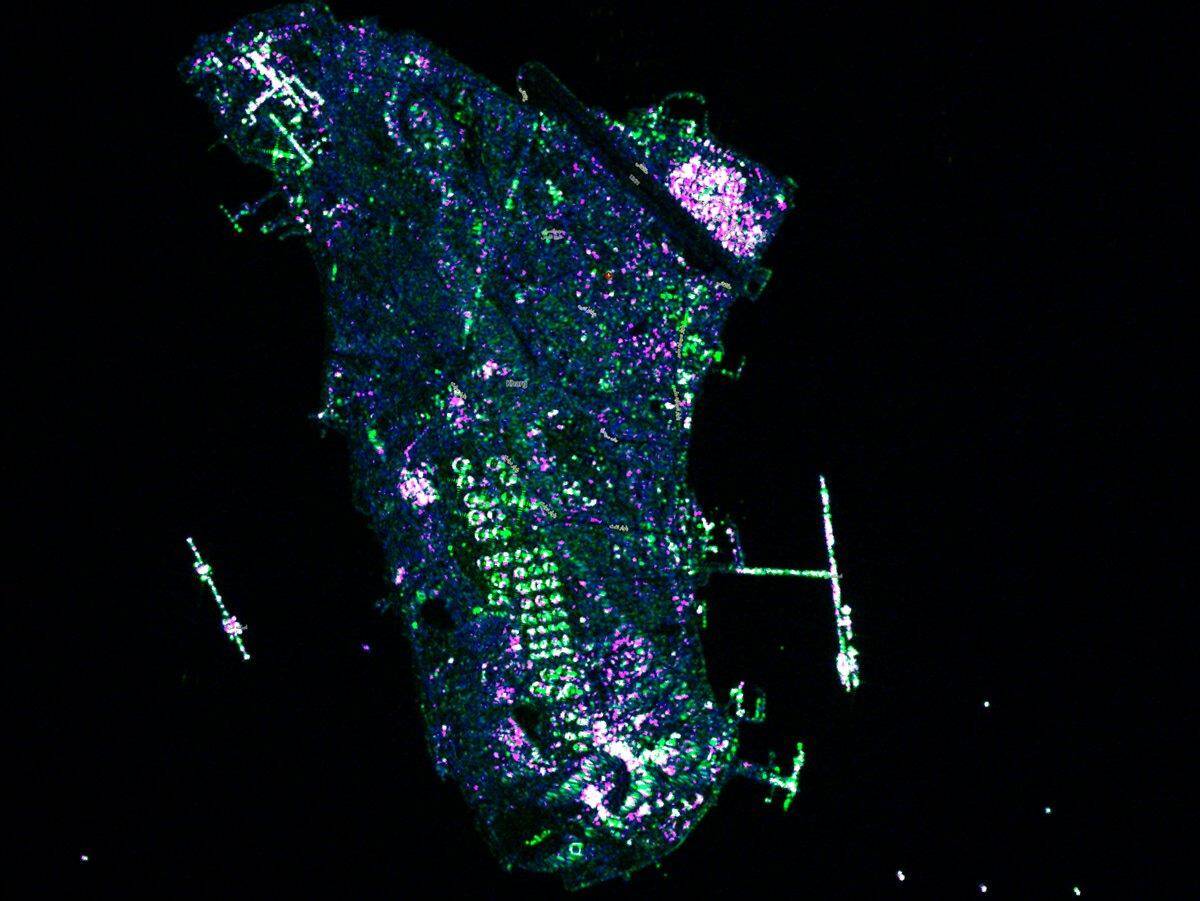
As mentioned, last week-There is probably no greater single point thing Trump could do to secure USD hegemony than capture/control Khrag Island. This would secure that an incredible amount of the world’s oil continues to be priced in USD, thus translating to a much stronger steadier USD, while Trump and Bessent continue to execute the Make America great again plan. For all that I hate about Trumps servitude to Israeli Zionist ambitions, his attempt at gaming global FX here is strong. It is a game of trying to serve 2 masters.
Master 1– Re-shore manufacturing in the US. Requiring a MUCH lower USD. STATUS: Not going great.
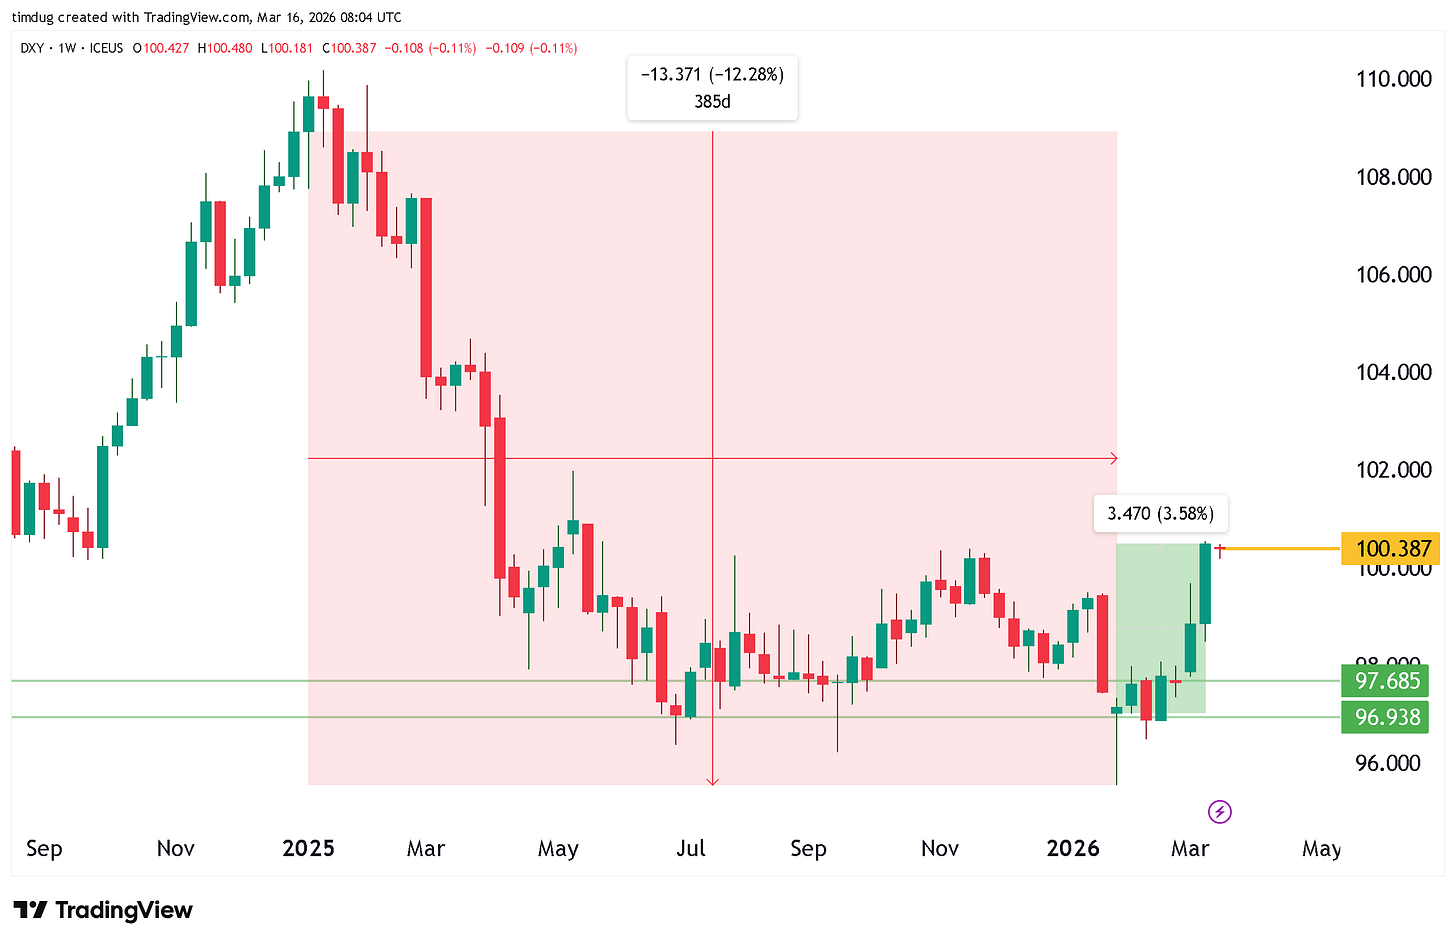
Master 2– Maintain DXY dominance to protect Treasury sales and interest. STATUS: Going great. DXY down 12% Jan 25-Jan 26. Now Q1 2026 Up 3.45%.
No Quick Exit In Sight
There is no fast off-ramp for Trump now. He cannot back out. A lot say that he needs to find an exit, however, because of Khrag Island, I do not believe he wants an exit. He wants dominance and full domain control of the area. They will do boots on the ground.
Opposingly, Iran will not pander. They hold the line they will not return to negotiations, citing the disgusting US attack on an Iranian school.
To Govern Is To Plan Ahead
Queues at the pumps are now being reported from The UK, France to China, Thailand, Pakistan. This was as I suspected would happen 2 weeks ago in ‘Price Discovery’ 2nd March 2026.
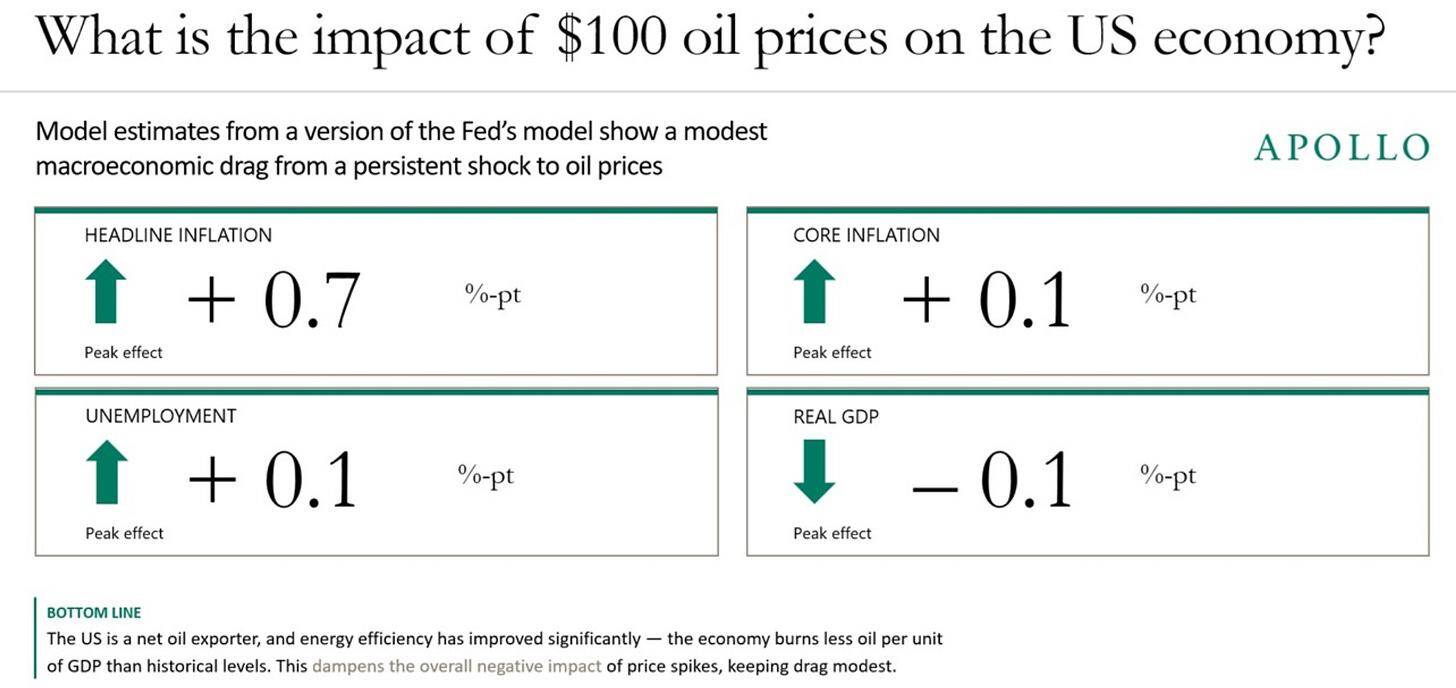
The G7 shot their shot and the market priced it out from the moment they had their first meeting. I will easily criticize the G7 for their incredible laissez-faire approach to decision making over the last 20 days. They should have had their meetings and strategic plans already in place the moment Trump sent the first carrier group. Even at that, they should have had a coordinated strategy in place long before. It’s not like this was never a risk. If it’s above a 10% risk, you must have a strategy on the shelf. They took over 2 weeks to come to an agreement on the size and timing of the SPR release and we still have no fully defined deployment plan. Only a headline plan and agreement. It is a devil-may-care attitude that is now going to spike inflation out of their control. This is the next phase. Global basket price reverb.
Commitment Of Traders Report
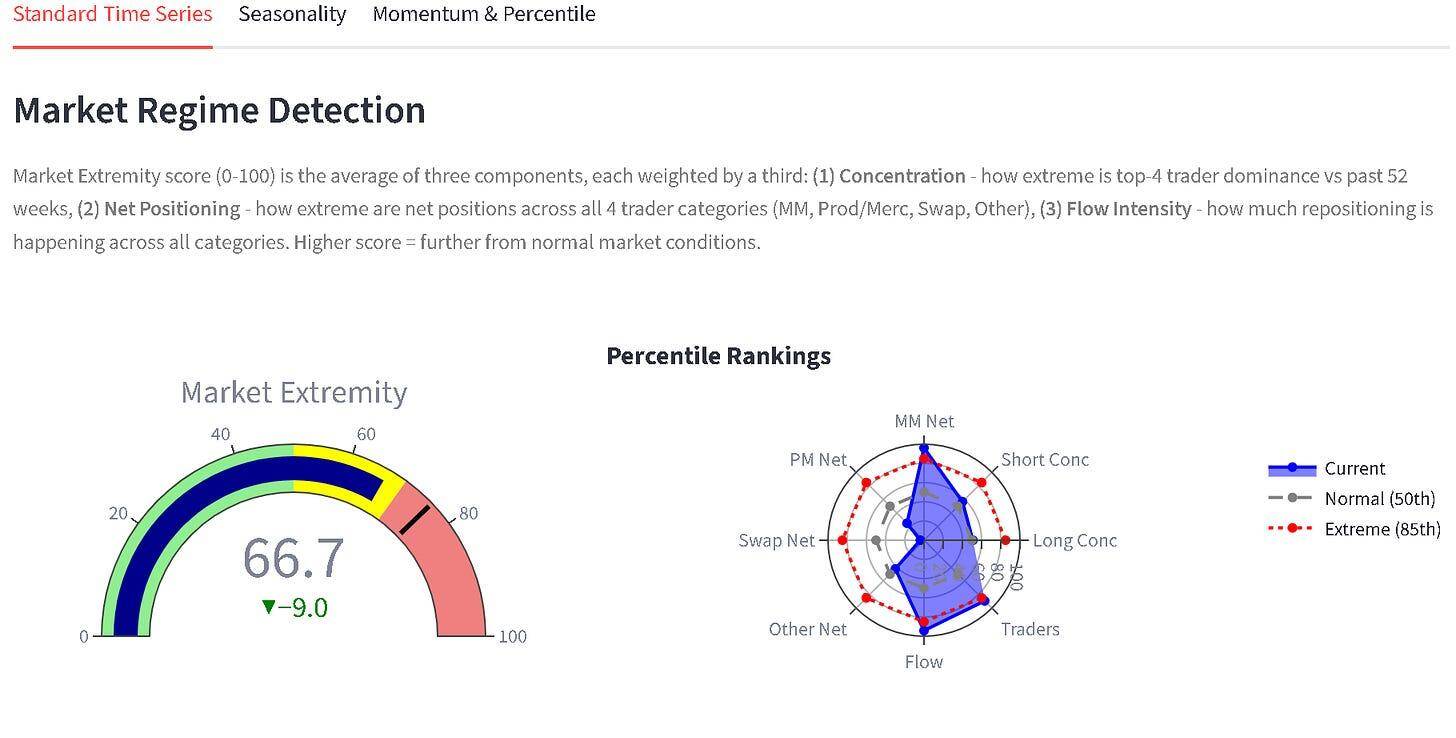
Here is the general snap shop from our C.O.T tool. Notice a theme?
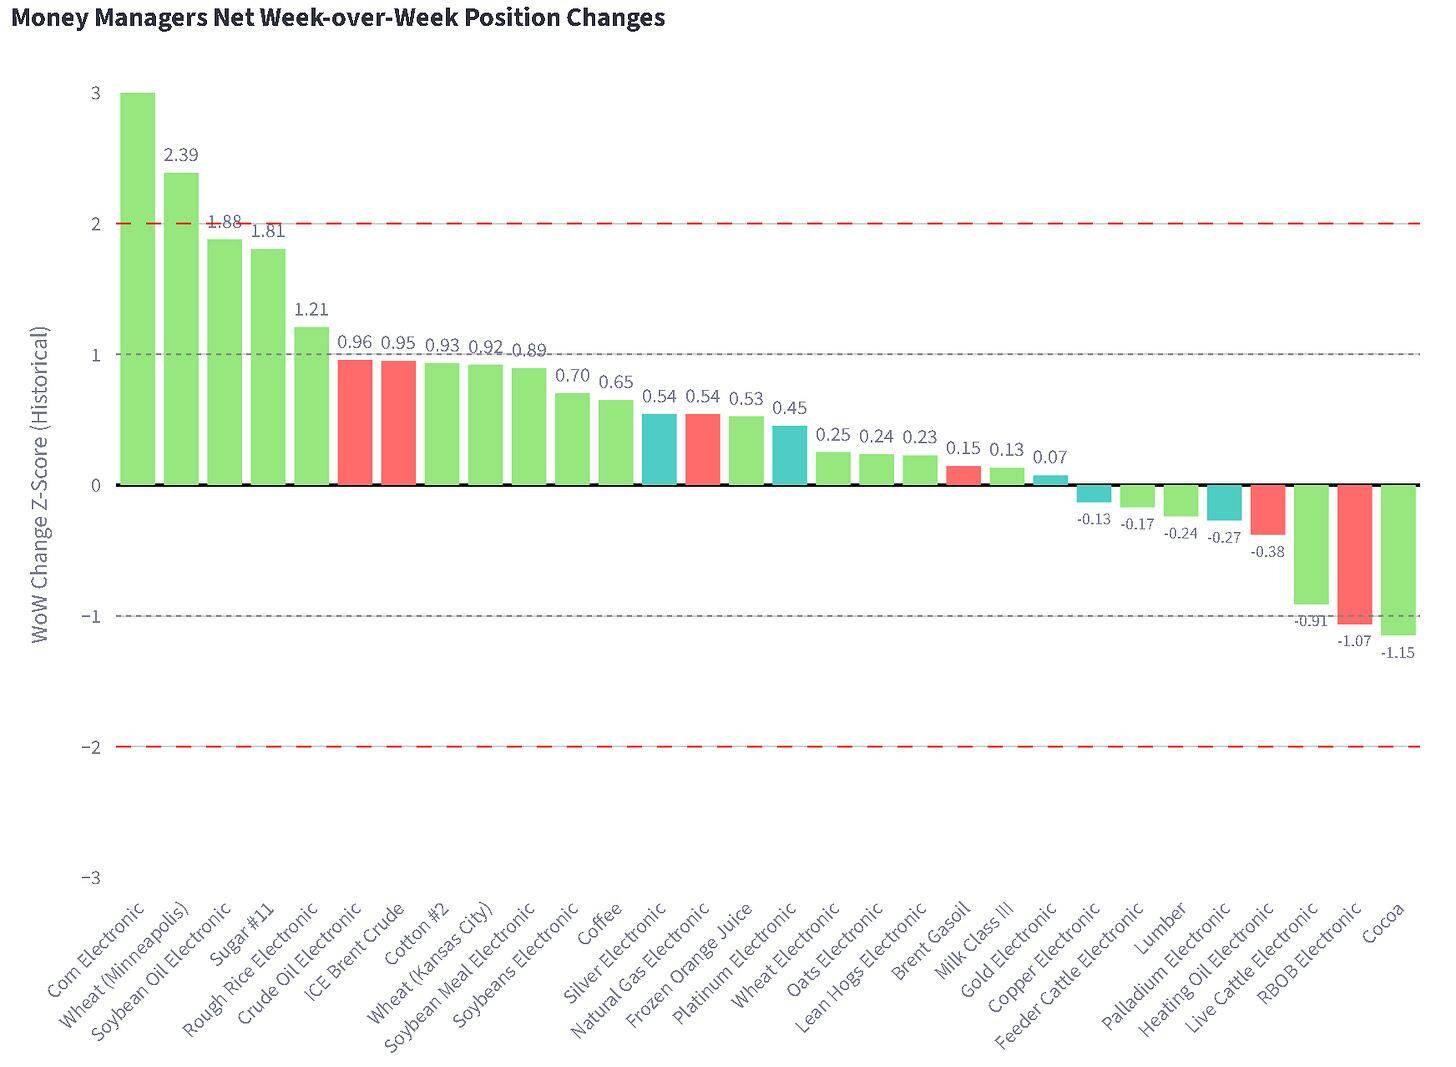
In summary: The positioning data suggests a market still structurally bullish but increasingly crowded. Commercial hedging surged into the geopolitical premium, money managers appear saturated on the long side, and swaps positioning implies large institutional clients remain heavily long crude risk.
- BRENT Open interest -99,272. Total 2,951,702
- BRENT Producer/Merchant Long -12,434. Total 1,092,293
- BRENT Producer/Merchant Short +46,354 Total 1,504,000
- BRENT Money Managers +16,204. Total 367,329
- BRENT Money Managers Short -24,250. Total 80,361
- BRENT Swap dealers Long Total +4,174 Total 408956
- BRENT Swap dealers Short -925. Total 66,391
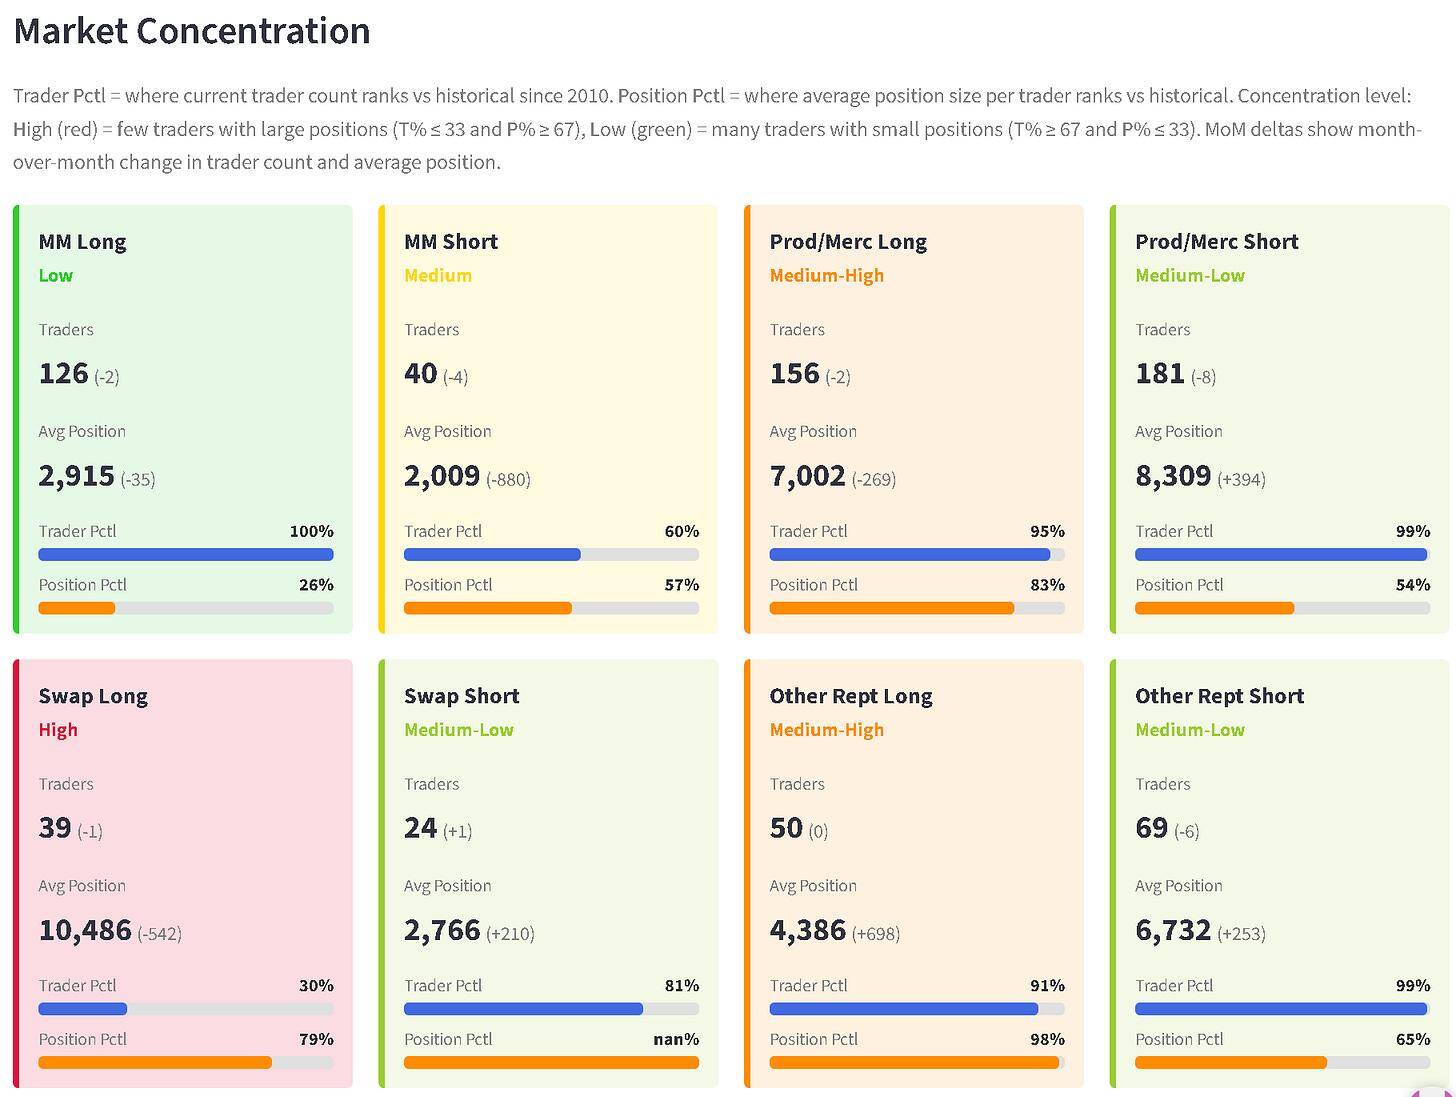
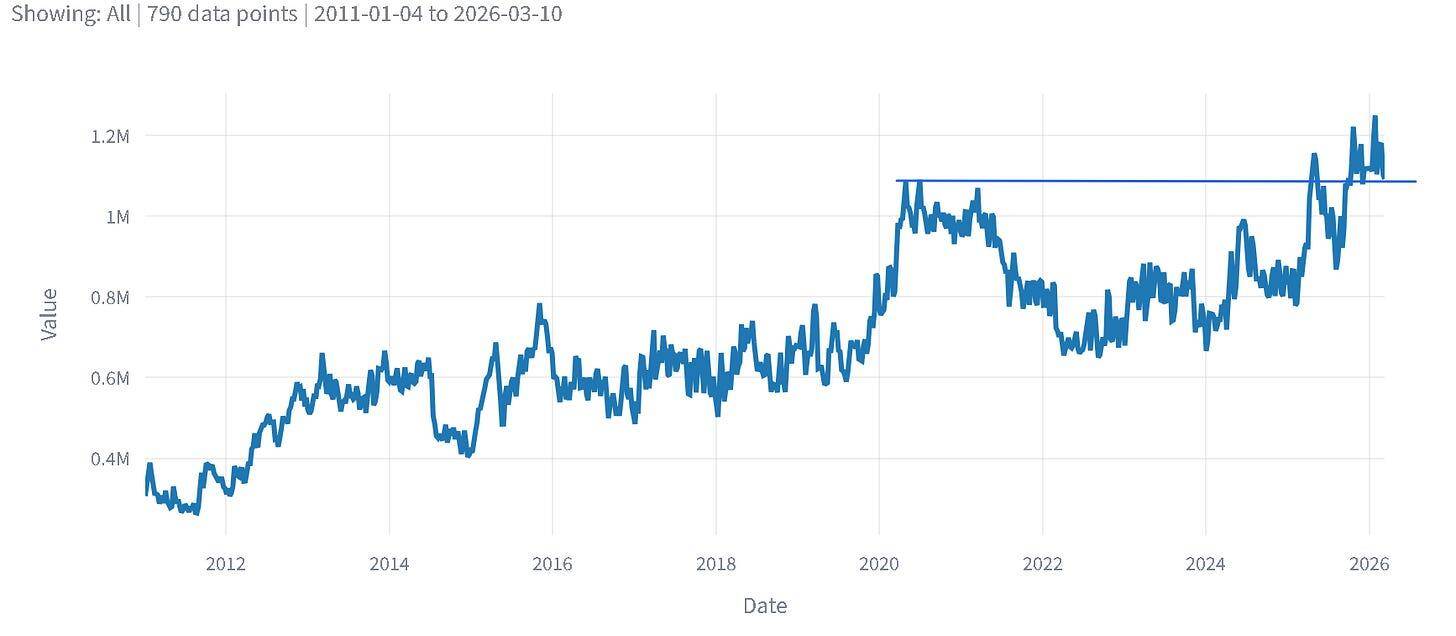
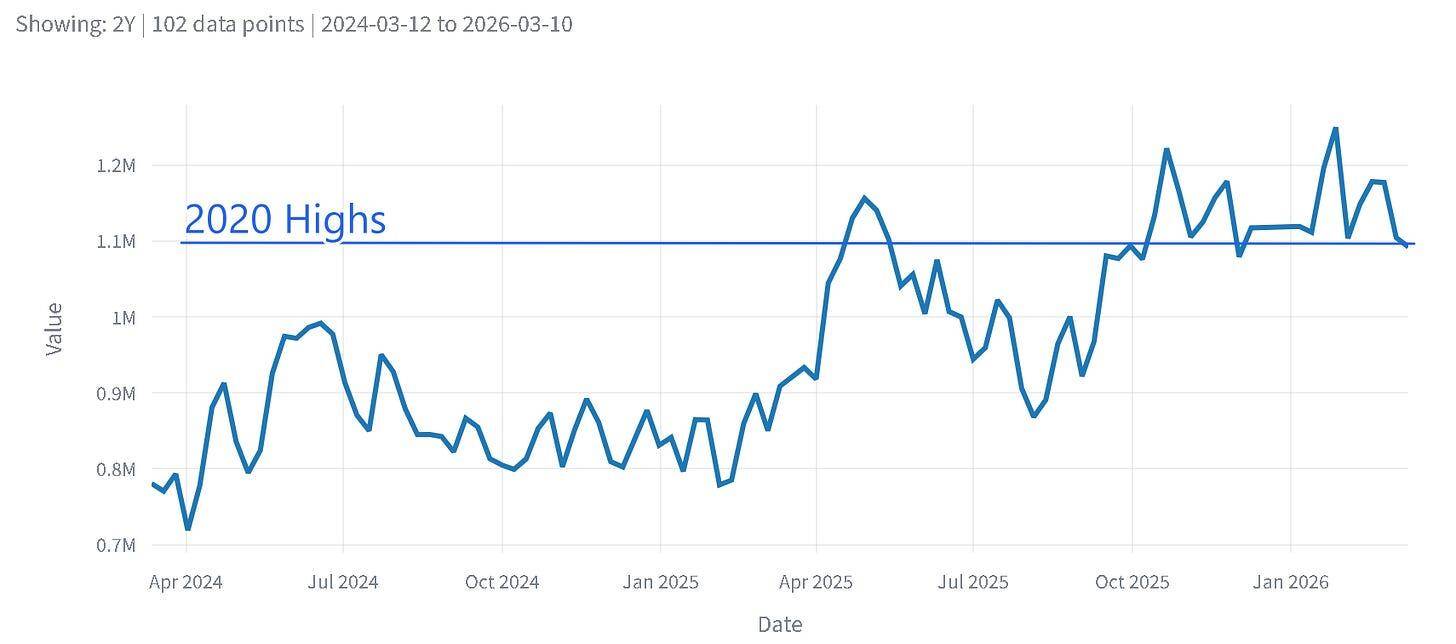
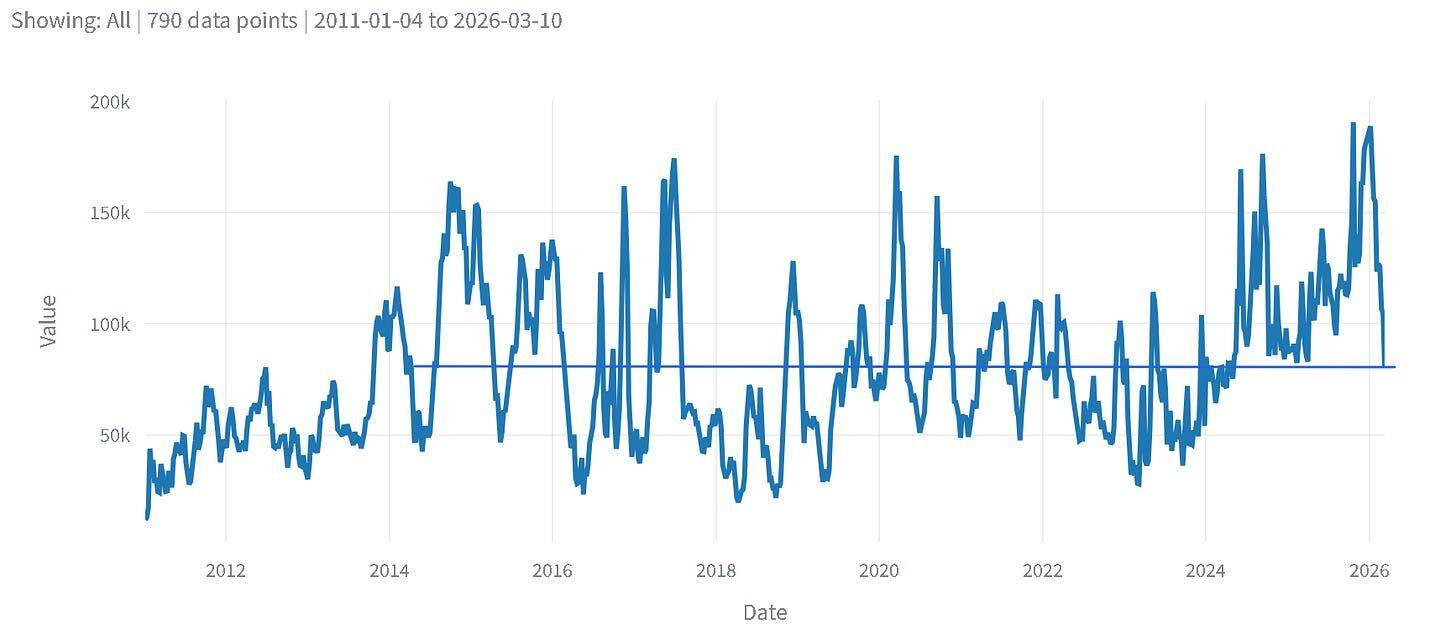
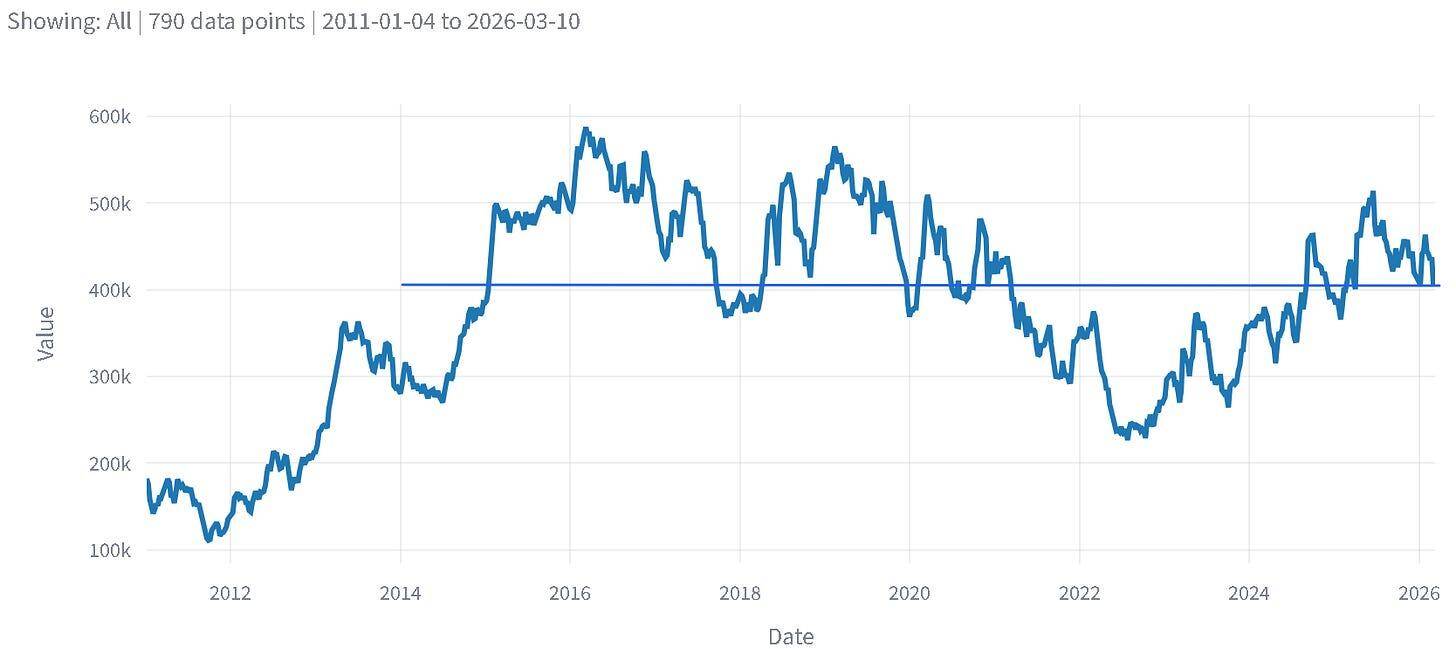
Zooming in on these longs, we can see they are not yet willing to drop their exposure below 2020 levels. This makes sense in supporting the thesis as discussed above-the duration of the potential global shocks are not yet known. It will be telling when these guys want to let go of their overall curve long exposure.
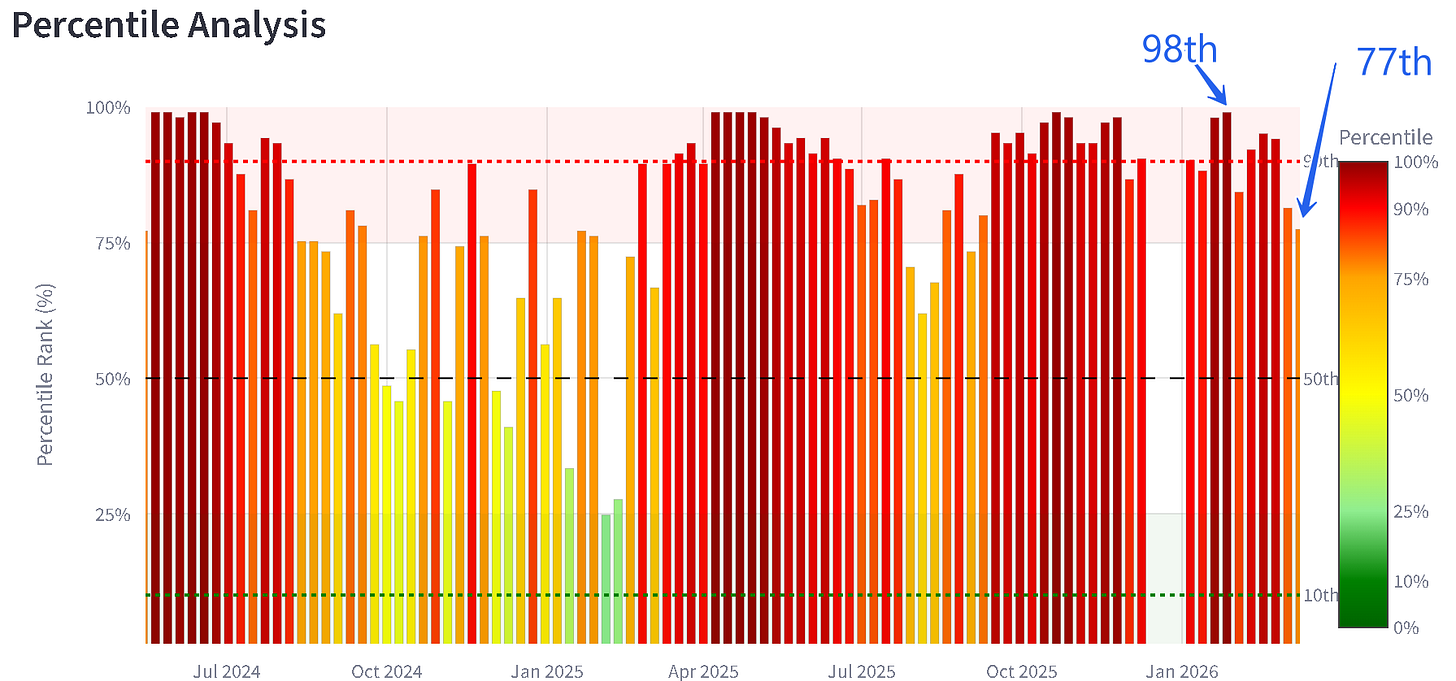
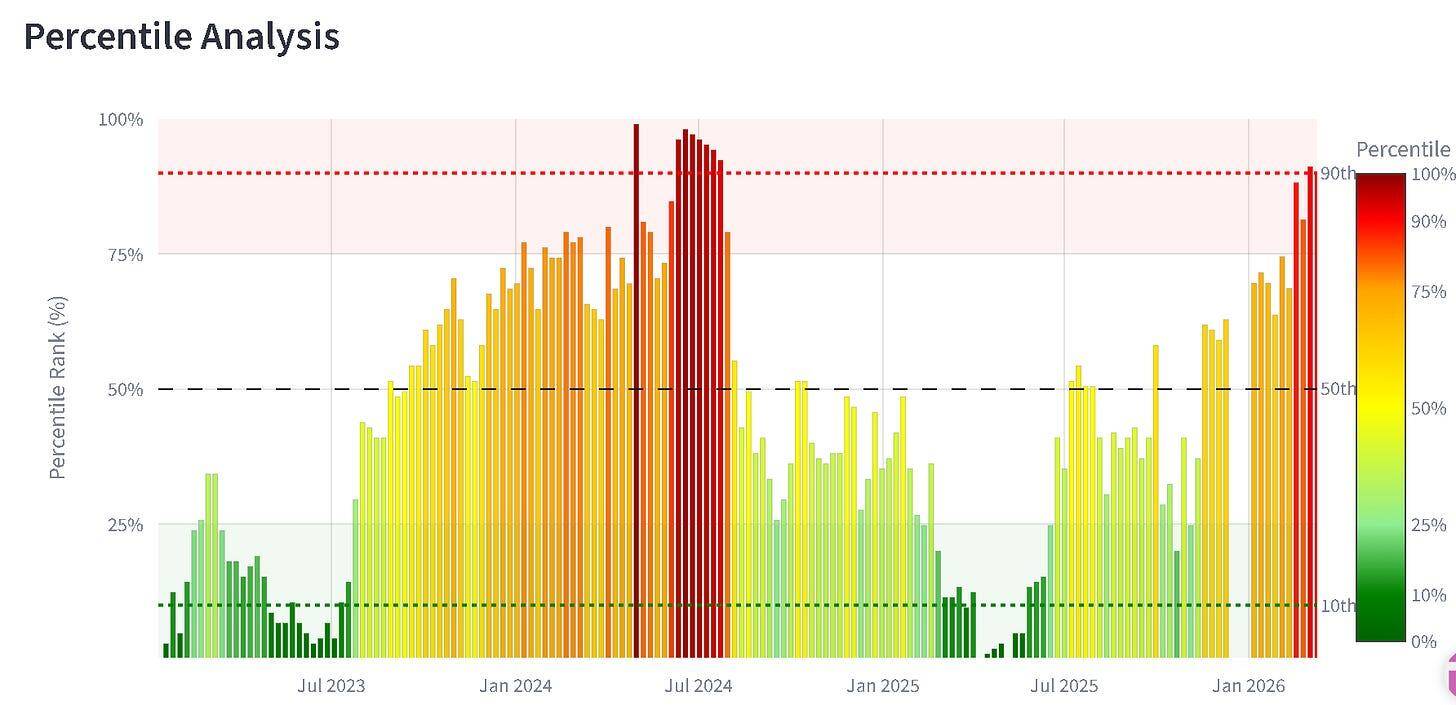
Short side: It would make sense that this cohort would increase their shorts and sell forward to hedge these gift prices. The signal here of rising probability of conflict was they were 98th percentile short as of Jan 27th. This was the day the US announced air military drills in the middle east. Since then, the hedging has retreated slightly. This signifies to me that the initial inventory risk spike has been covered.
Money Managers
Money manager longs in Brent seem gassed out at these levels.
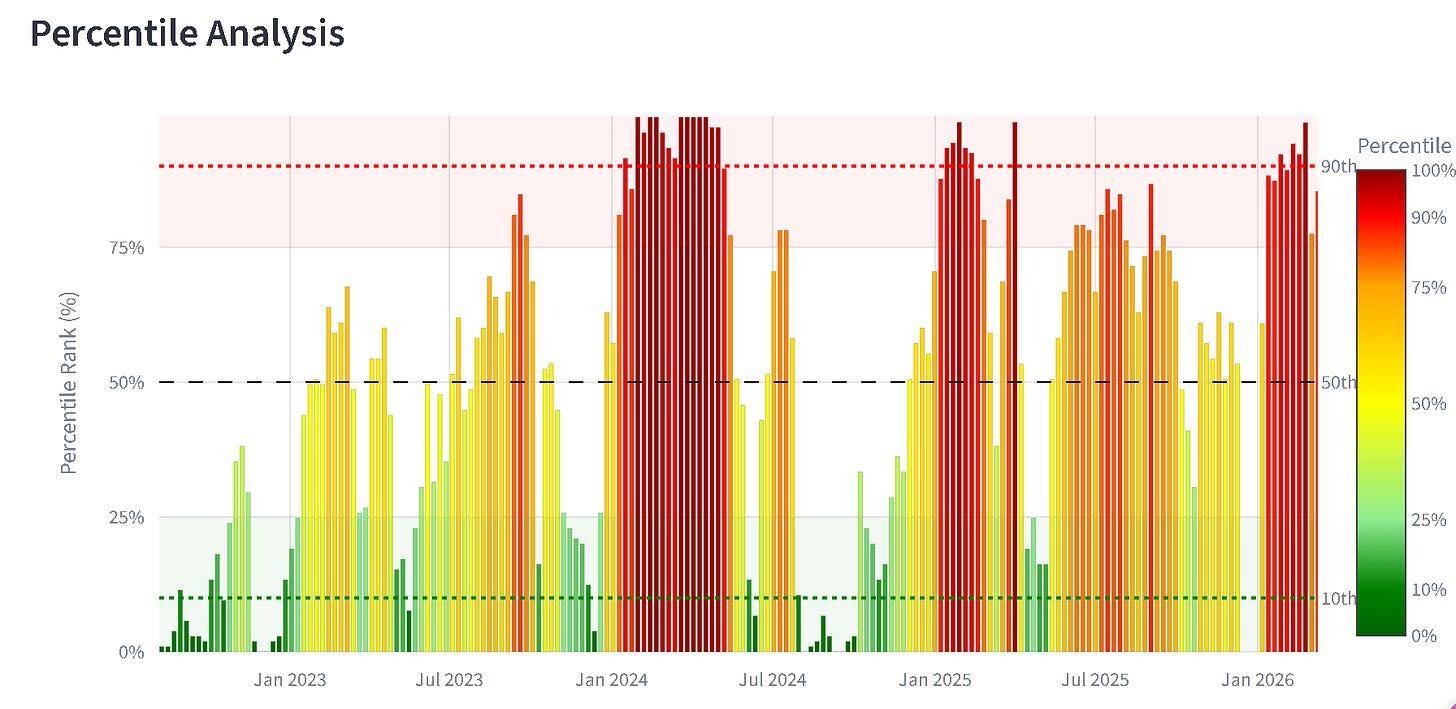
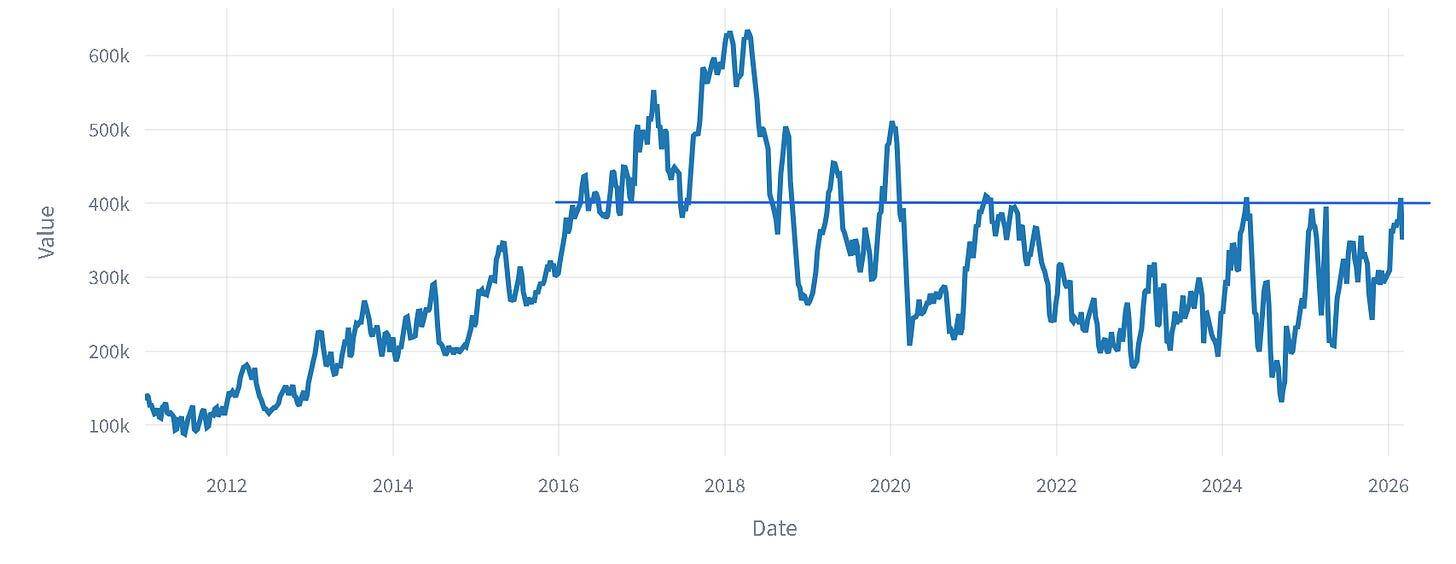
On closer inspection, it seems that they liquidated into the initial price highs, only to then reload on last week’s lows. Pretty sure the US Energy secretary has his fund in this cohort.
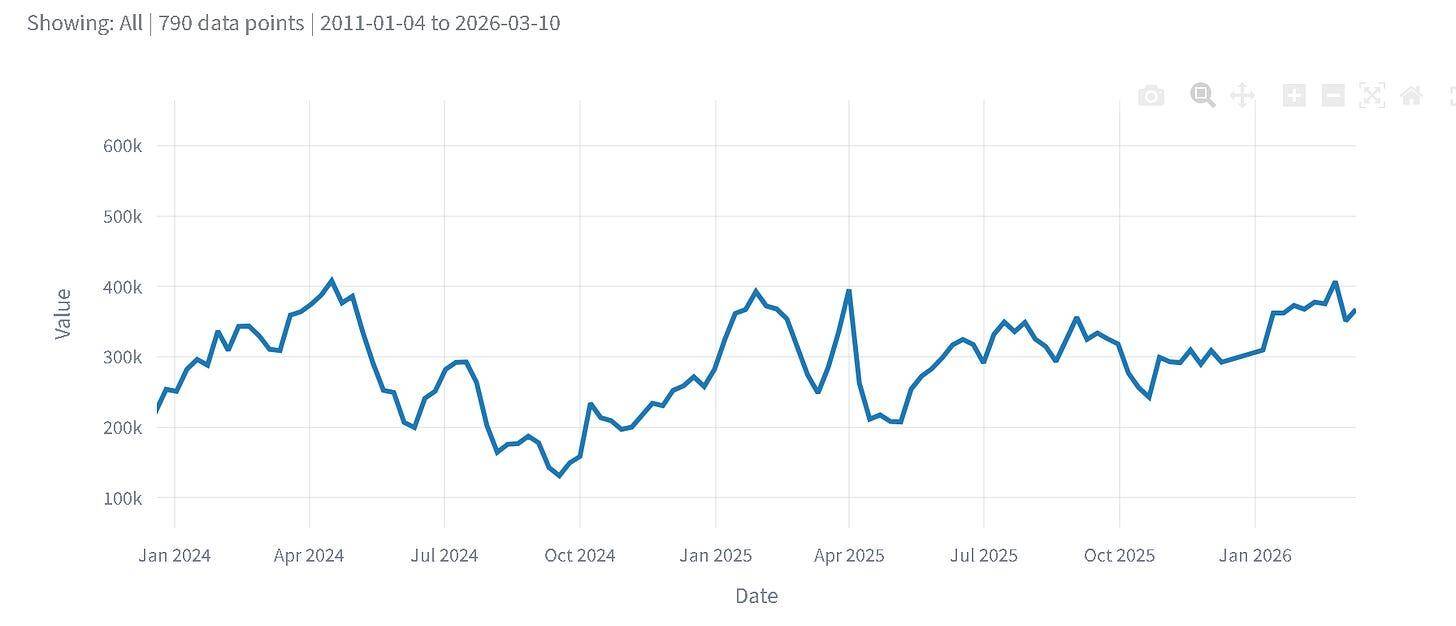
If we look at the distribution of contracts over the last 3 weeks here it tells that story.
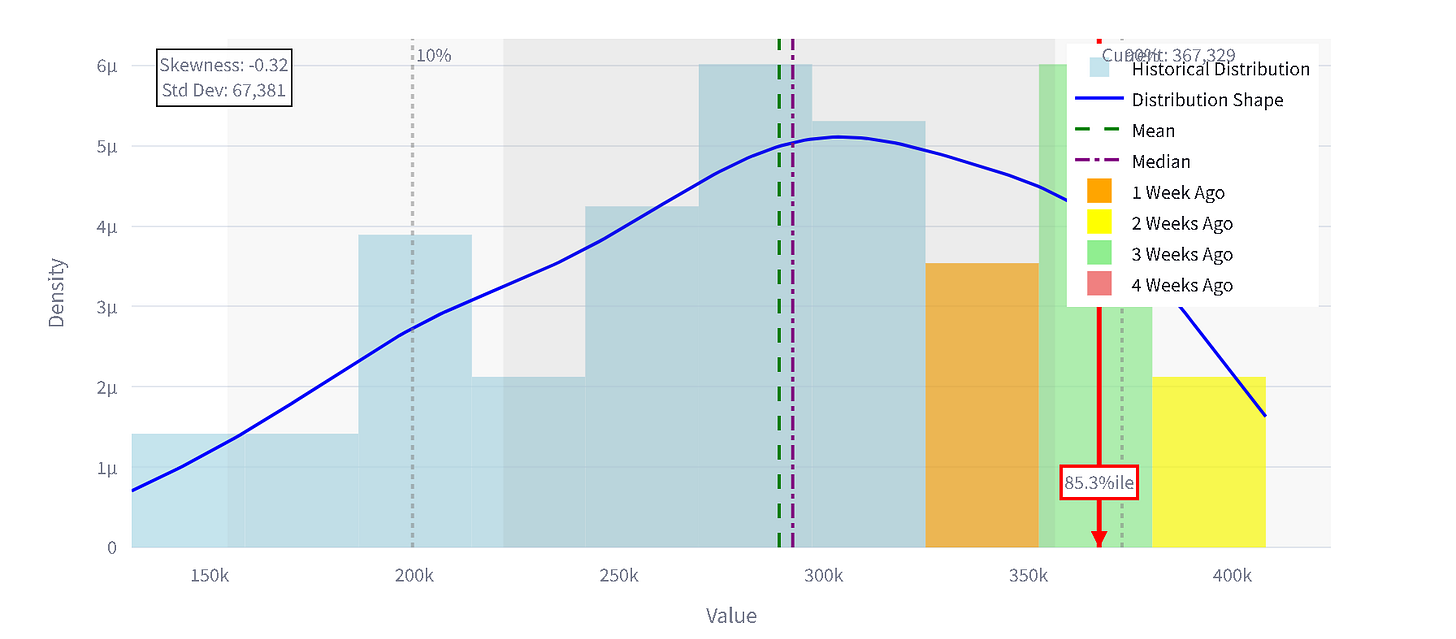
MM Shorts are back to levels last seen March 2024. We are going to have to start to look at where they may want to build again on the short side.
Swaps
If swaps long are going up- means their clients are getting more short. Vice versa. This is where the largest of participants play.
Longs
Shorts
The swap clients holding here below early 2024 levels- an oil environment where the Houthis were attacking ships transiting in the straits of Strait of Mandeb and the Gulf of Oman. This is now threading together nicely as tankers are indeed diverting to the Strait of Mandeb to collect diverted cargos where the Saudi East-West pipeline ends up. The Houthis are indeed expected to start to hit these transits as well.
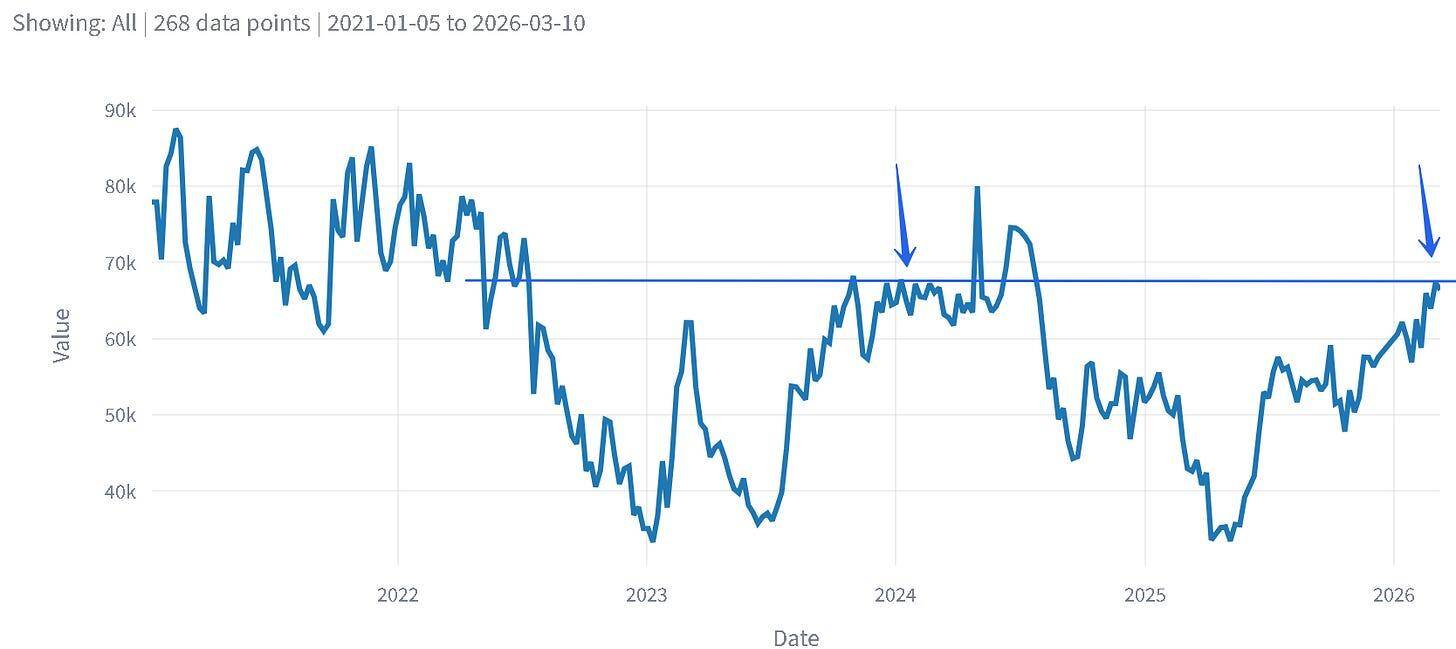
They are however at stretched levels that will be difficult to add any great amounts to. Net net-they are extremely long and maintaining that positioning.
What’s The Next Move?
I’m not going to be any use in this section this week. The volatility is wild, therefore any trade guidance I may give may price in and out within 2 hrs, with a new landscape over the course of 48hrs. This is intraday and spread trading central.
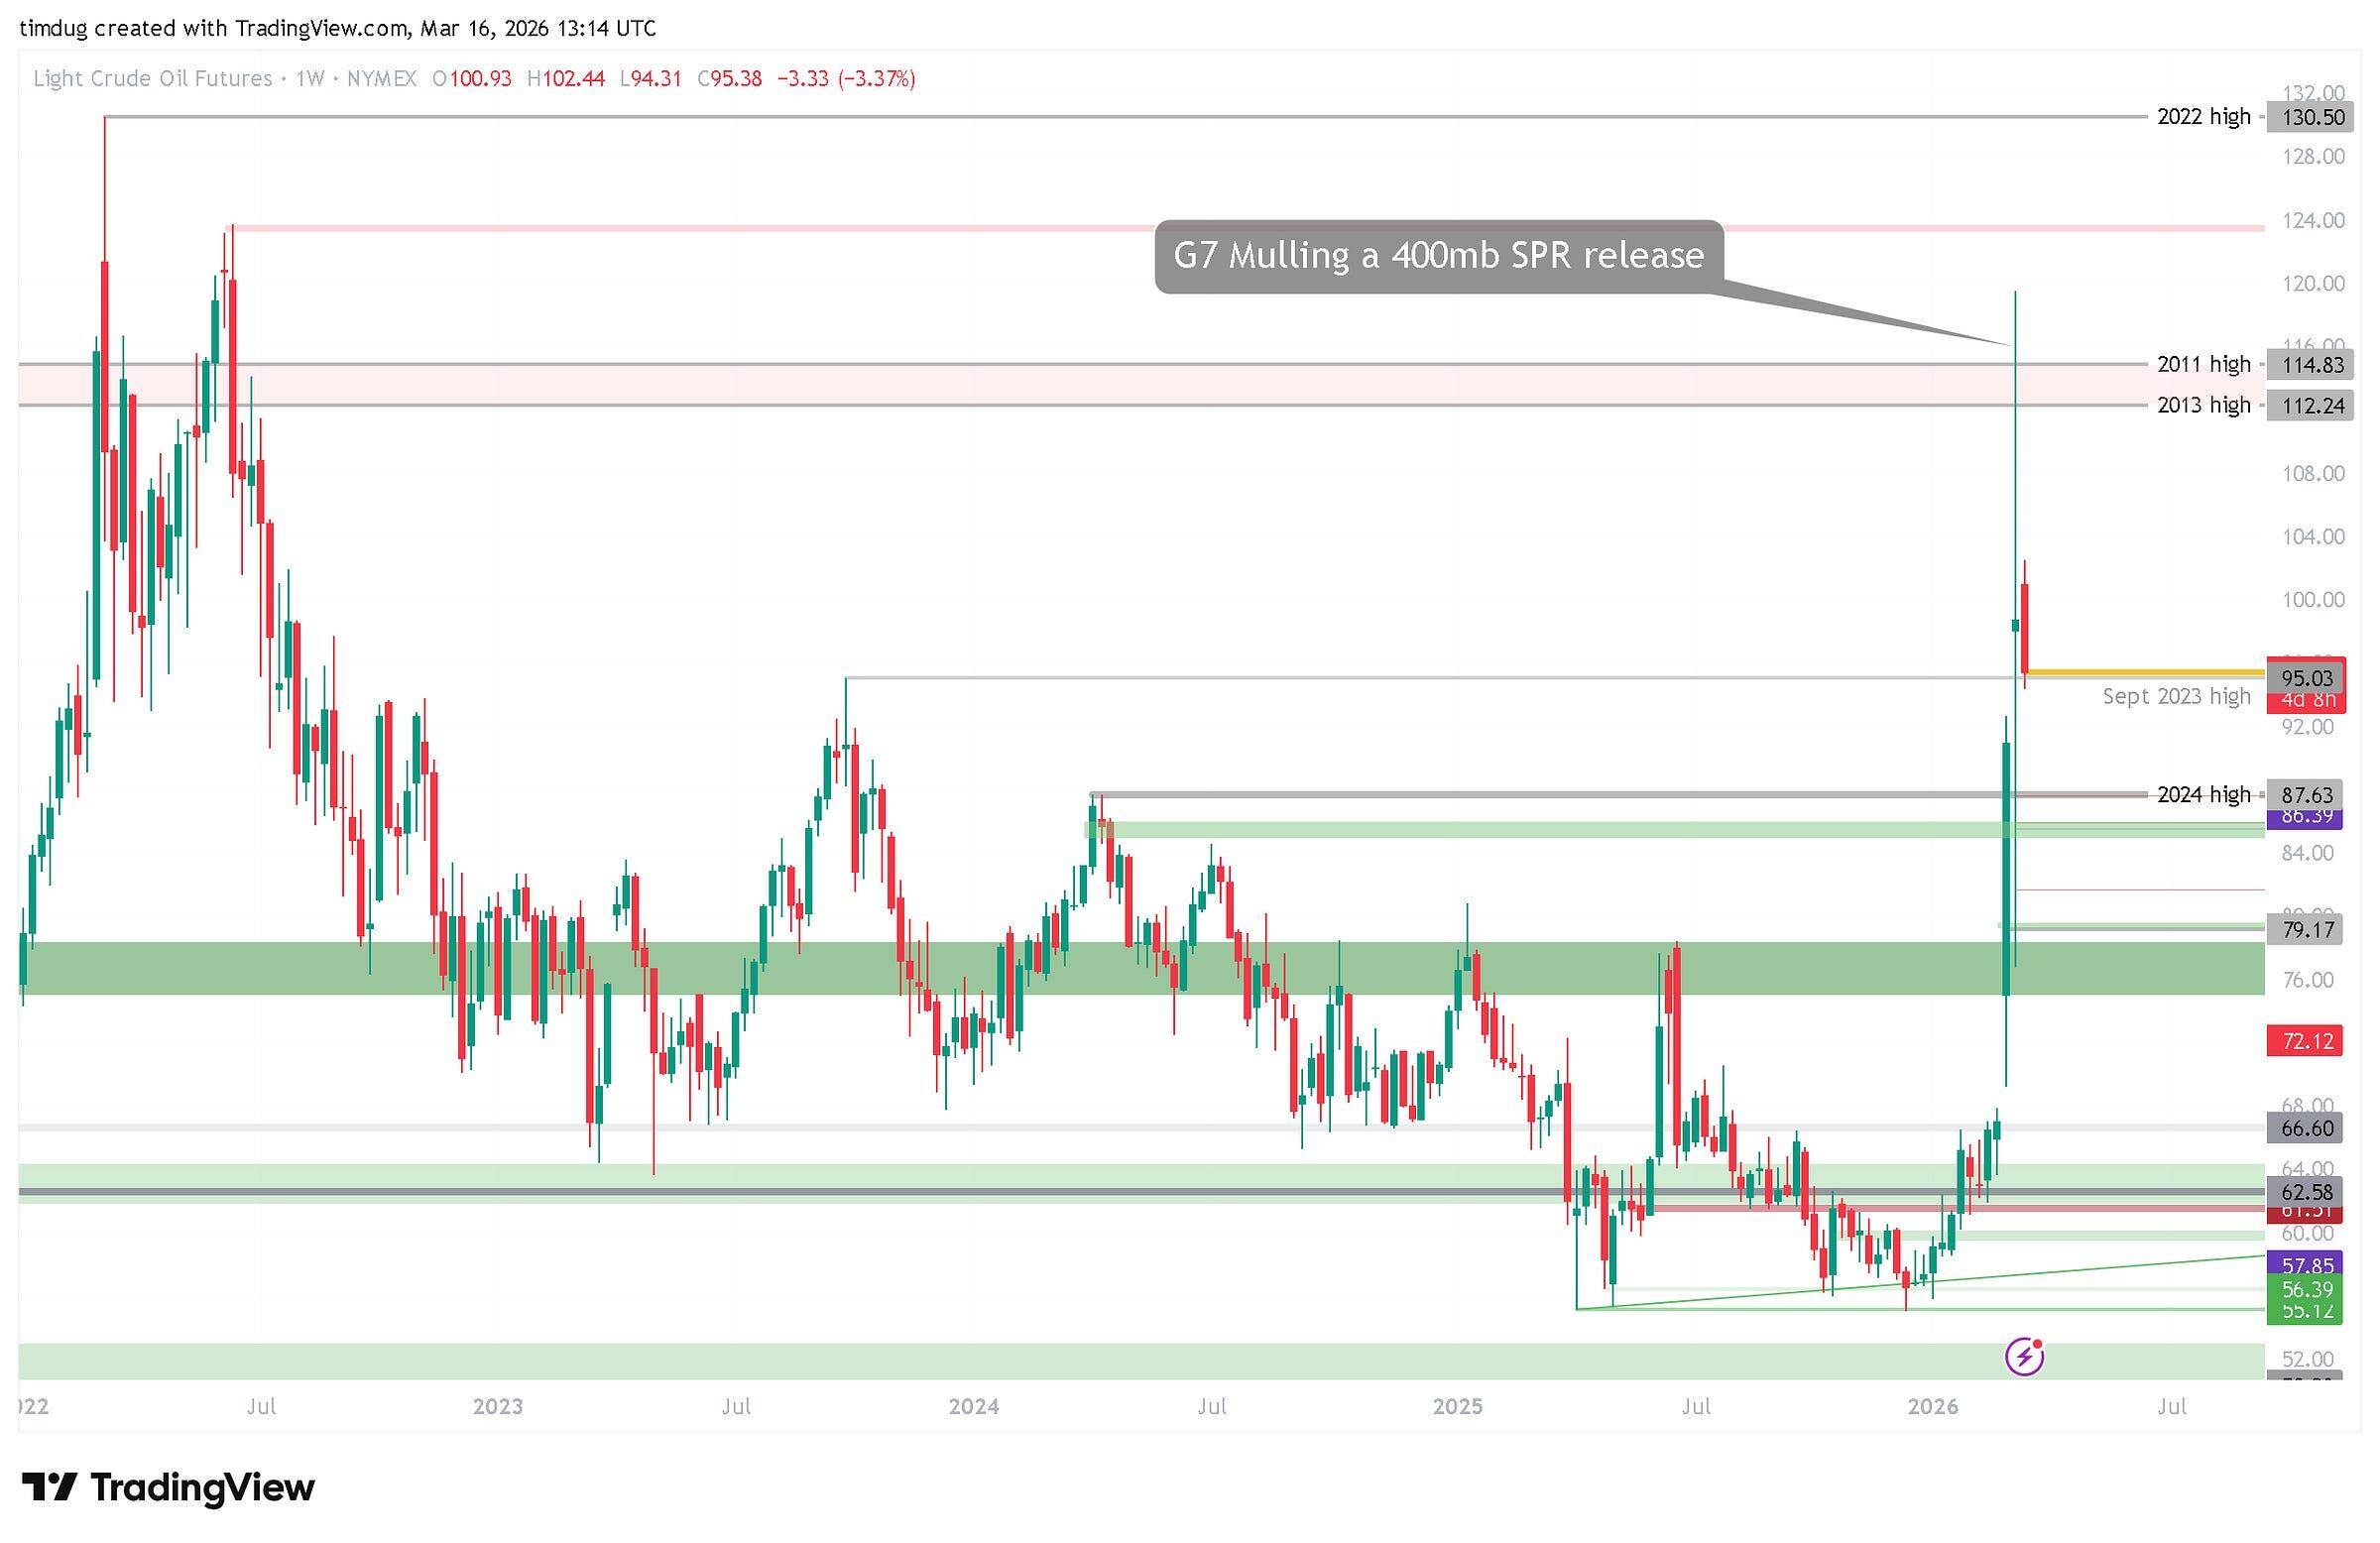
What I do see as high probability, is that the Expeditionary forces arrive and start escorting vessels. Followed by a next phase of boots on the ground in Iran. Price will be near to impossible to forecast on this, and it may take up to 2 weeks to deploy a ground invasion.