


It was a busy morning on the Eurozone economic calendar. Prelim inflation and first estimate GDP numbers drew plenty of interest.
The numbers were EUR positive. Both first-quarter GDP and inflation figures for the Eurozone delivered support.
Inflationary Pressures Pick Up in April Due to Supply Chain Woes
According to prelim figures for April, French consumer prices increased by 0.4% following a 1.4% jump in March.
For the Eurozone, the annual rate of inflation ticked up from 7.4% to 7.5. Economists forecast a rate of 7.5%.
According to Eurostat,
- Energy is expected to have the highest annual rate in April (38.0% compared with 44.4% in March), followed by food, alcohol, & tobacco (6.4% compared with 5.0% in March).
- Prices for non-energy industrial goods are to rise 3.8% compared with 3.4% in March, with services by 3.3% compared with 2.7% in March.
First Quarter GDP Numbers Deliver Mixed Results
In the first quarter, the French economy stalled, falling short of a forecasted 0.3% growth. Year-on-year, the economy expanded by 5.3%, marginally softer than 5.5% in the previous quarter.
GDP numbers from Germany impressed, with the economy growing by 4.0% year-on-year, up from 1.8% in Q4. Quarter-on-quarter, the economy expanded by 0.2%, recovering from a 0.3% contraction in the previous quarter.
For the euro area, the economy grew by 0.2%, quarter-on-quarter. Economists had forecast the economy to grow by 0.3% in the quarter. Year-on-year, the economy expanded by 5.0%, which was in line with forecasts.
According to Eurostat,
- Portugal (+2.6%) recorded the highest increase compared with the previous quarter, followed by Austria (+2.5%) and Latvia (+2.1%).
- Italy recorded the only decline, with a 0.2% contraction.
Market Impact
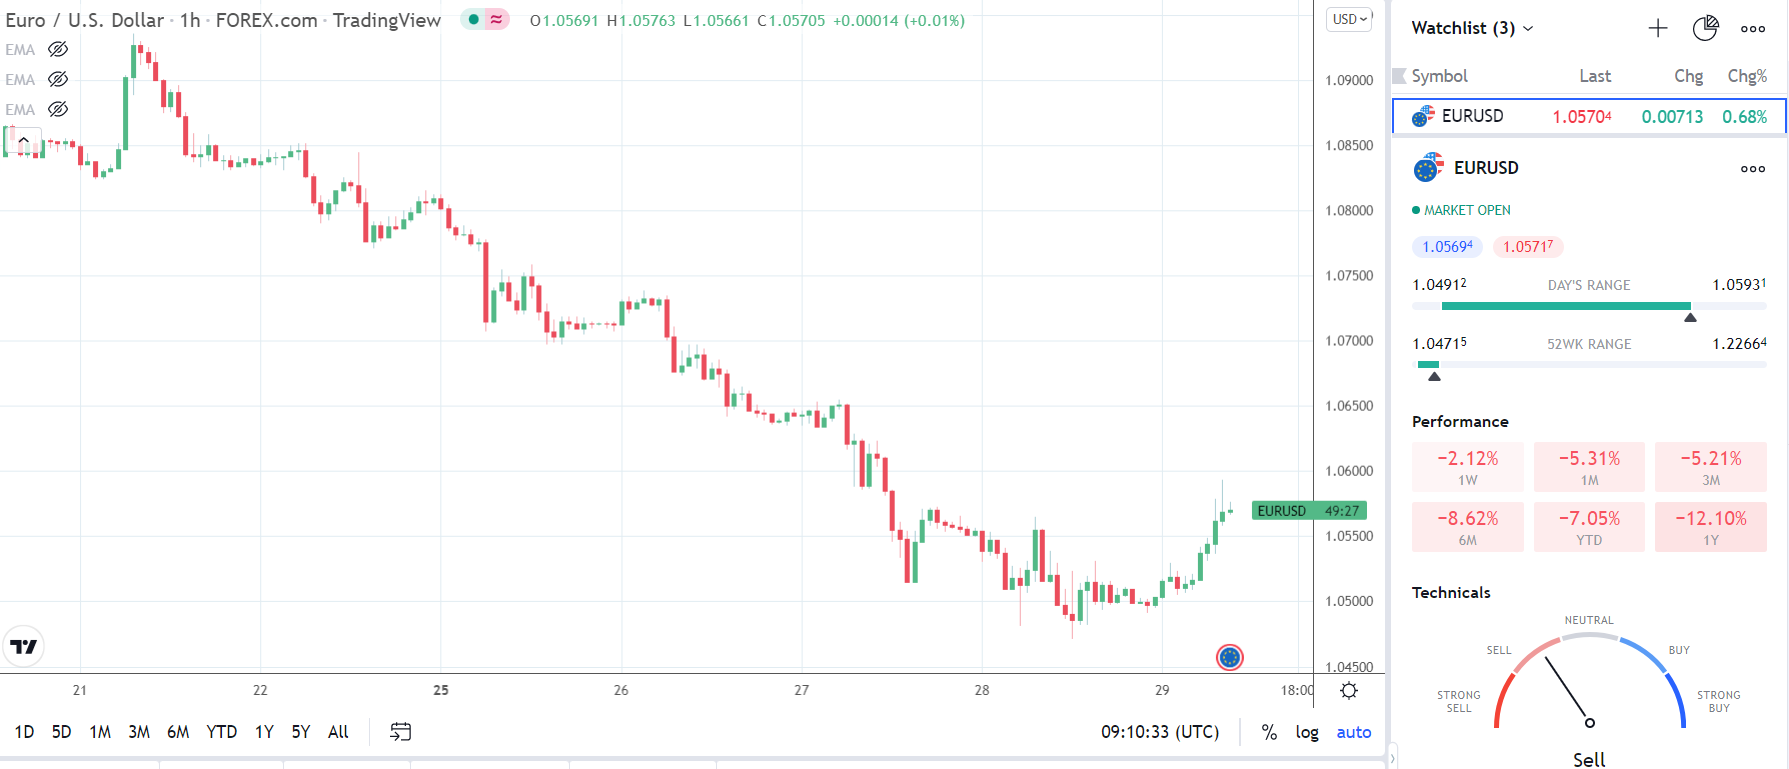
Ahead of today’s stats, the EUR fell to a pre-stat and current-day low of $1.04912 before finding support.
In response to today’s stats, the EUR rose to a current-day high of $1.05931 before easing back.
At the time of writing, the EUR was up by 0.68% to $1.05704.
Next Up
US inflation and personal spending figures are due out later today. With the Fed delivering its policy decision next Wednesday, inflation will likely be the market’s area of focus.