DAX Dips Ahead of Crucial US Data and Trade Updates
The DAX stumbled at the open as markets braced for critical US data and trade updates set to influence global risk appetite. On Thursday, May 15, the DAX opened the session 0.54% lower at 23,399.
Market focus will shift to key US economic indicators, potentially reflecting the impact of tariffs on the economy. Uncertainty surrounding Trump’s trade policies added to the cautious mood.
German wholesale prices rose 0.8% year-on-year in April, down from 1.3% in March. However, the figures had little immediate impact on the DAX.
Sector Performance
Merck tumbled 5.05% amid concerns about President Trump’s drug price cuts on earnings.
Uncertainty about US trade policy also weighed on German auto stocks. Mercedes-Benz Group and Porsche fell 0.47% and 0.57% in early trading, while Volkswagen was flat. BMW traded ex-dividend.
Eurozone Employment in Focus
Later in the morning session, Eurozone employment figures will draw interest. Economists expect employment to rise 0.8% year-on-year in Q1 2025, up from 0.7% in Q4 2024.
A tighter labor market could lift wages and consumer spending, potentially fueling inflationary pressures. Rising inflation may dampen bets on multiple ECB rate cuts, pressuring German-listed stocks. However, a softer reading could signal a more dovish ECB rate path.
DAX Price Forecast
Every new DAX analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all DAX forecastsUS Markets Mixed Amid Economic and Trade Uncertainties
Wall Street signaled waning risk appetite on Wednesday, May 14, amid fading optimism over the US-China trade truce and economic uncertainty.
The Nasdaq Composite Index and the S&P 500 rose 0.72% and 0.10%, respectively. This week’s AI-related deals in the Middle East bolstered demand for tech stocks. However, the upside was modest as investors awaited key economic indicators and trade developments.
US Retail Sales and Producer Prices in Focus
Later today, market focus will shift to US producer prices and retail sales data. Economists forecast retail sales to stagnate month-on-month in April after surging 1.5% in March. A drop in retail sales may reflect the impact of tariffs on demand, potentially reviving recession fears. Conversely, a higher reading could signal a resilient economy, improving risk sentiment.
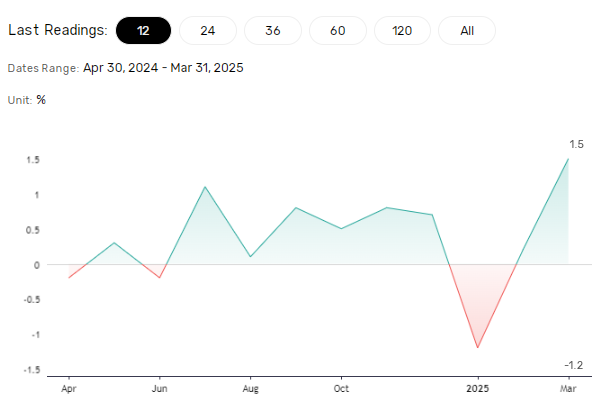
Producer prices are also under scrutiny following the CPI report. Economists expect producer prices to rise 2.5% year-on-year in April compared with 2.7% in March. A softer print might indicate easing inflation, boosting Fed rate cut hopes. Conversely, an uptick may reflect tariff effects on import prices, dimming prospects for near-term policy easing.
Fed Chair Powell is also scheduled to speak, adding another potential catalyst for volatility in equity markets.
Near-Term Outlook
The DAX’s near-term outlook depends on key economic data, trade headlines, and central bank signals.
- Bearish Scenario: Rising US-EU tensions, weak US retail sales, and a hawkish Fed Chair could send the DAX toward 23,000.
- Bullish Scenario: Optimism about a US-EU trade deal, upbeat US retail sales, and a dovish Fed Chair could fuel a rally toward the all-time high of 23,912.
DAX Technical Indicators
Daily Chart
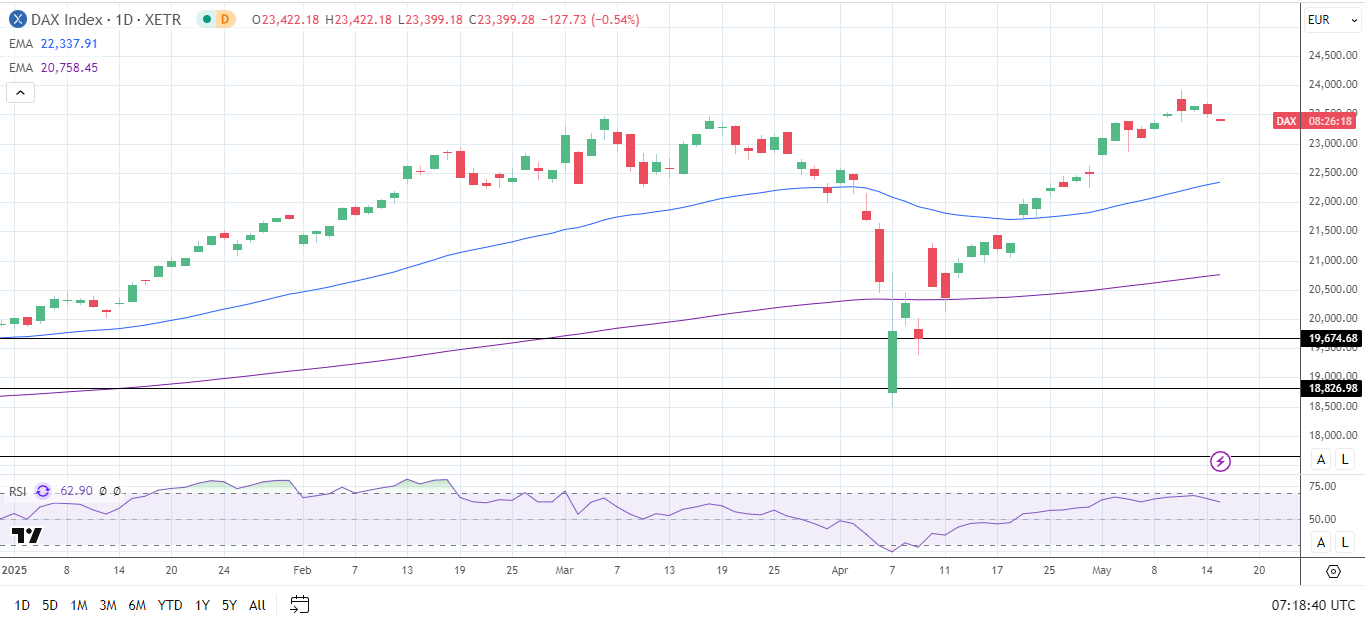
The DAX remains above the 50-day and 200-day Exponential Moving Averages (EMA), sustaining a bullish trend.
A breakout above 23,750 would open the door to retesting the May 12 high of 23,912 and the 24,000 resistance level. Holding above 24,000 could fuel a move toward 24,350.
On the downside, a drop below 23,350 brings 23,150 into view, with 23,000 the next support level.
The 14-day Relative Strength Index (RSI) at 62.90 suggests the DAX could climb to 23,912 before entering overbought territory (RSI > 70).
Final Thoughts
With global trade tensions, central bank commentary, and macroeconomic data continuing to influence sentiment, volatility will likely persist. EU trade news and domestic policy decisions in Germany, including fiscal spending plans, may further sway demand for German equities. Traders should stay alert to both technical and fundamental shifts.