Last Week in Brief
From geopolitics and elevated government borrowing costs to AI investment concerns, hawkish Fed minutes, and rising oil prices and yields, it was quite the week. President Trump eased concerns by ruling out any strikes on Iran before the Midterms via a social media post. However, as I said in a note last week, I have lost count of his threats; markets have become almost desensitised, and quite frankly, if no shots are fired and nothing is inked, traders will largely overlook his posts.
This Week’s Key Events
Without question, the key risk event on everyone’s radar this week is Wednesday’s September US CPI report. Another potentially noteworthy macro print to watch is Thursday’s September Australian employment report. We also gear up for earnings season, with bank stocks front and centre. Another talking point this week will be Fed Chairman Kevin Warsh’s public speech at the International Monetary Fund’s annual meeting in Thailand on Friday.
Markets Heading In
The USD index notched its fourth straight week in positive territory last week, clocking highs not seen since early April and nearing YTD peaks. However, upside momentum has certainly eased. That said, if the upcoming CPI print shows a marked dovish deviation, investors will likely fully price out any October tightening and weigh on the buck.
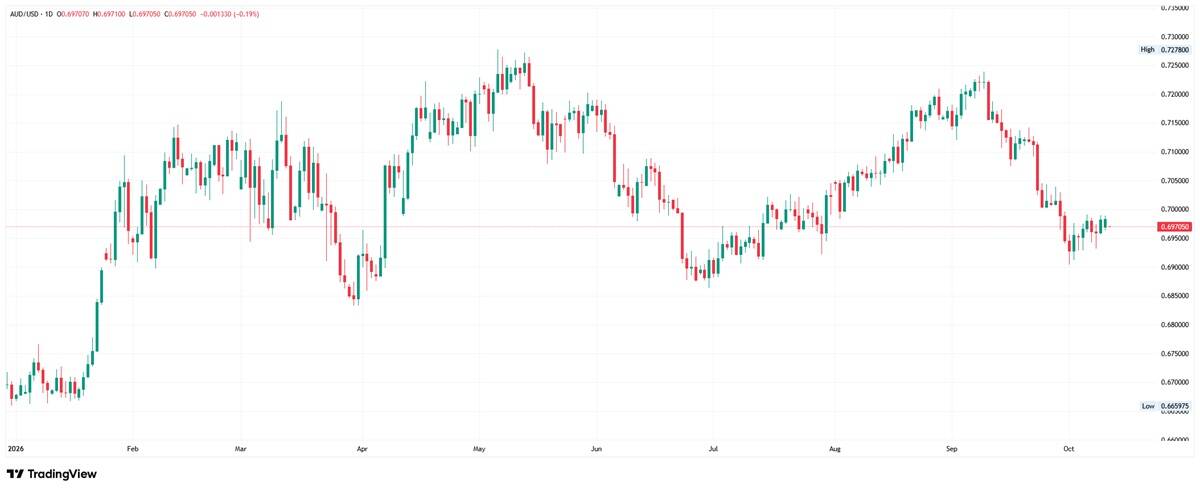
Treasury yields followed suit, but 10s and 30s fell from their highs and posted their first weekly decline in a while, albeit from multi-decade peaks. The S&P 500 and Nasdaq Composite hit fresh records, driven mainly by AI stocks. The positive sentiment lifted high-beta currencies, with AUD and NZD snapping multi-week losing streaks against the USD.
US CPI Inflation: Why a Miss Matters More
Expectations heading into the US CPI data suggest both YY headline and core will rise to 3.7% (from 3.4% in August) and 2.5% (from 2.4%), respectively. MM headline is also forecast to increase to 0.6% (from 0.4%), while core is expected to ease to 0.2% (from 0.3%).
AUD/USD Price Forecast
Every new AUD/USD analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all AUD/USD forecastsThe recent US payrolls printed a clear miss: 29,000 against c.90,000 expected, down from August’s initial reading of 162,000. Revisions then took 31,000 off July (now -10,000) and 29,000 off August (now 133,000), leaving the two months a combined 60,000 below previous estimates. Unemployment ticked up to 4.2% from 4.1%, though unrounded, the rate rose only from 4.14% to 4.18%, with wage growth coming in cooler. The August US PCE numbers were also recently released and came in below expectations across the board. Although the BEA changed its methodology, price pressures remain above the Fed’s 2% target.
Ultimately, for this week’s US CPI, I would expect a miss – with focus on core measures – to deliver more volatility than a beat. A miss would likely unwind October tightening bets (and perhaps take a hike off the table in December), unwind USD bullish positioning, and follow on from recent soft jobs and PCE data. A hot print largely confirms current pricing and, at most, adds a little premium for a fourth hike.
Australian Employment
The only other economic data I will be watching closely this week is the Aussie employment report. Consensus suggests that the Australian economy added 20,000 new jobs, down from 39,500 in August, with unemployment expected to remain steady at 4.6%.
Following RBA Governor Michele Bullock’s comments, markets have reduced the probability of a year-end rate hike to a coin toss, and next-year expectations to just one rate hike from two. Bullock noted that the Board considered both a hike and a hold at its recent meeting and said she hoped further policy tightening would not be needed. With this, I feel a broad miss – employment down and unemployment up – would likely offer the most bang for your buck, as this could prompt investors to price out November tightening (c.7 bps) and trigger AUD downside.
Earnings: Banks Kick Off Q3
Q3 earnings season starts with Citi, Goldman Sachs, JPMorgan, Wells Fargo, Bank of America, BlackRock, and Morgan Stanley. Their commentary on credit quality, loan demand, and deposit costs will offer useful insight into consumers and businesses.
The risk is that expectations are high after a strong Q2, so even solid results or cautious guidance could disappoint. Equities are near record highs despite elevated oil, sticky inflation concerns, and multi-decade-high yields, so earnings are carrying much of the weight.
Written by FP Markets Chief Market Analyst, Aaron Hill