The French group recorded only modest organic revenue growth in the third quarter of 2026, while sales at its flagship Fashion & Leather Goods division declined more sharply than expected. Weak Chinese consumer sentiment remains a major headwind, compounded by new tax pressures on wealthy shoppers and mounting affordability concerns among luxury customers in Western markets.
The deterioration raises a question for investors: is LVMH facing a temporary demand slowdown, or are changing spending habits and years of price increases exposing deeper weaknesses in its business model?
LVMH’s Q3 Results Highlight Persistent Weakness
LVMH reported €18.5 billion in third-quarter revenue on October 12, 2026, representing organic growth of 1%. The result missed analysts’ expectations of 1.3%, according to Reuters. For the first nine months, revenue reached €57.1 billion, with organic growth of 2%, although reported revenue declined 2% year on year.
Currency movements reduced nine-month reported revenue by 3%, while changes in consolidation scope had a negative 1% impact. These effects help explain the difference between underlying sales performance and reported figures, but they do not change the central concern: organic growth remains limited.
The most significant weakness is in Fashion & Leather Goods, which includes Louis Vuitton and Dior. The division generated €26.4 billion in revenue during the first nine months, accounting for approximately 46% of group sales. Organic revenue fell 5% in Q3, following a 1% decline in the first half. The contraction was substantially worse than the 1.8% decline analysts had anticipated.
Other divisions provided some support, as Watches & Jewelry recorded 8% organic growth over the first nine months, while Selective Retailing, including Sephora, advanced 6%. Wines & Spirits grew 5%, and Perfumes & Cosmetics remained stable.
However, the quarterly picture was mixed. Watches & Jewelry growth slowed to 6% in Q3 from 9% in the first half, while Selective Retailing accelerated to 8%. The group’s diversified portfolio is helping cushion the downturn, but weakness in its largest division remains a significant obstacle.
China Faces New Pressures as Luxury Spending Weakens
China is becoming an increasingly important test of LVMH’s ability to sustain demand without resorting to aggressive discounting. The group attributed the weaker Asian performance in Q3 to a sharp deterioration in Chinese consumer sentiment, driven by macroeconomic conditions and reduced discretionary spending. Sales in Asia declined 5%, compared with 5% growth in the United States.
LVMH’s chief financial officer, Cécile Cabanis, also pointed to a deterioration in the confidence of Chinese consumers following the government’s intensified tax enforcement. New tax guidelines compel wealthy taxpayers with offshore trusts to declare undisclosed assets and settle all unpaid liabilities prior to the October 22 deadline. The measure could leave some affluent consumers with less disposable income available for luxury purchases, according to Reuters.
This matters because Chinese consumers account for approximately one-fifth of global luxury purchases and have historically been a major source of industry growth. Their spending has weakened substantially since the pandemic, however, amid China’s prolonged property-market downturn and broader economic uncertainty.
The latest tax measures add another potential headwind. According to Alexis Bonhomme, head of Shanghai-based luxury consultancy Trinity Asia, the 20% levy on affected wealthy individuals is putting pressure on spending by ultra-high-net-worth consumers, a group that had previously shown greater resilience than more price-sensitive buyers.
The implications extend beyond a temporary decline in shopping activity. If even the wealthiest customers become more cautious, luxury brands may find it harder to rely on high-end spending to offset weakness among aspirational consumers. Bernstein analysts have also highlighted a sharp deceleration in growth at mainland Chinese shopping malls over the summer, suggesting that softer demand is not confined to a single customer segment.
LVMH must therefore contend with both cyclical and potentially structural challenges. Property-market weakness and tax liabilities can weigh on spending in the short term, while changing consumer priorities and reduced enthusiasm for expensive products could take longer to reverse.
Pricing Power and Consumer Affordability Under Pressure
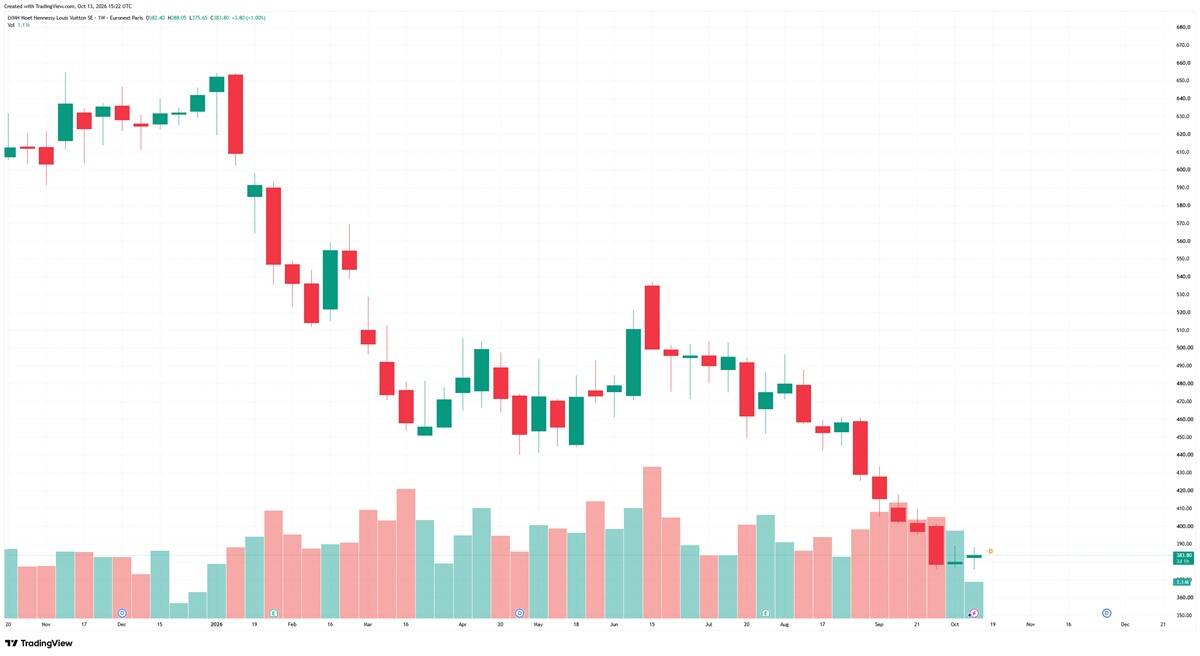
The Chinese slowdown is unfolding alongside a broader deterioration in the luxury industry’s growth prospects. European luxury shares have lost more than 20% on average so far in 2026, according to recent market reporting, reflecting investor concerns about stagnant sales and limited visibility on a sustained improvement in demand. LVMH has been among the weakest performers, with its shares down roughly 40% year to date around the October 12 results.
The pressure is not limited to China. In Western markets, inflation and higher living costs have squeezed the disposable income of middle-income consumers, many of whom are important buyers of brands such as Louis Vuitton. Meanwhile, geopolitical uncertainty, including the Iran conflict, has added to concerns about consumer confidence and spending.
As a result, LVMH faces a difficult balance between protecting exclusivity and maintaining sales volumes. Years of price increases helped luxury brands improve revenue during the post-pandemic boom, but they may also have made some products less accessible to aspirational buyers. When consumers become more cautious, the perceived value of a handbag or other high-end purchase becomes increasingly important.
LVMH has indicated that it does not favour drastic price cuts at Louis Vuitton. This approach is consistent with preserving brand positioning, but it leaves greater responsibility on product innovation, design and customer experience to stimulate demand. If customers no longer consider higher prices justified by the products on offer, maintaining premium pricing alone may not be sufficient to support growth.
The pressure on LVMH is also visible in its position on the French stock market. The company’s share-price decline has eroded its market capitalisation, and it has lost its position as the CAC 40’s largest listed company by market value to L’Oréal. This shift illustrates how sharply investor sentiment towards the luxury group has deteriorated, although market-capitalisation rankings can change with share prices.
What Does This Mean for LVMH Shares?
LVMH still benefits from a broad portfolio of globally recognised brands, geographic diversification and businesses that are performing better than its flagship fashion division. Growth at Sephora and in Watches & Jewelry offers some support, while positive US, European and Japanese trends may help offset weaker Chinese demand.
Nevertheless, investors should not assume that these strengths will quickly compensate for continued weakness at Louis Vuitton and Dior. The latest figures show that LVMH’s diversification can soften the impact of a downturn, but it cannot eliminate the consequences when its largest division contracts.
The lower share price may attract investors looking for value, but a decline in valuation does not necessarily mean that the stock has reached its lowest level and will rebound. If revenue remains weak and margins come under pressure, earnings expectations could fall further.
In our previous analysis of LVMH shares, published in October 2025, we examined whether the company was approaching an investment opportunity after signs of stabilisation. The latest results offer a reason to reassess that thesis: the improvement needed to support a sustained bullish outlook has yet to materialise.
Investors should watch for stabilisation in Fashion & Leather Goods, clearer evidence of improving Chinese consumer confidence and sustained growth across the group’s other divisions. Until those signals emerge, LVMH’s brand strength and lower valuation must be weighed against the risk that weaker demand and constrained consumer spending will continue to weigh on earnings.
Sources: LVMH Earnings, Reuters, The Wall Street Journal, Bloomberg, Yahoo Finance