


Copper’s Tariff Premium Defies the Missed June Deadline
This outlet’s own June 29 call looked for compression toward $5.50 if Washington failed to confirm a refined copper tariff by June 30. Washington failed. Copper went up instead. The reason nobody prints sits in the COMEX – LME spread. US buyers and warehouses are still paying for a tariff that was deferred and never cancelled, and that payment is the trade.
Copper Rises Despite a Divided Fed
Copper set a record at $6.72/lb on May 13, 2026. Then $6.13 by June 23, and $6.376 on July 29, up 3.3% on the month and 43.6% on the year. I treat the Fed and tariff clocks as unrelated here. Chair Kevin Warsh’s second meeting held at 3.5% – 3.75%, but the vote split 9 – 3, and the FOMC statement has Hammack, Kashkari and Logan all wanting a quarter point more. Copper closed higher anyway. A tape the dollar drives doesn’t do that. The mechanism below is copper’s alone.
US Refined Copper Tariff Decision Remains Live
The tariff itself is finished. The decision that matters is not. President Trump’s July 2025 proclamation put copper under Section 232 at a flat 50%. An April 2026 update split that into 50% on semi finished goods and 25% on derivatives. Refined cathode escaped both. What Commerce recommended instead was bigger i.e. a phased universal duty of 15% from January 1, 2027 and 30% from January 1, 2028, with a market review due by June 30, 2026. The Congressional Research Service quotes the operative words, and the review comes “after which the President may then determine whether to impose” that duty. The verb is may. Nothing in it binds him. I read the silence as the signal i.e. three fact sheets, three months, no mention of the one decision that matters. June 30 came and went. Neither the White House’s April nor its June 2026 fact sheet records a decision, and none has been announced since. The recommendation is still live.
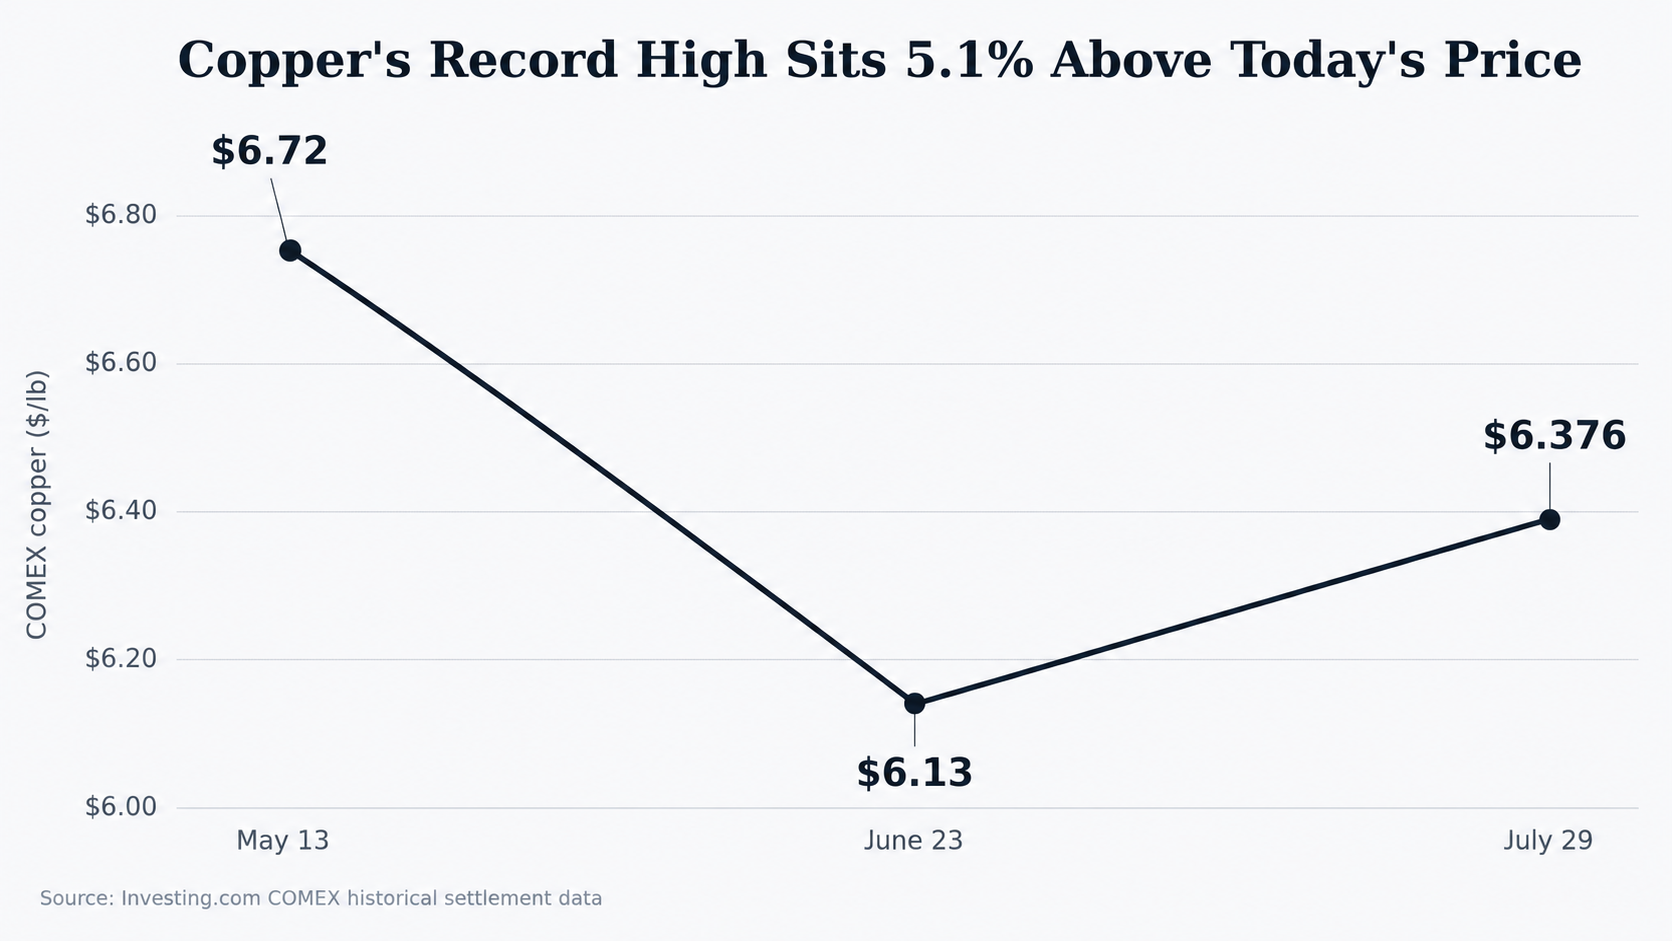
COMEX copper fell from a May 13 record of $6.72/lb to $6.13 on June 23 before recovering to $6.376 on July 29. Source: COMEX historical settlement data.
Copper Price Forecast
Every new Copper analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Copper forecastsCopper Price Analysis: Positioning and the COMEX-LME Premium
Positioning: Managed Money Keeps Adding Length
CFTC’s July 21, 2026 report puts speculative longs at 108,034 contracts against 34,057 short, so a net long of 73,977. The prior week ran roughly 64,385. Longs added 8,798, shorts shed 794, hence a build of 9,592 contracts. That build landed in the same stretch the tariff decision did not. Momentum could explain some of it. I think the timing argues otherwise i.e. money went long in the exact week the decision was due. The crowding cuts the other way too, since this net long sits near its 2026 highs and unwinds from there are fast.
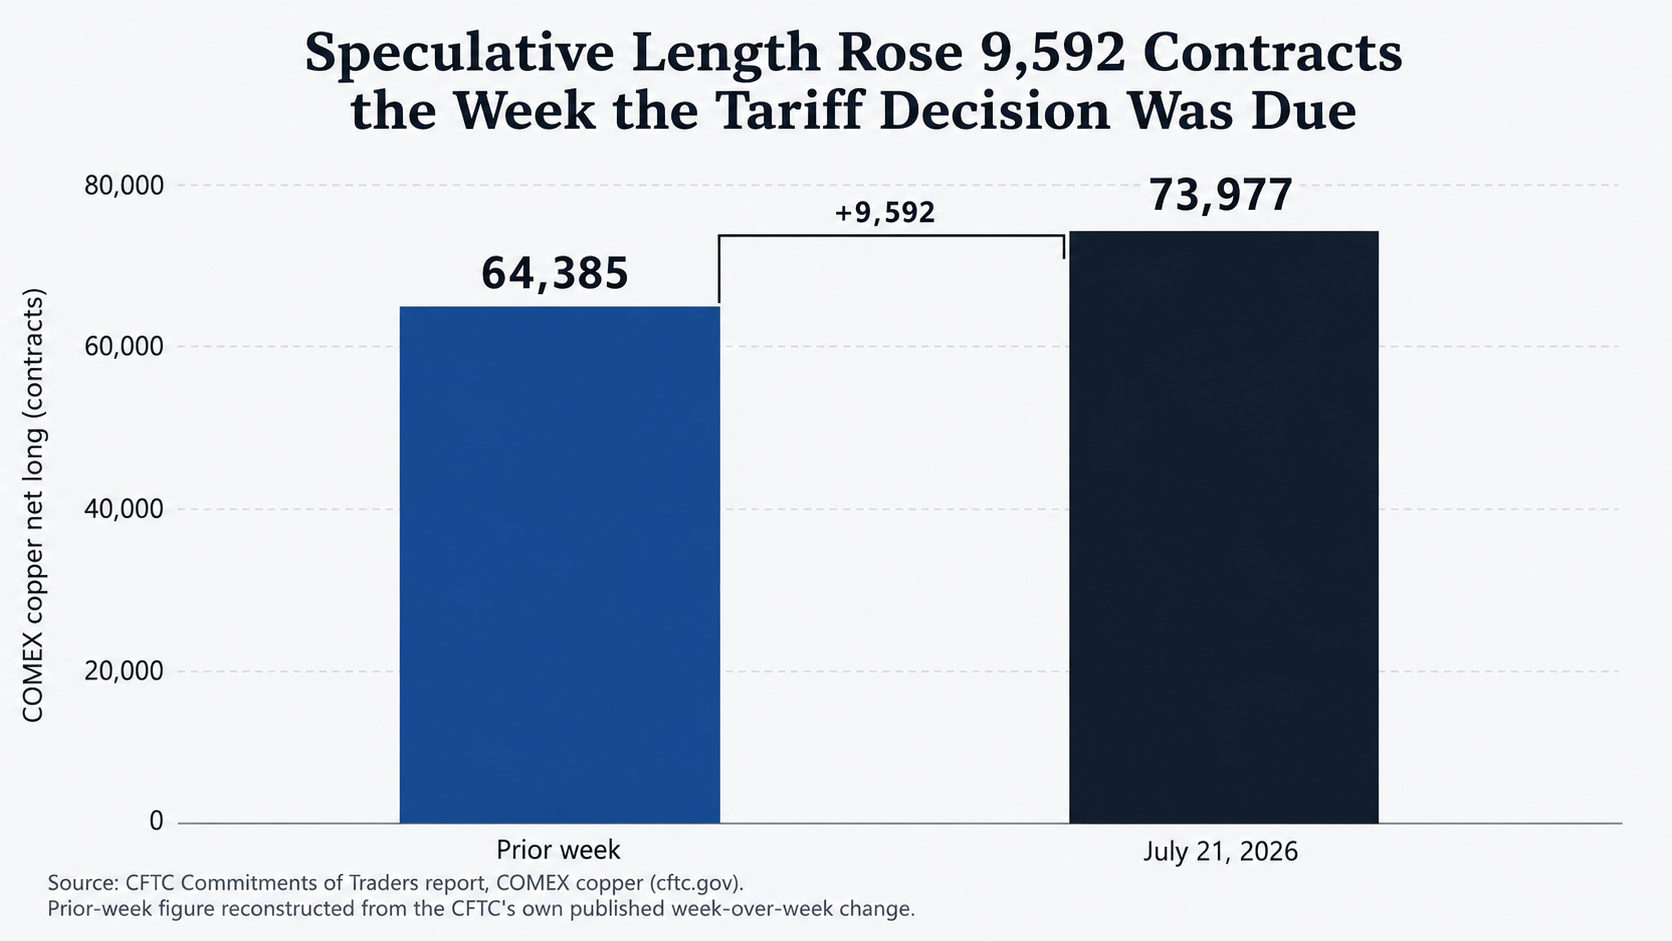
Managed-money net length in COMEX copper rose by 9,592 contracts to 73,977 in the week ended July 21, 2026. Source: CFTC Commitments of Traders report; prior-week figure reconstructed from the CFTC’s published weekly change.
The Structural Premium: Inventory Is the Tell
The premium is computable, so I ran it. COMEX settled at $6.3760/lb on July 29, 2026, and Westmetall’s read of LME’s own settlement puts LME cash the same day at $13,633.00/tonne, which is $6.184/lb. The gap is 19.2 cents per pound. Argus Media has the 2005 – 2025 average at 2.3 cents and the 2025 peak clearing $1.30/lb, so my $6.65 – $6.80 target needs 42 to 57 cents over Goldman’s $6.23/lb LME base, well inside that precedent. Fed day made the point for me. COMEX closed up, LME cash down, and the spread widened 2.1 cents in one session. Registered COMEX stock hit 457.6K short tons on July 28, 2026, up 2.6% in thirty days, and the build dates to mid 2025, when the Section 232 threat first landed. I read those as the same event. Here’s my mechanical read i.e. importers don’t warehouse US metal ahead of a duty that might be rejected, unless they expect it. The premium is what that expectation costs, and it widens the longer the recommendation sits.
China doesn’t explain this premium. Neither do this year’s disruptions at Grasberg and Kamoa Kakula, which move LME and COMEX together. China’s manufacturing PMI rose to 50.3 in June 2026 from 50.0 in May, a third straight month of expansion tied to AI linked exports, per the National Bureau of Statistics. Real, and beside the point here. What the COMEX – LME gap measures is whatever survives once I net that shared demand out of both venues, which is exactly where a US specific tariff expectation would sit. It has held near eight times its historical norm through the same window.
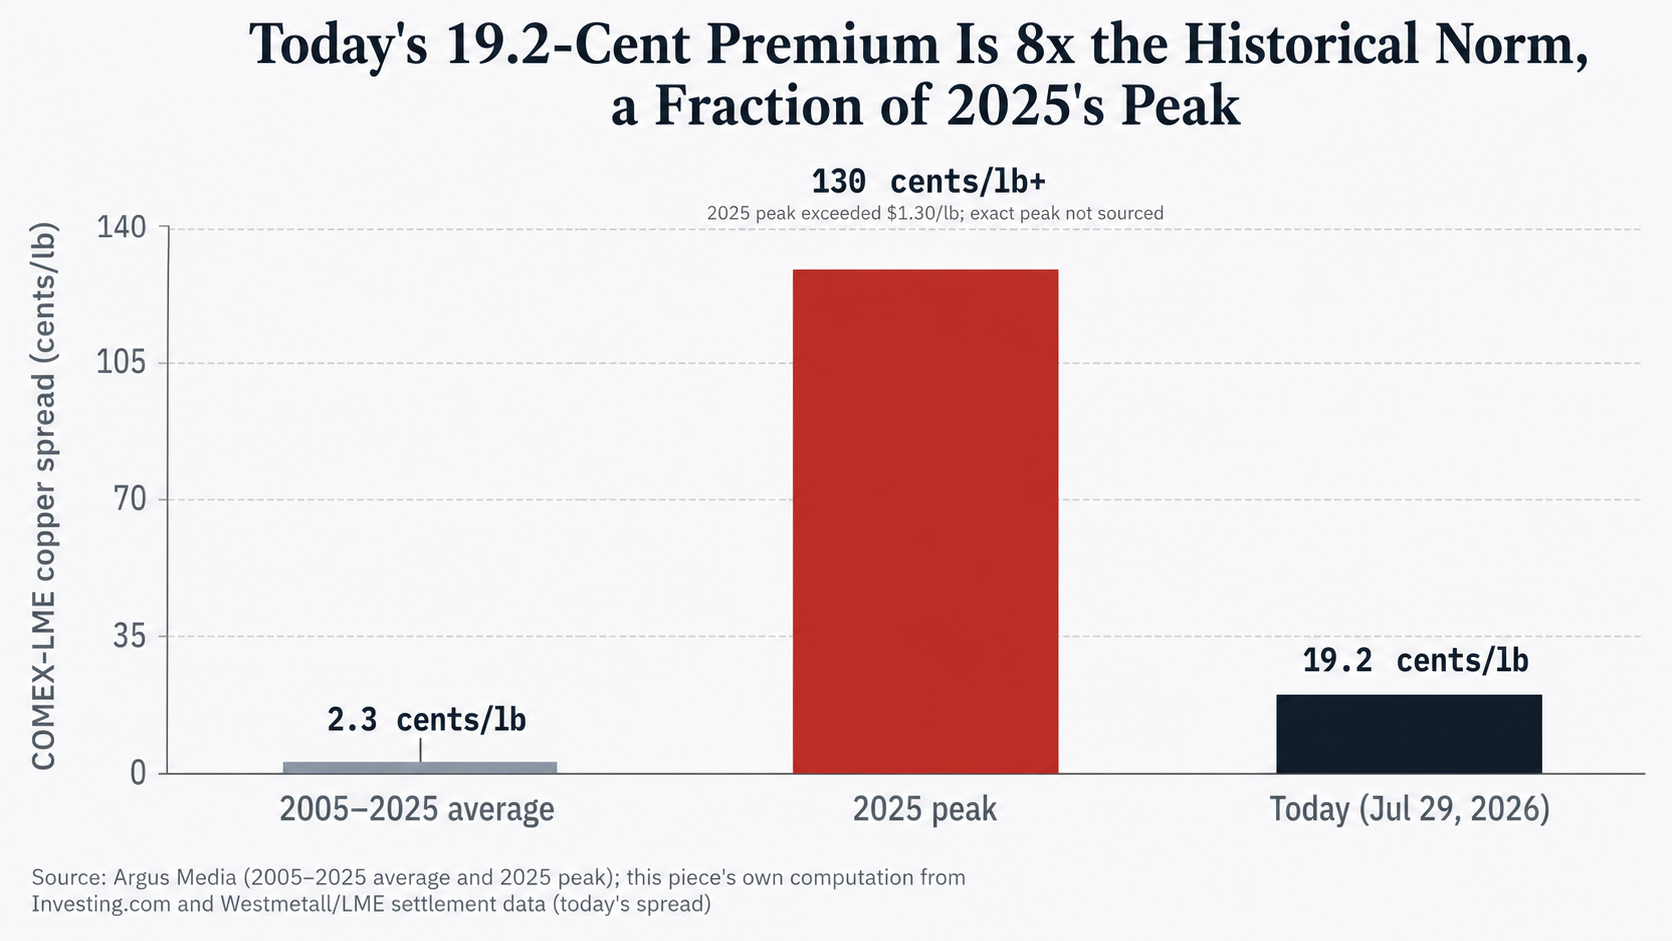
The 19.2-cent COMEX-LME copper premium is roughly eight times the 2005-2025 average but remains well below the 2025 peak. Source: Argus Media and Westmetall/LME settlement data.
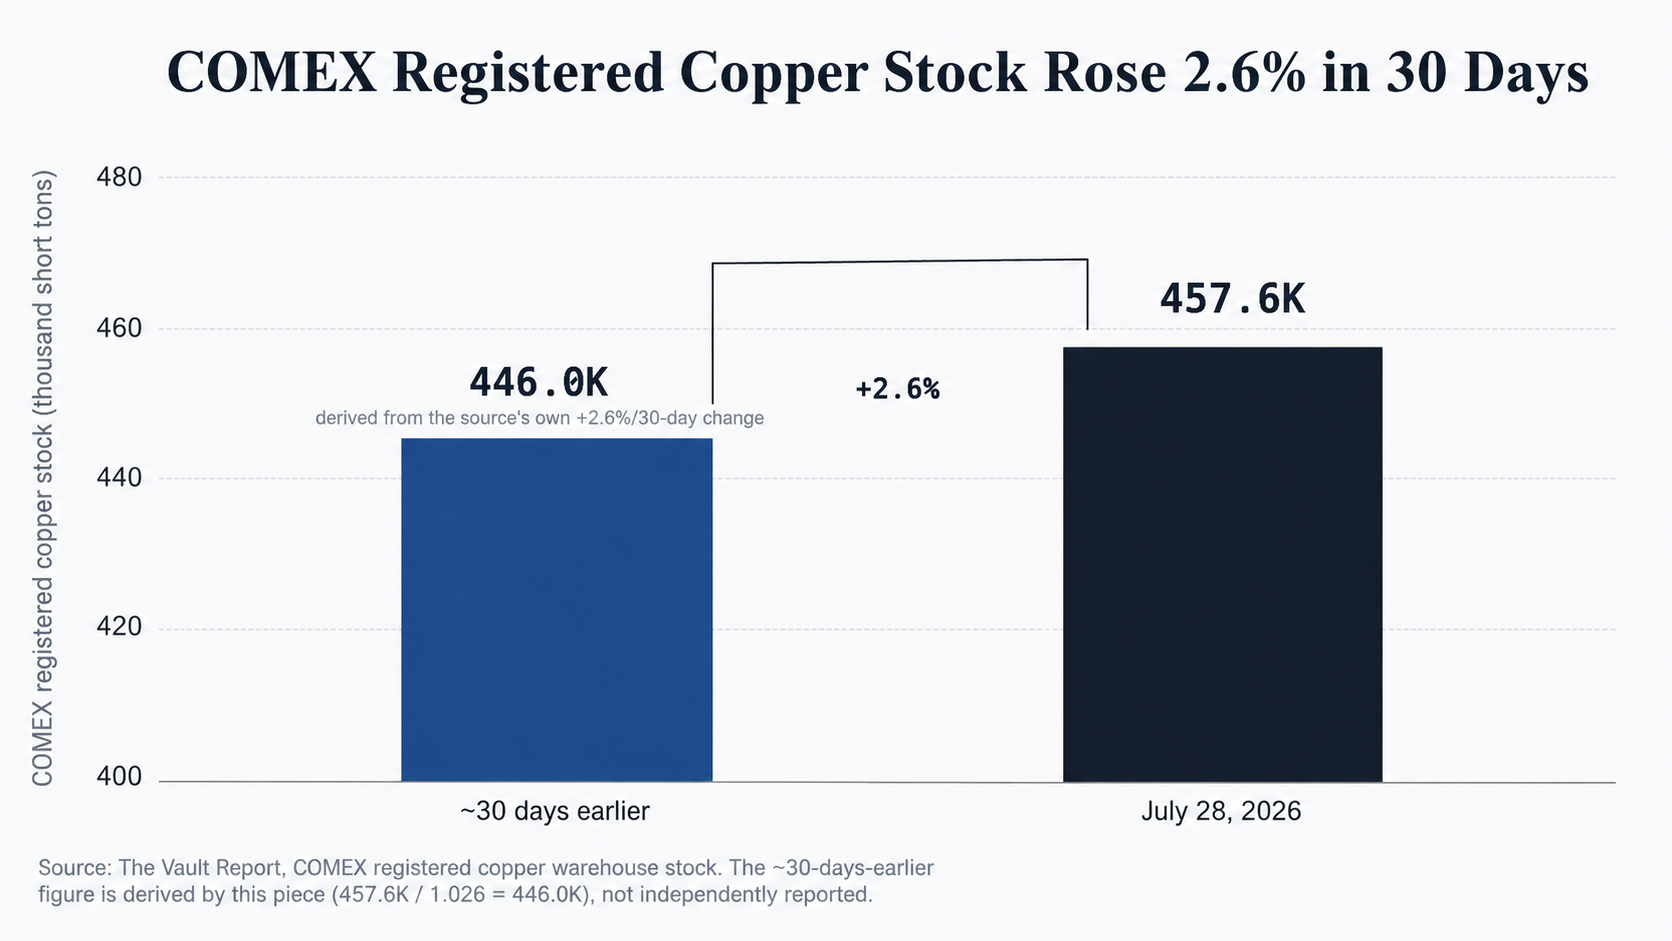
Registered COMEX copper stocks increased 2.6% over 30 days to 457.6K short tons on July 28, 2026. Source: The Vault Report, based on CME/COMEX warehouse data.
Copper Price Targets and Risks
In my view the premium widens again before it collapses, which argues for COMEX copper testing $6.65 – $6.80 by Q4 2026 while the recommended 2027 – 2028 duty stays undecided. My fair entry sits at $6.15 – $6.30, where copper has held since the June pullback, with room to add on a retest of $6.00. My invalidation is a close below $5.85 alongside the spread compressing under 8 cents per pound, the two together saying the market has stopped pricing the duty at all. Two risks sit outside the thesis. September is the live one, with three officials already on record for a hike, and a dollar bid on that outcome would cap copper for weeks. Positioning near its 2026 highs can also unwind fast on nothing at all. Goldman Sachs’ own June 2, 2026 upgrade of its end 2026 LME target, to $13,735/tonne ($6.23/lb), cites “US imports… reflecting the now-open import arbitrage”, which confirms the mechanism from the other side. Add today’s premium and Goldman still falls short of my case. It hasn’t priced the widening.
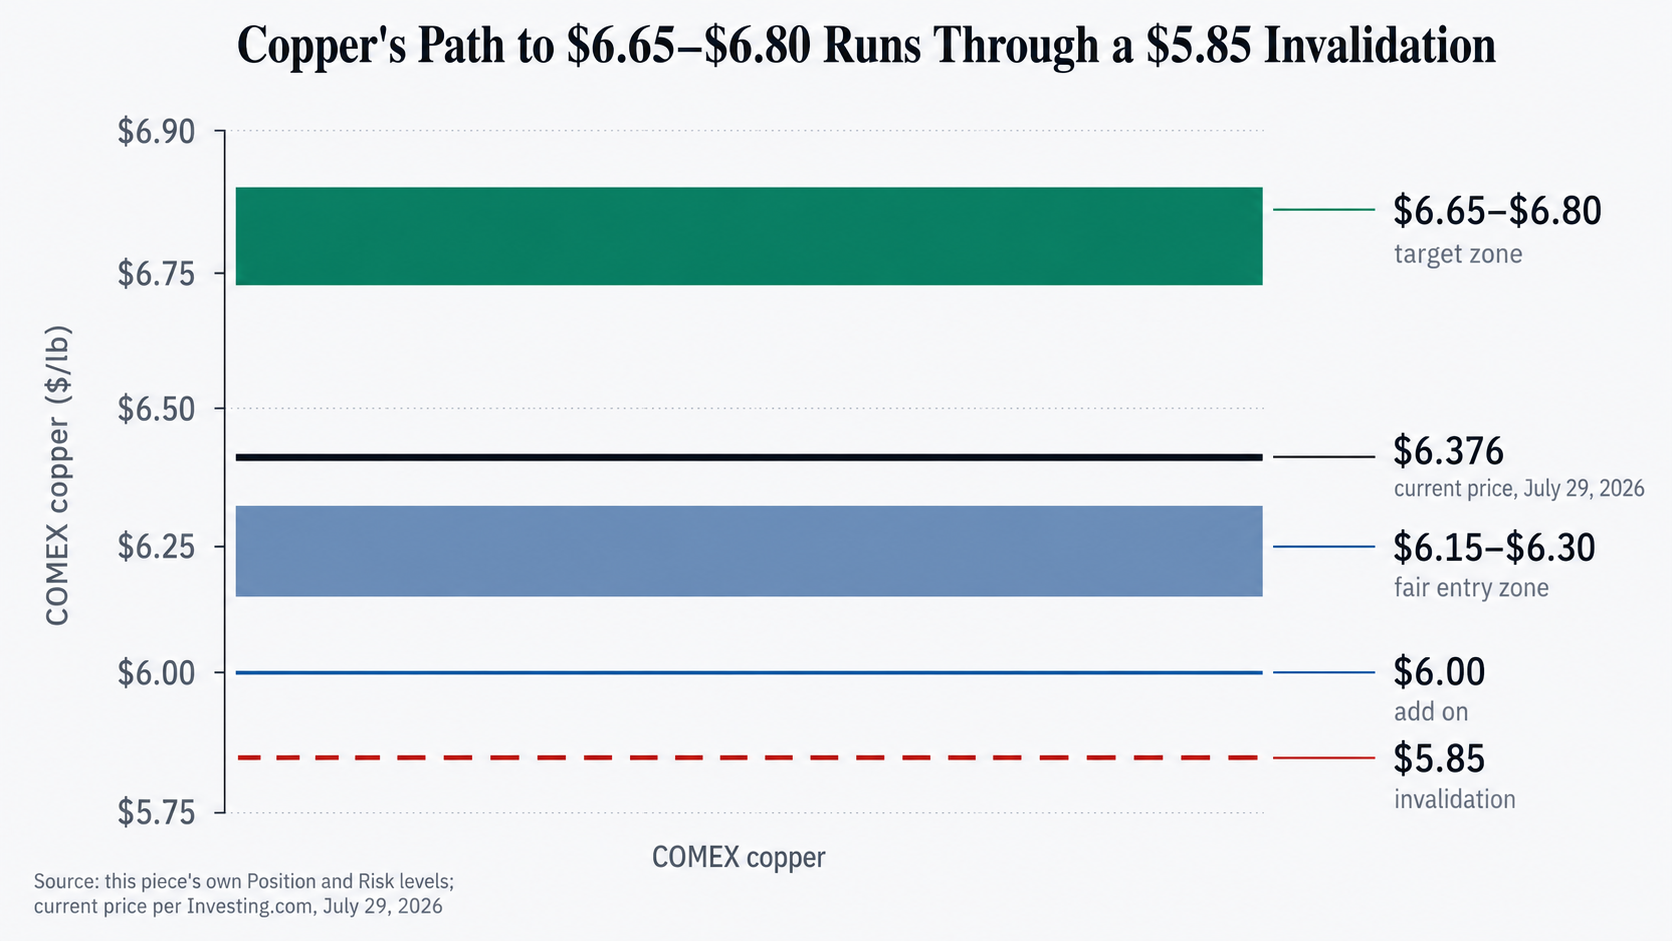
The bullish setup targets $6.65-$6.80, with a fair-entry zone at $6.15-$6.30 and invalidation at $5.85. Source: Author’s analysis; current price from Investing.com as of July 29, 2026.
Copper Price Outlook: $6.65-$6.80 by Q4 2026
My base case is a COMEX copper move toward $6.65 – $6.80 into Q4 2026, on an import premium that survived its first deadline. One thing resolves it i.e. a presidential decision, and a January 1, 2027 start leaves little room past Q4. Rejection compresses the premium. Confirmation converts it from expectation into landed cost. The TC/RC squeeze at Chinese smelters is a related pressure.