


Renewed conflict shuts Hormuz with The US to ‘takeover’, but do we need to price in higher?
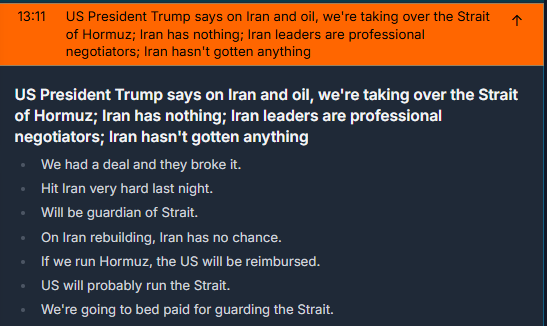
Newsquawk headline summarizes President Trump’s comments on a U.S. role in guarding the Strait of Hormuz. Source: Newsquawk, July 13, 2026.
In this report: We look at Several elements of pricing in the market and how China can turn this entire book on its head.
Last week. Brent +4.46% ($3.05) Open $68.68 High $76.08 Low $67.82 Close $71.51
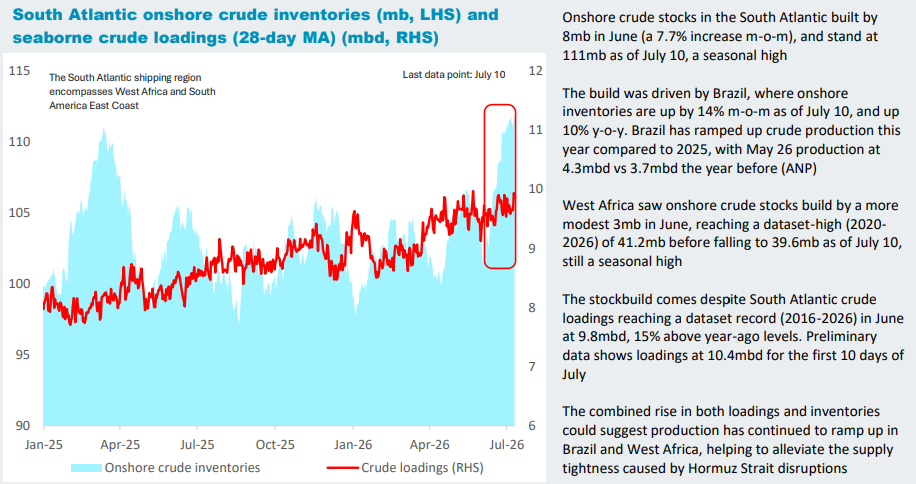
South Atlantic crude inventories and seaborne loadings rise as Brazil and West Africa add supply. Source: Vortexa.
Oil Market Outlook: Four Forces Shaping Brent Prices
There are 4 key factors in the oil landscape currently that need to be understood. It is my view that price action is on a knife edge at the moment. Does this renewed closure of the straight actually impact price the way we think it should….Up? Or is this new closure going to actually have far less impact than the first, if any? Is it that simple? This is not even accounting for how hard Russia is getting hit at the moment from Ukraine. Read below for a Russian brief.
Here they are and here is what we have to balance. Welcome to oil!
- The MOU is dead and The SOH is closed again with a US blockade. Traffic is reduced to 52% WoW-source: Kplr.
- Easing of supply is real across the global network, with local MENA region remedies, OECD strategic releases, but we are also seeing large builds of stores in the South Atlantic market from Brazil and West Africa. These add to the overall SOH relief.
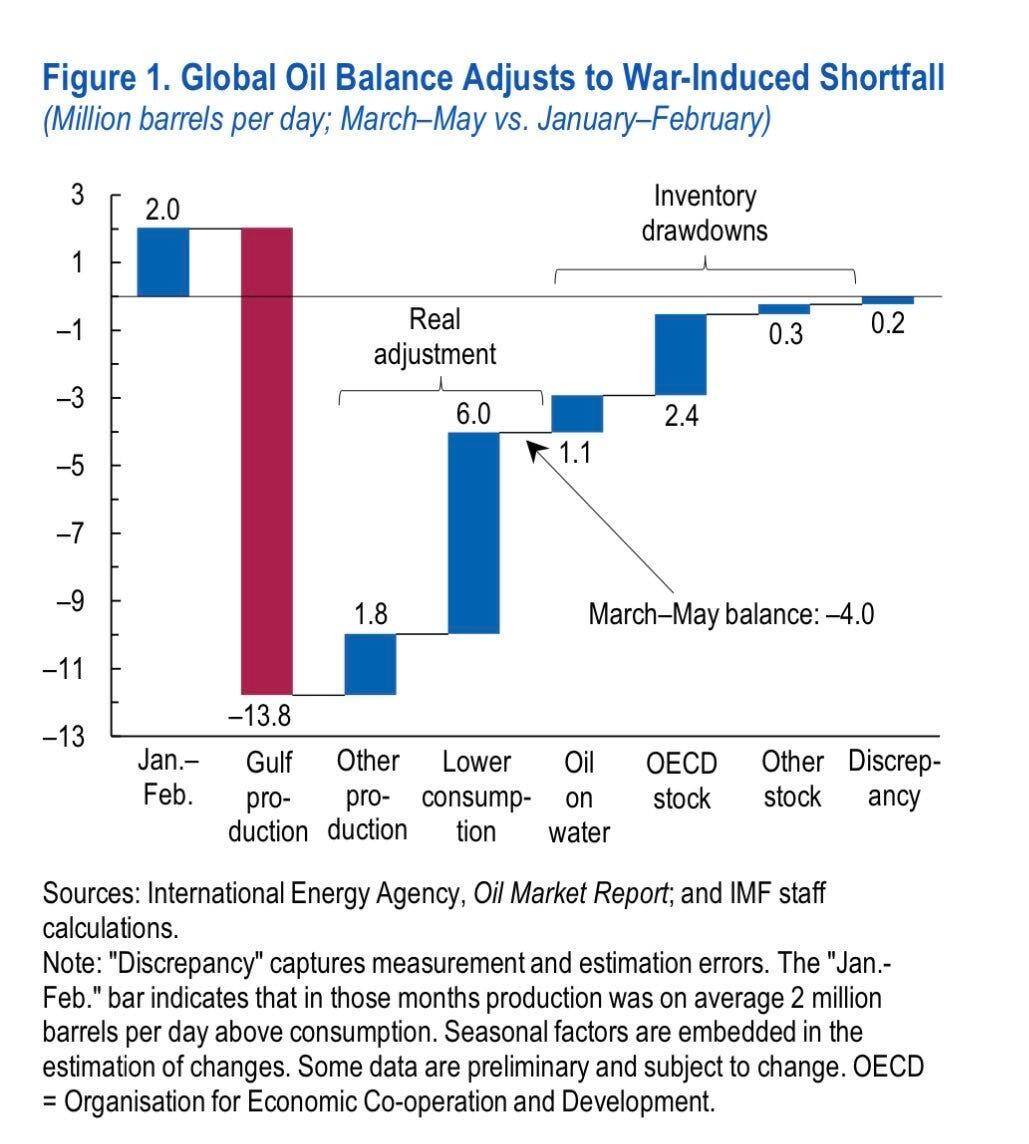
Global oil-balance adjustment to the war-induced shortfall, March–May versus January–February. Source: International Energy Agency Oil Market Report and IMF staff calculations.
Price reaction is limited and controlled. The reaction to a new closure has been bid up but limited in scale. We will need a new catalyst and extended closure time, to reaccelerate up. The US blockade that comes into force on Monday has found some strong volumes of buying. However, this was met with limited upside as of 5pm GMT.
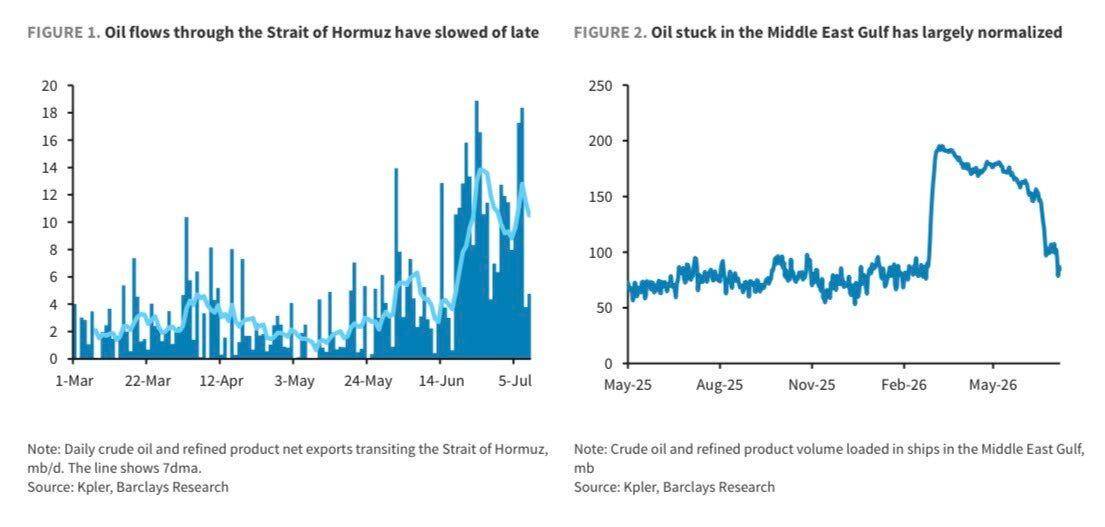
Oil flows through the Strait of Hormuz have slowed while Middle East Gulf stocks normalize. Source: Kpler and Barclays Research.
- Tightness continues to haunt the landscape with strategic reserves masking the shit show. Inventories thus continue to be propped up. The mini glut we currently see, is largely down to this and two other factors. 1. Chinas withdrawal from the import scene with Chinese refining maintenance runs a small factor. 2. A wave of relief ships laden with oil exited The SOH over the last 3 weeks. More in China section below.
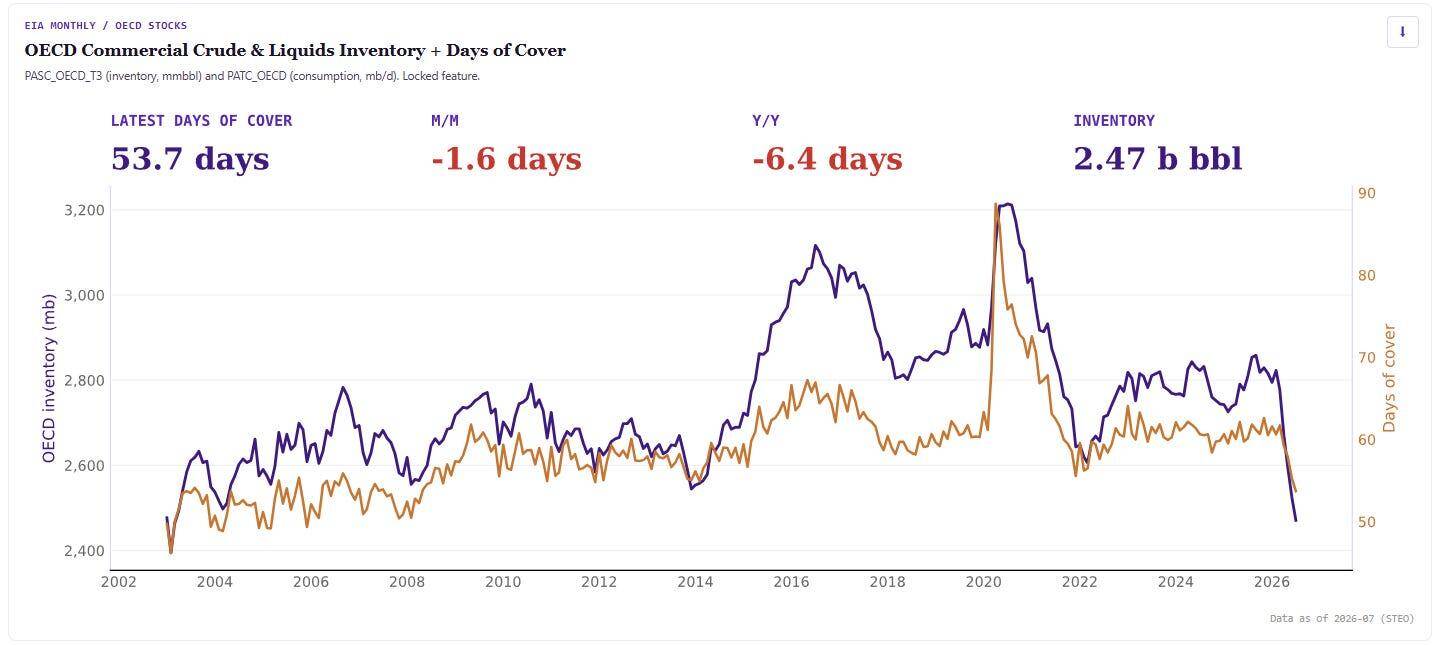
OECD commercial crude and liquids inventories and days of cover. Source: U.S. Energy Information Administration, Short-Term Energy Outlook.
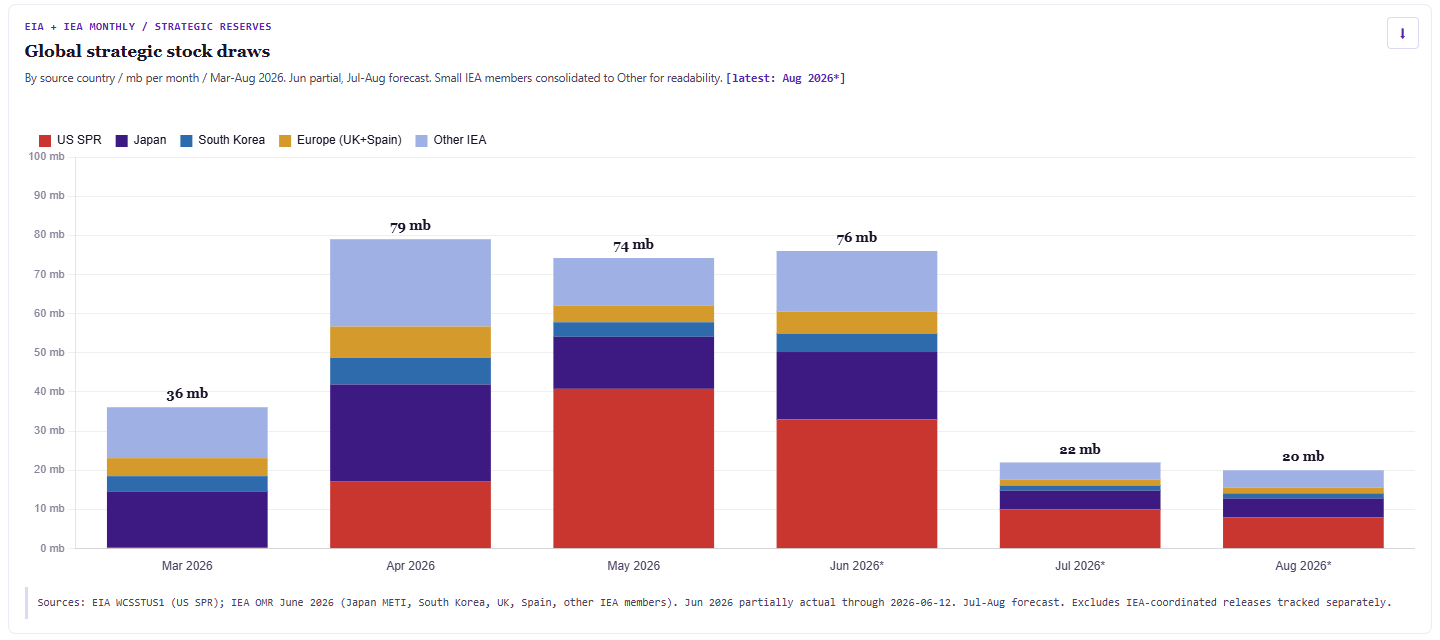
Global strategic stock draws by region, March–August 2026. Source: U.S. Energy Information Administration and International Energy Agency.
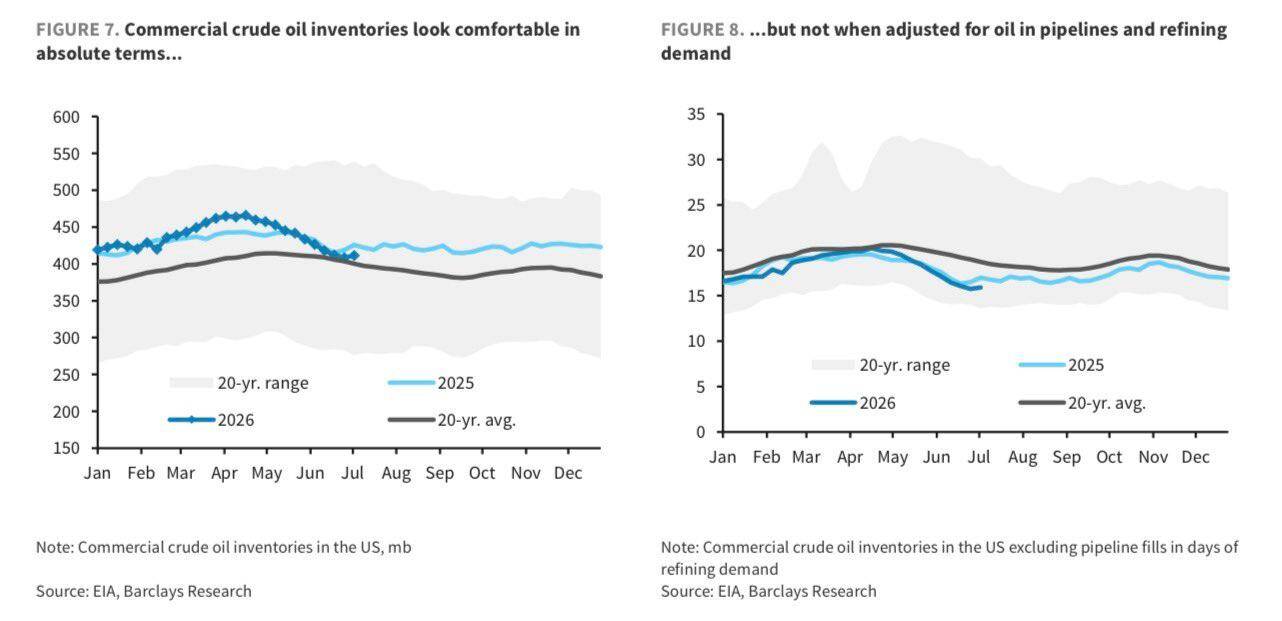
U.S. commercial crude inventories appear comfortable in absolute terms but tighter after adjusting for pipeline fills and refinery demand. Source: EIA and Barclays Research.
Brent Oil Price Forecast
Every new Brent Oil analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Brent Oil forecasts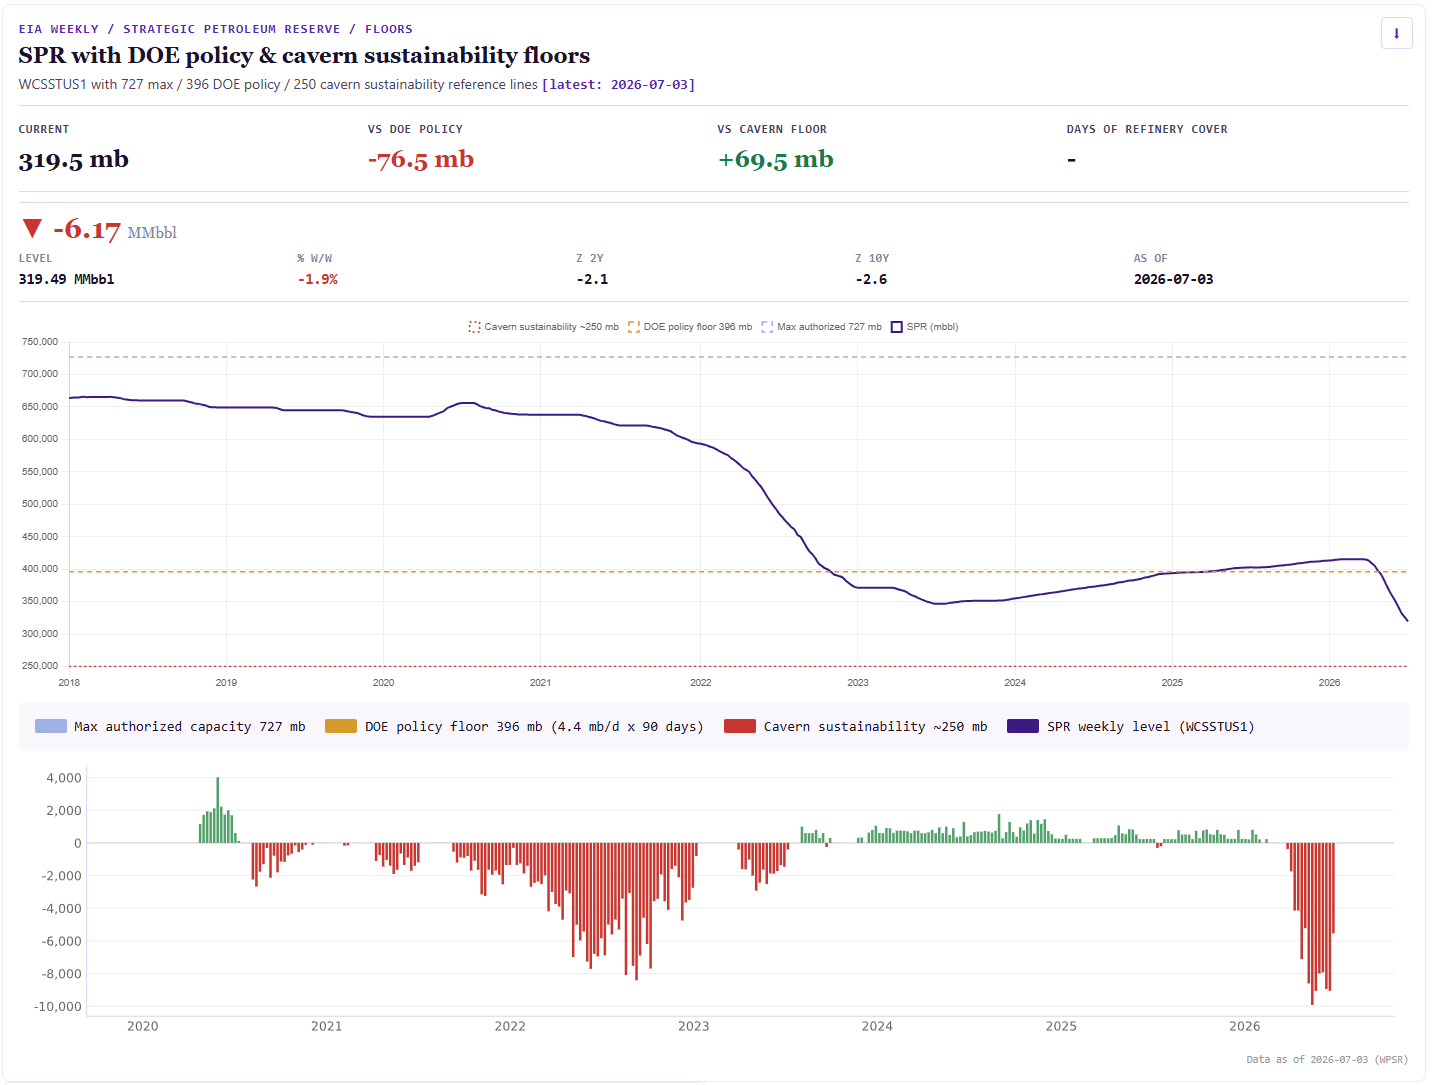
U.S. Strategic Petroleum Reserve level versus policy and cavern-sustainability floors. Source: U.S. Energy Information Administration.
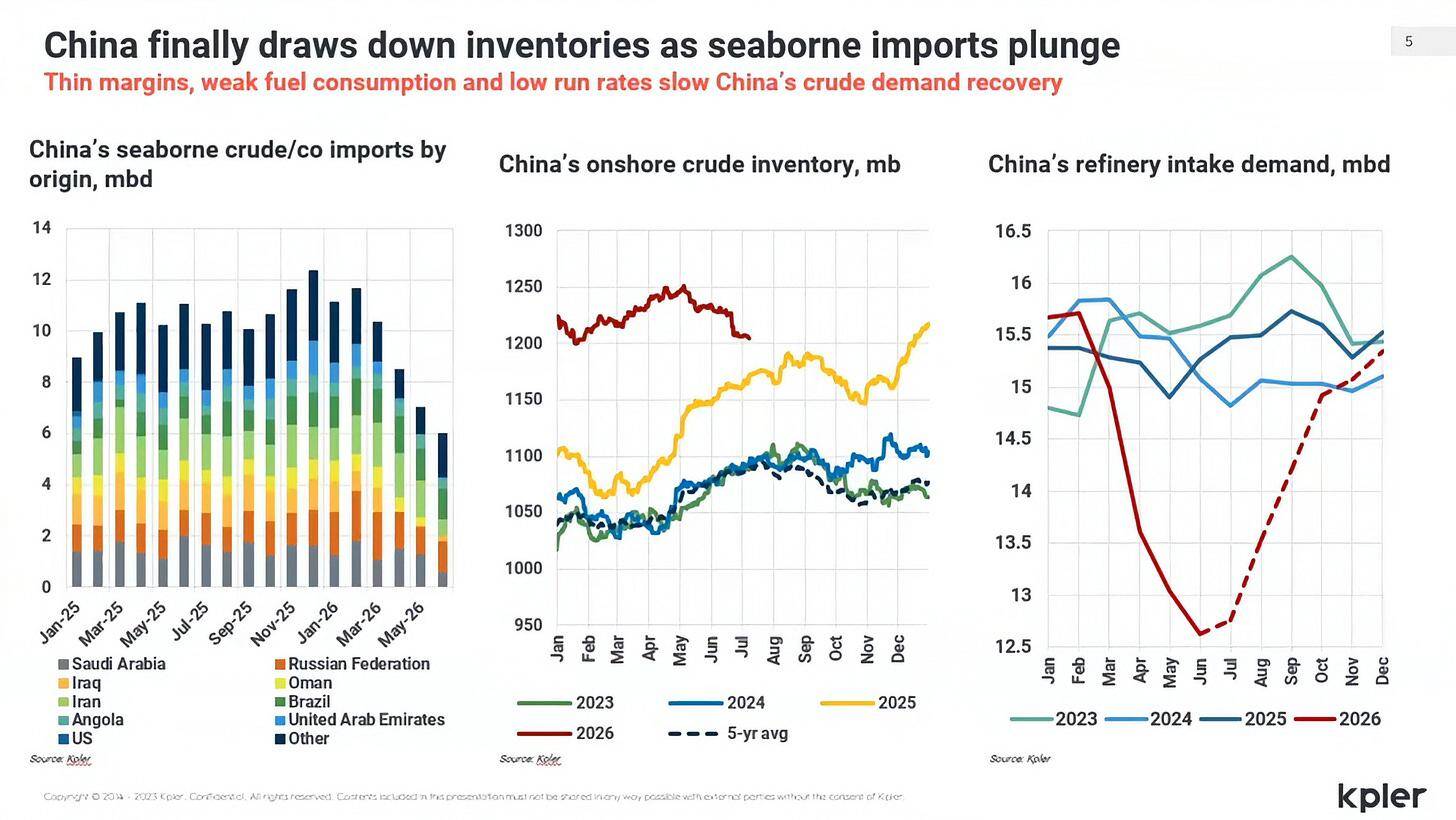
China’s Crude Import Slump Could Reverse the Oil Trade
China quietly cut its crude imports to 5mb/d since Feb, close to half of what it was buying before. The barrels that then left Hormuz heading east started to pile up at refiners who were not taking them.
Shandong teapots ran at 50.5% in late May, a nine-year low; the national average was 66.3%; May processing fell 9.1% year over year. The reasons are expensive crude, crushed refining margins, weak fuel demand, the fuel-export ban – and, importantly, EV adoption accelerating once oil pushed above $100
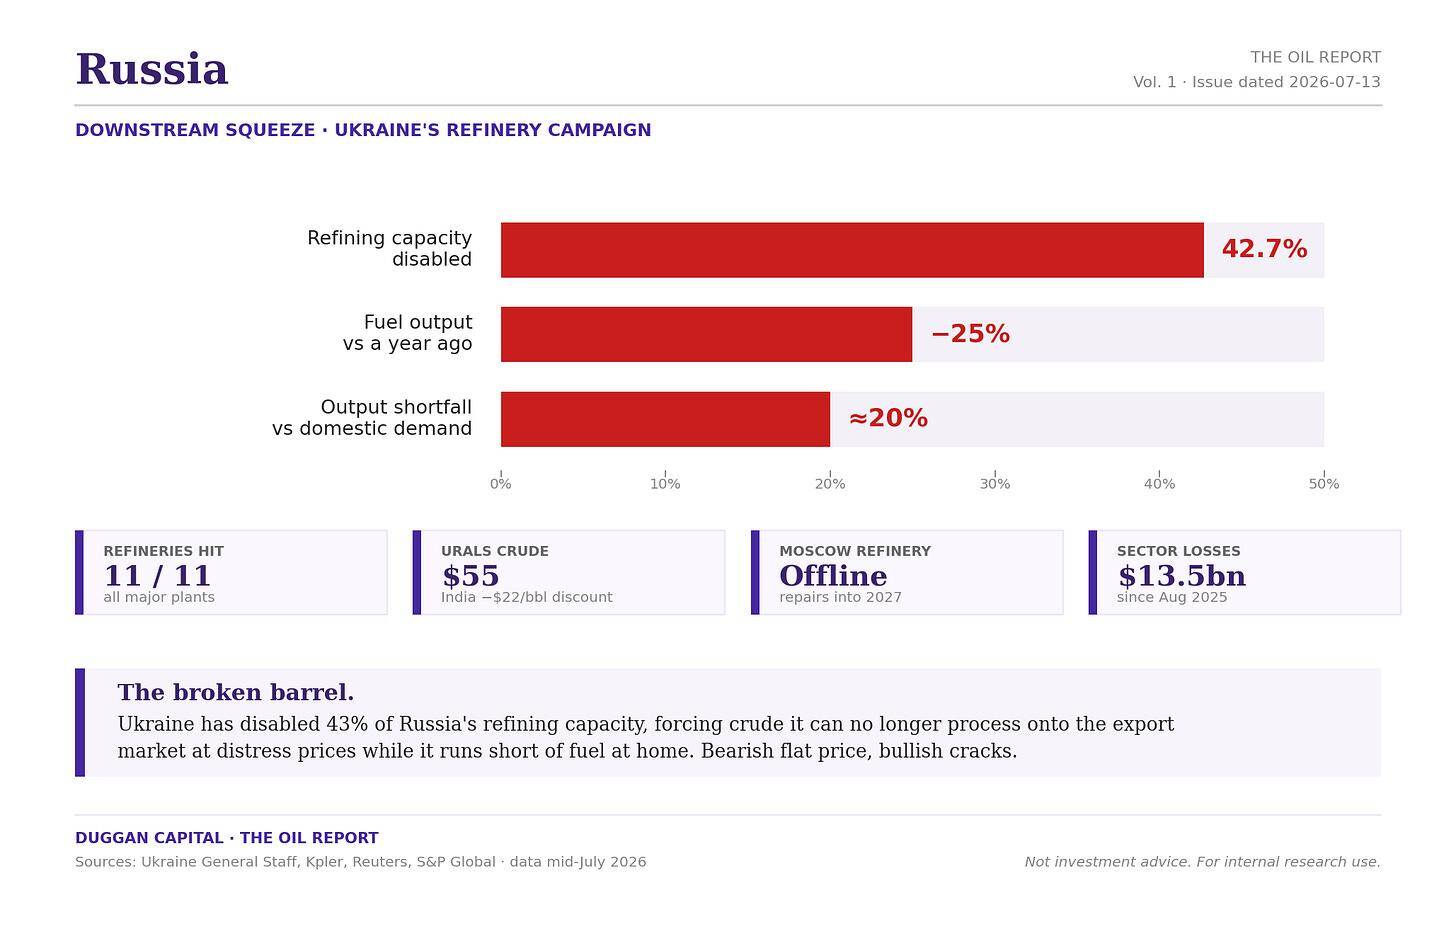
Impact of Ukraine’s refinery campaign on Russian refining capacity and fuel output. Source: Duggan Capital, citing Ukraine General Staff, Kpler, Reuters and S&P Global.
Ukraine has spent 2026 dismantling Russia’s refining base rather than its oilfields, and that distinction is now moving the barrels. Long-range drones have disabled roughly 43% of Russian refining capacity, hitting all eleven major plants; Omsk, the largest, has been offline since 6 July, and the Moscow refinery is not expected back until early 2027. June fuel output fell 25% year on year and now runs about a fifth short of domestic demand, forcing Russia into the strange position of importing refined product. The market consequence is clean: crude Russia can no longer process is being pushed offshore at distress prices, Urals near $55 with Indian cargoes clearing at discounts of around $22 a barrel, even as India and China quietly trim their intake. That is the whole trade in miniature. Broken refineries add crude to a market already glutted and pull product out of one that is tightening. Bearish flat price, bullish cracks, and one more reason the Strait’s closure is not doing what the headlines expect.
Middle East Export Competition Limits Hormuz Risk Premium
UAE Bypass Capacity Adds Hormuz-Free Supply
UAE, fresh from its divorce from OPEC has been out on the town. Increasing its OPEC held production quota from the 3.2mb/d to 4.5mb/d with a short-term target of 5mb/d. The Habshan–Fujairah pipeline (ADCOP) carries UAE crude to the Fujairah terminal on the Gulf of Oman, outside the Strait of Hormuz – currently moving about 1.5 million b/d against 1.8 million of capacity. And a new bypass pipeline is roughly half-built and being accelerated, with reporting that it could double the UAE’s Hormuz-free export capacity by 2027. So a free-agent UAE isn’t just adding barrels — it’s adding barrels that can reach the market even if the strait is shut.
Saudi Arabia Cuts Pricing to Compete With Murban
As of a Kplr call last week, we can see the arbitrage op that caused Saudi to drop its OSP (open selling price). They are competing with the ex-wife of UAE on price. It’s no good that UAE left and is increasing its production. So a good move by UAE overall but now Saudi is forced to ask less if it wants to be competitive to buyers in the market. The UAE grade is the Murban grade in orange. Saudi is the Arab light in black.
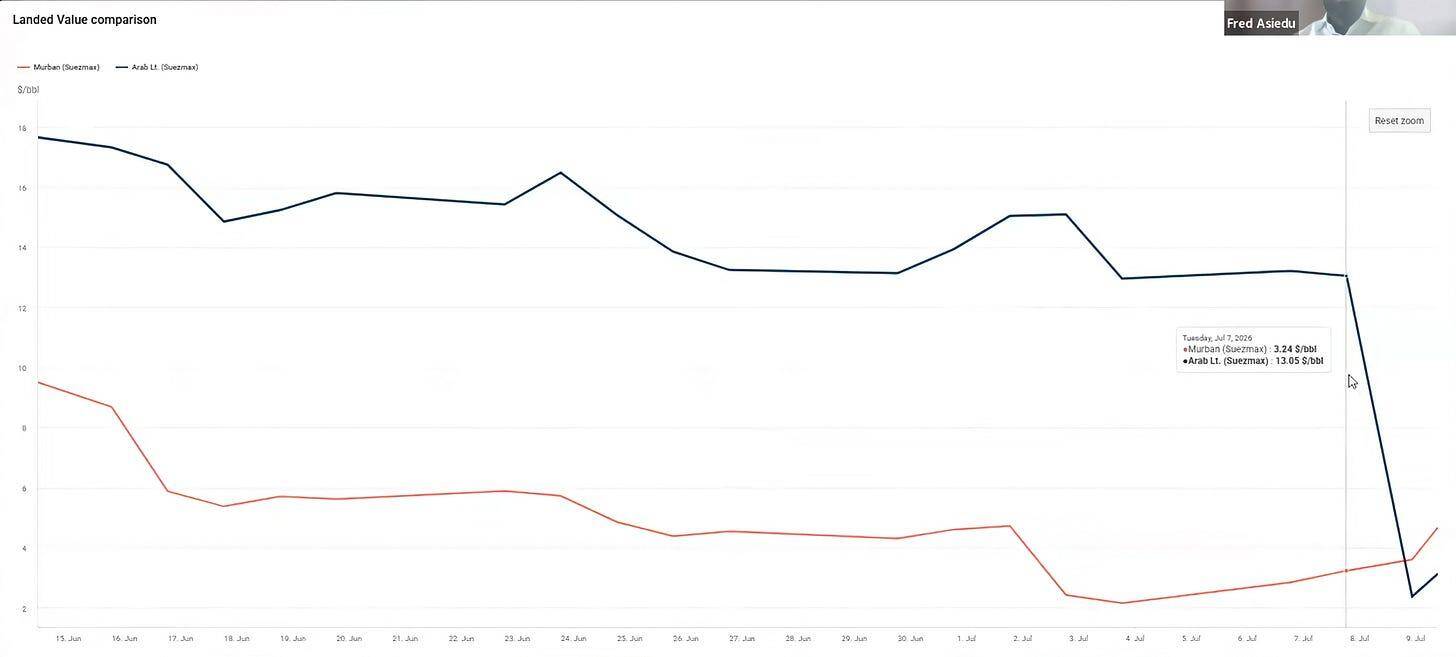
Saudi Arab Light and UAE Murban pricing comparison. Source: Kpler.
Brent Short-Squeeze Risk Builds as China Returns
So we have to be careful…as always. I believe that we are perfectly primed for a short squeeze, but this time, unlike the Maduro kidnapping, we don’t have such a binary event. The short squeeze is happening with a combined thesis that 1 The SOH is closed again now as of writing with a new US blockade (but not completely, given the Oman southern route remains open but perilous). 2. That China are returning to higher refinery utility rates and a more attractive ‘non panic buying’ average price.
I think small money is trading 1- the re-closure, and smart money is quietly buying the 2nd. If this is the case, we need more evidence to see exactly how much China has returned to the markets. I don’t have that data yet. Perhaps these new rock bottom Arab light prices will bring China back?
Brent COT Report Signals Crowded Shorts
The positioning analysis below uses the ICE Futures Europe Commitment of Traders report for Brent futures and options for the week of July 7, 2026.
I’m changing my mental model on swaps dealers back to being confluent with their client’s directional bias. My prior mental model of looking at them as inverse to their clients positioning was wrong and only served me when judging swaps v Money managers.
To be clear, I now look at swap dealer’s directional bias in futures as being confluent with their clients. If swaps building longs, their cleints are building longs. I do not see their size as being equals to exactly their client positions, as it is only a reflection of how much of their clients positions they want to hedge off in futures and options. Welcome to the nuances of reading a COT report.
In the latest COT, we see swap dealers actually trim their short positions by almost 25% 21k contracts. They also added 4.8% to longs +21k contracts. On the other side, in speculators MM, only added 180 contracts to the short side, reducing longs -367 contracts. I suspect the speculators MM are feeling a little pain since we are up 3% on price $74.30 since last Tuesdays close at $72.20.
Other Reportables being net short actually grew their net short by 45%. INSANE! I feel a squeeze a coming!
The read. I think swaps are positioning nicely for a larger move back up in the face of renewed tensions and a new closure of The SOH. MM Specs seem to have held their short conviction into a lifting market. MM remain crowded short on all time horizons. We will have to wait until this Friday to see if they are continuing to sell into this rise, but let’s be clear, they have little size left to deploy. This is what crowding tells us. Moreover, Other Reportables is insane, they grew their net short by 45%
Market positioning reflects growing short-squeeze anxiety.
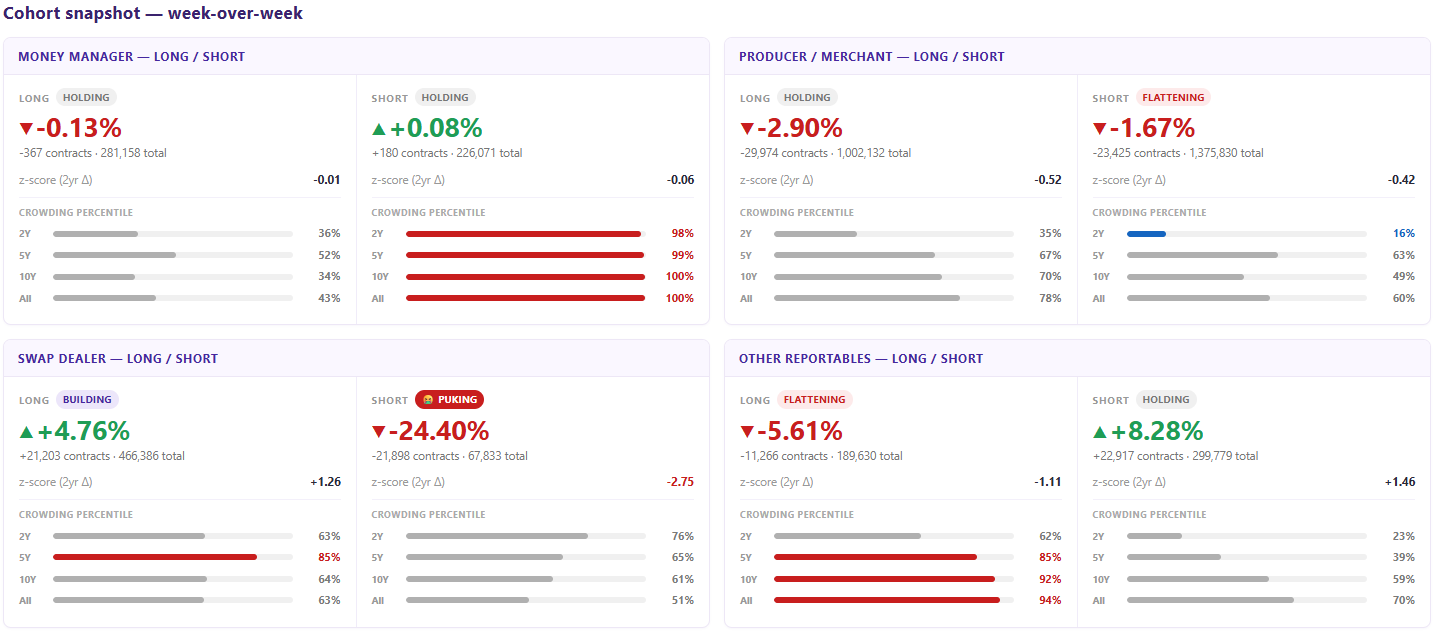
Week-over-week COT positioning by trader cohort. Source: ICE Futures Europe COT data; Duggan Capital calculations.
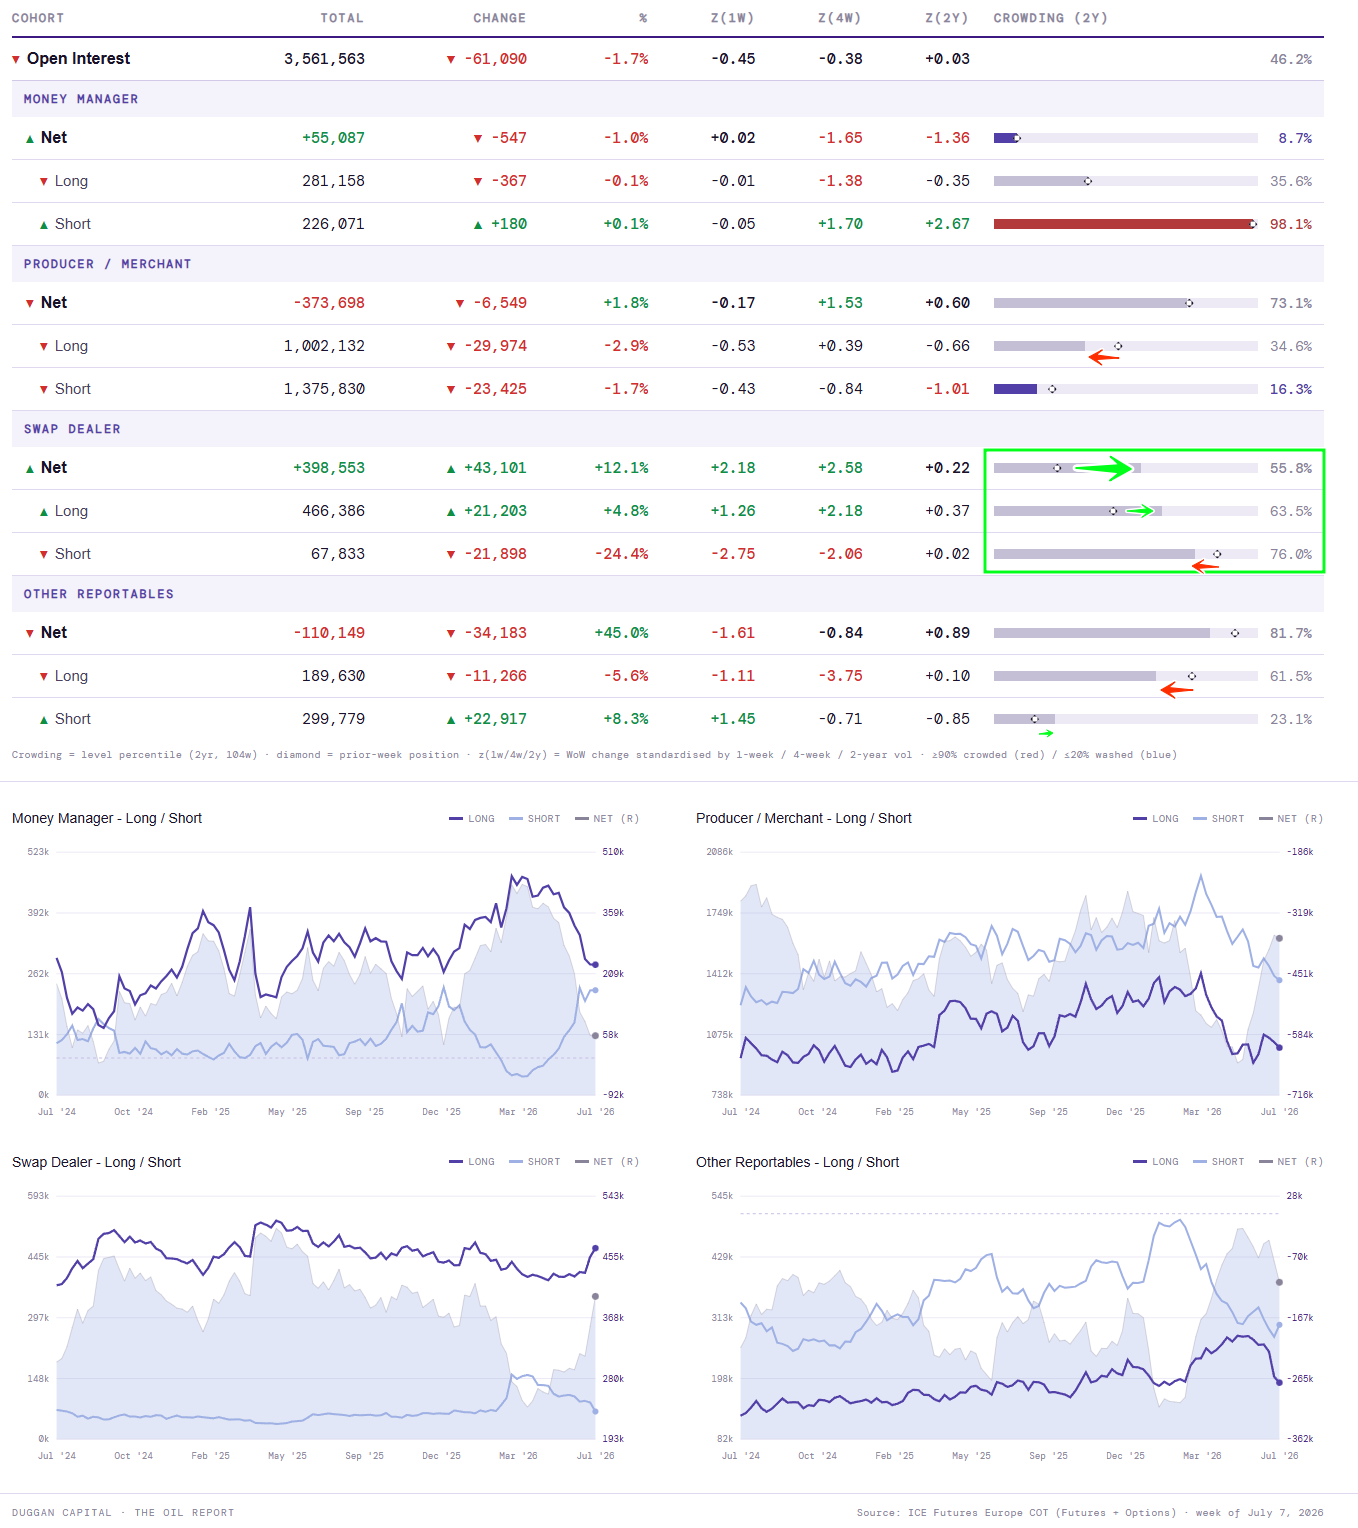
Brent futures and options positioning and crowding metrics for the week of July 7, 2026. Source: ICE Futures Europe COT data; Duggan Capital analysis.
Brent Trade Outlook: Upside Risk Remains in Focus
Trade thesis is boringly not that unchanged at all from last week. Price risk is firmly tilted to the upside. Wednesdays EIA report will be a pretty explosive one I think. If we continue to press further on product exports, while going into a new 2nd major round closure & blockade, its spelling trouble for consumers everywhere at the pump.
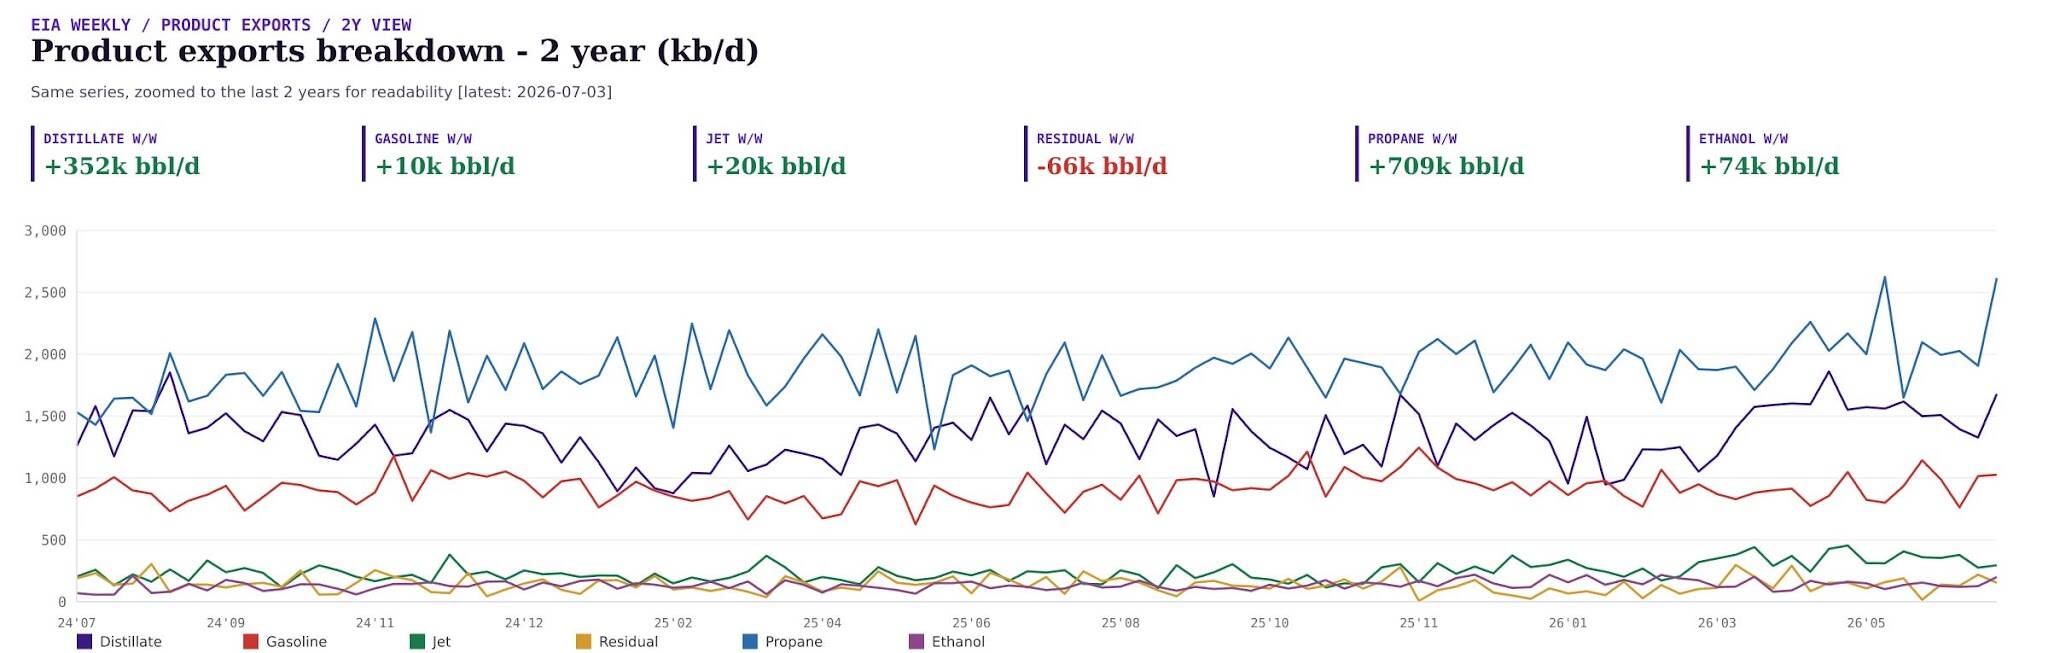
U.S. petroleum-product export breakdown over the past two years. Source: U.S. Energy Information Administration.
The buying areas continue to hold after they traded last week on Friday on the pullback. Nice action. The breakout higher will be violent when it happens, but please be careful, as we need a more fundamental war risk driver in order to push meaningfully higher. For now, the simple ‘closed again’ is a little worn out as a catalyst. Despite a US blockade also renewing. My view is to stay long, stay exposed, and keep the hedges in place. This is not trading or investment advice.
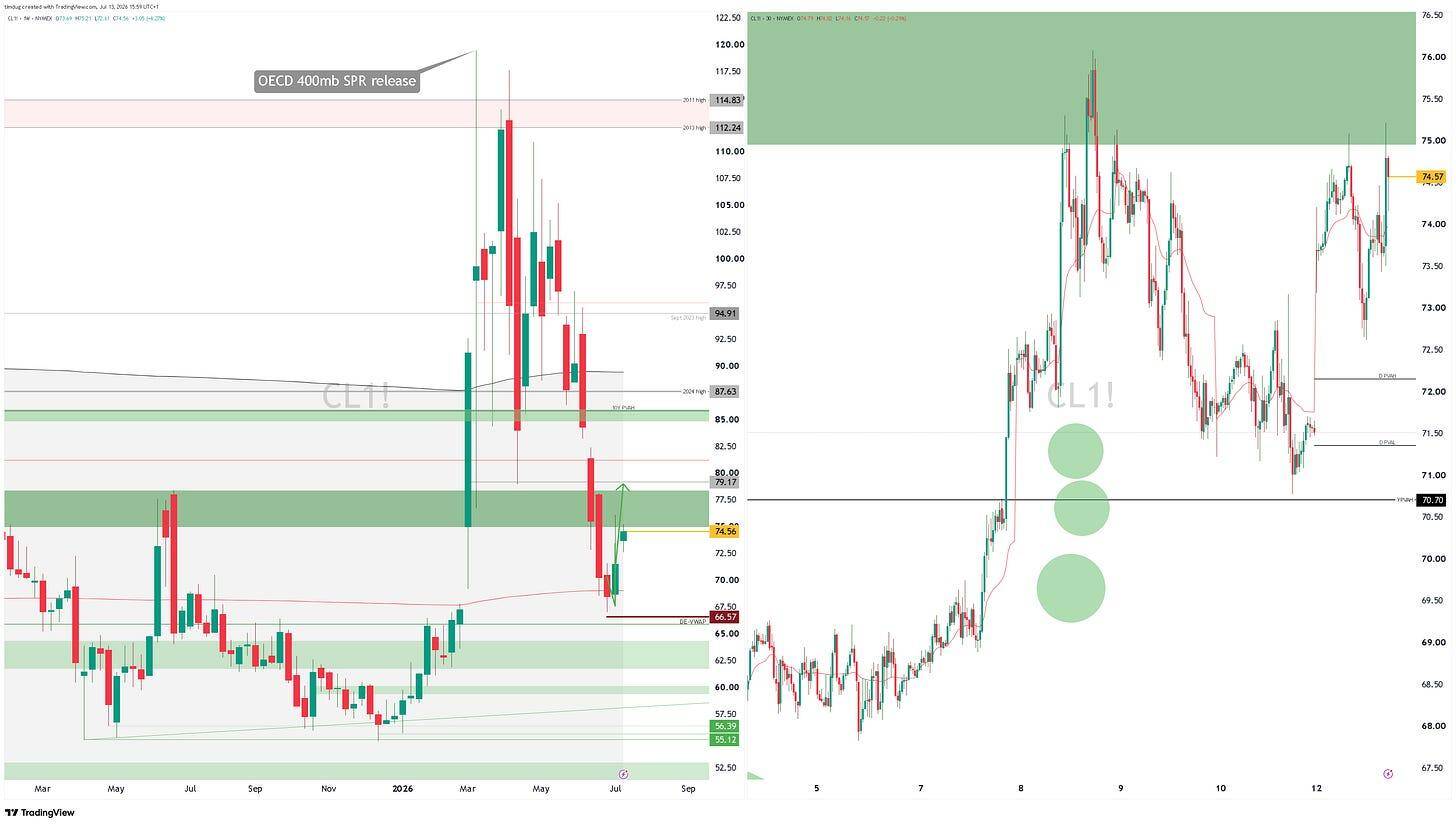
Brent crude price action and technical levels on weekly and intraday charts. Source: TradingView.
That’s the report.