My critical assessment read of where are is below. In short, we need to make it to Fridays June 19th signing in Switzerland without major incident. But there is one actor that could completely kybosh this entire deal: Netanyahu. The US MUST, as part of this Memorandum of Understanding (MOU), restrain Israel. It is important to note that we are in NO WAY out of the woods. The material changes today are on warfare peace and a restart to transit. This is the largest positive step so far. But the industry has made other arrangements and has moved on to a large degree already.
We are in a 30-day window where the Straight of Hormuz may be open, but there are still constricted shipping factors due to the de-mining.
1. Iran declared itself the winner. Araqchi on state TV: Iran emerged stronger. Sovereignty of the Strait belongs to Iran and Oman. Iran will secure safe passage. This is a country that extracted $300bn reconstruction commitment, $24bn frozen funds, oil sanctions suspension, US forces withdrawal, and a permanent seat at the table on nuclear issues – while keeping its missile program off the agenda entirely.
2. The Strait reopens under Iranian arrangements. Article 5 of the 14-point draft: “Reopening the Strait of Hormuz within 30 days under Iranian arrangements.’’ The PGSA (Persian Gulf Strait Authority) that Kpler’s shipping analyst called out as Iran’s attempt to legitimise control – that is what “Iranian arrangements” means. Iran did not lose the strait. It monetised it.
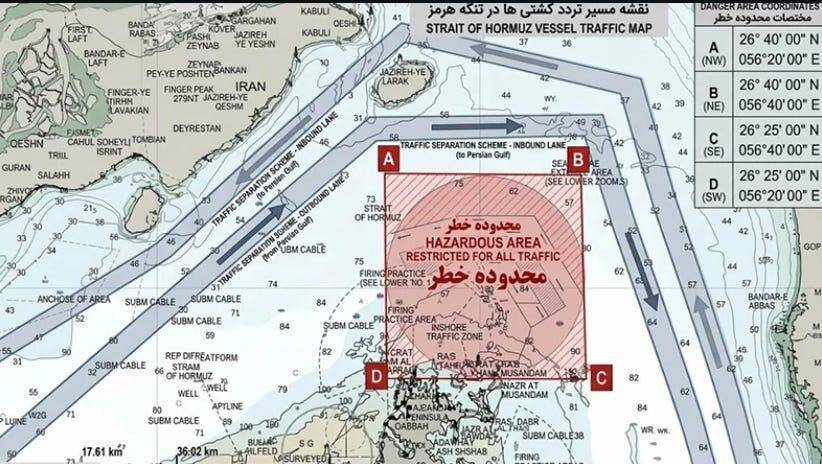
Navigation is opening up. The actually straits that can be safely passed is an extremely tight corridor between Larak Island and Qeshm Island. The minefield illustrated off the Oman coast also clearly highlighted. The work begins on Friday (maybe??) for mine clearance. It will be interesting to find out how much cooperation will happen between the IRGC and US Navy forces to actually clear this area. The Pentagon’s assessment was this would take 6 months. Trump wants it done in 30 days.
3. Tolls suspended for 60 days – not abolished. Trump NYT interview: MOU suspends tolls for 60 days. Not permanently. The tollgate model is paused, not dismantled. At the end of the 60-day negotiation window, if final deal is not reached, tolls resume. Iran’s FM confirmed: if interim deal not implemented, no nuclear talks. The leverage is explicit and retained.
4. Israel is not on board. Israeli Defence Minister opposes IDF withdrawal from Lebanon. Has told Trump directly. If Iran attacks Israel over Lebanon, Israel strikes Iran. Trump reached deal over Netanyahu’s objections – described him as “very difficult.” The Lebanon front is not closed. One incident there reopens the military dimension. The US posture towards Israel will now become interesting.
5. Missile program untouched. Fars News confirmed today: no clause on Iran’s missile and drone program. Not in current understanding. Not scheduled for later stages.
6. $300bn reconstruction commitment. Article 7: US and allies required to submit reconstruction plans worth at least $300bn. This is Iran extracting a Marshall Plan as a condition of the deal. The economic architecture of the new relationship is Iranian reparations from the West. If you make a mess of the place, you gotta pay the cleaning bill!
Current State of the Market
Despite the shoddy shape of inventories, stock and SPR’s, the current flows are not what you think.
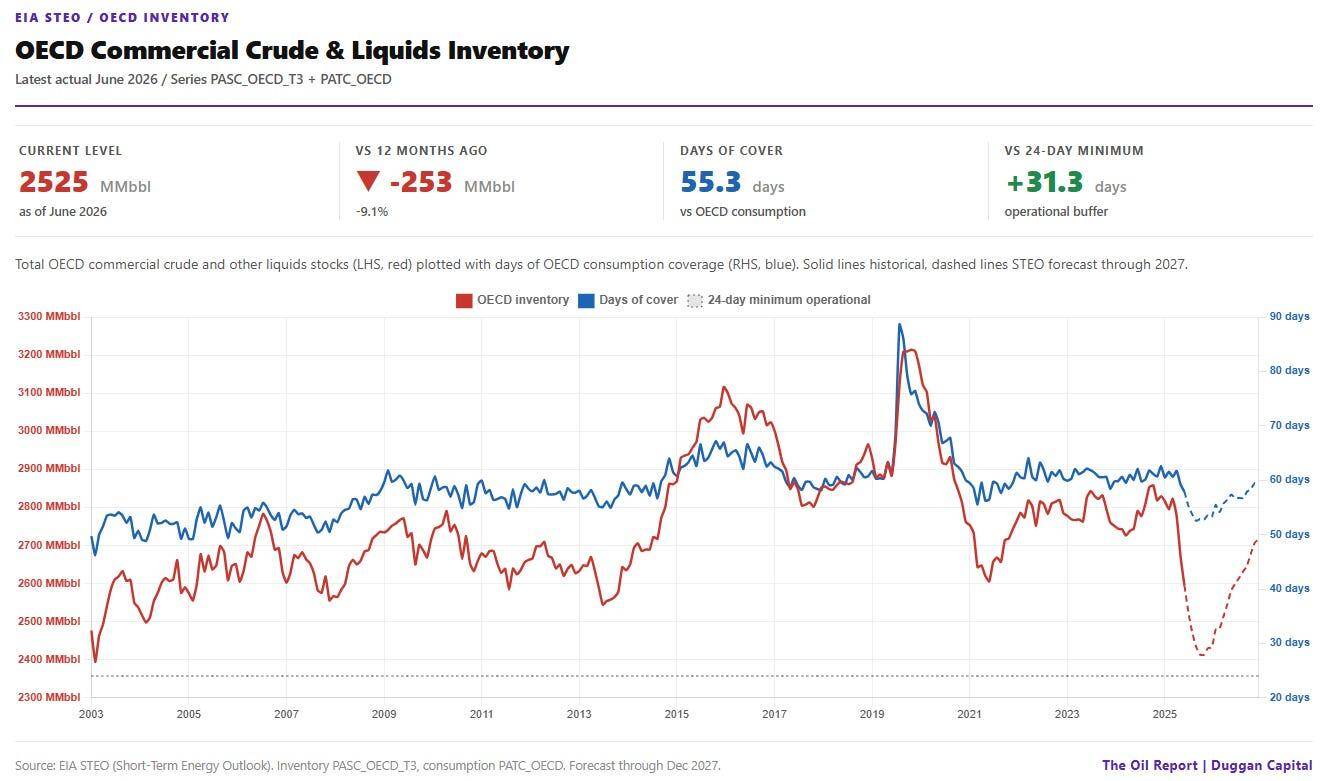
- Commercial inventories in the OECD group run dry in 55 days from today. That is an actual tank bottom on Commercial stocks. See chart below. It is widely discussed now that stocks only need to draw down another 20 days of supply until the actual pipes and system stops functioning normally on commercial stocks. So they are currently being topped up from the SPRs around the world/OECD.
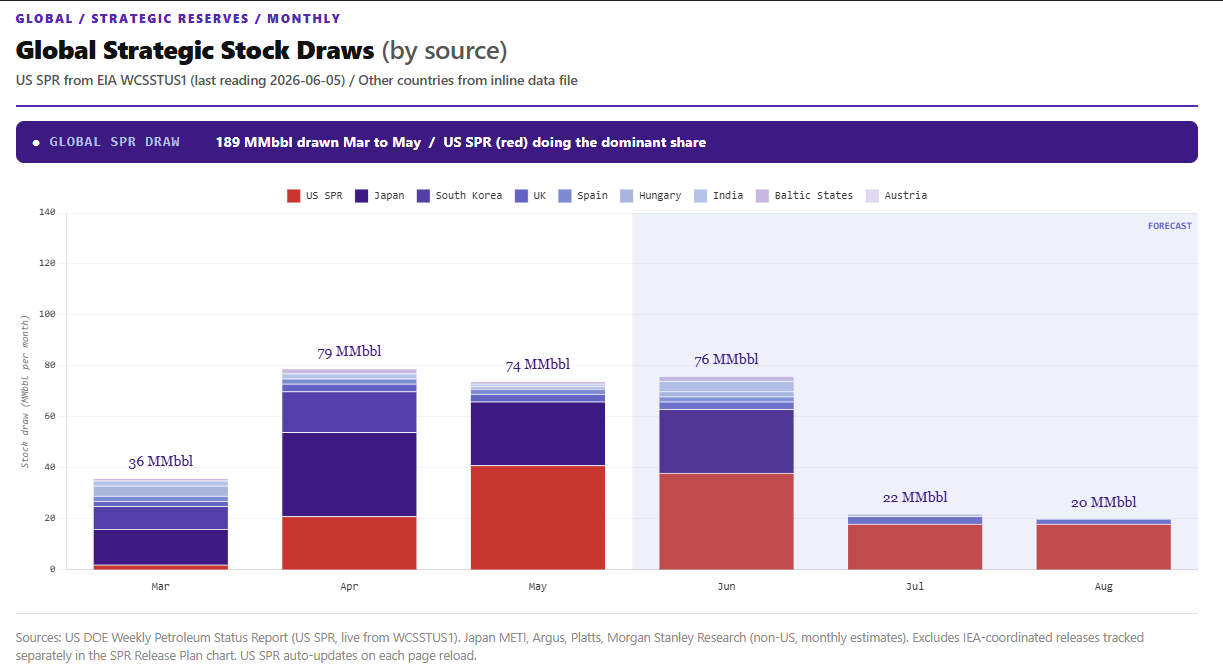
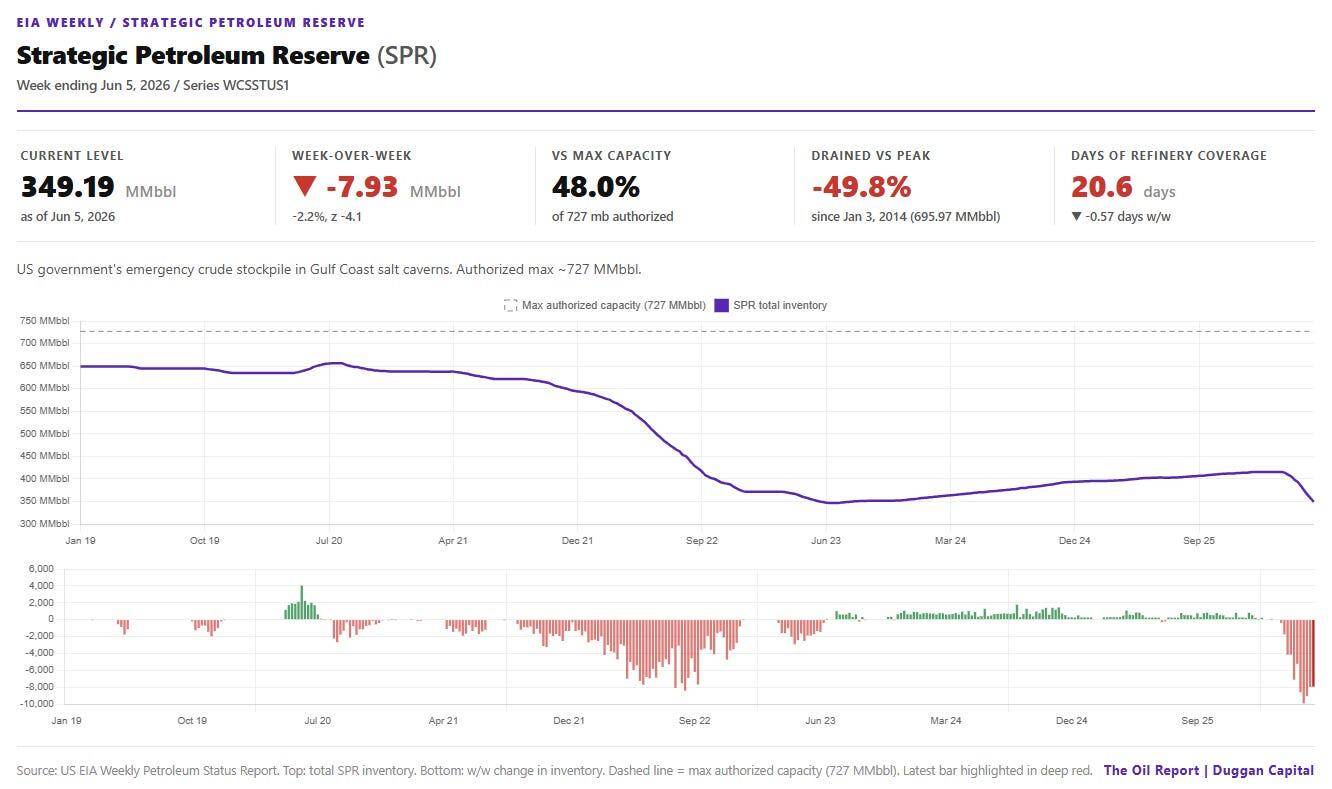
- The OECD coordinated SPR release. The OECD came together in April and agreed to release 400mb into the market from their collective SPR reserves. The US portion is 172mb, scheduled to be fully released by about July 12th. See chart. This is the reserves release that has worked to keep a cap on oil prices to date, combined with a softening of shipping where we now have a meaningful amount of oil transiting daily with the help of CENTCOM . More with maps and Kplr data below.
Brent Oil Price Forecast
Every new Brent Oil analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Brent Oil forecasts
The Deal: What Is Agreed?
Pakistan announced the framework on June 14th after 107 days of conflict. Qatar facilitated. The formal signing is scheduled for Friday, June 19th in Switzerland. The agreement is a memorandum of understanding – an interim framework, not a final deal.
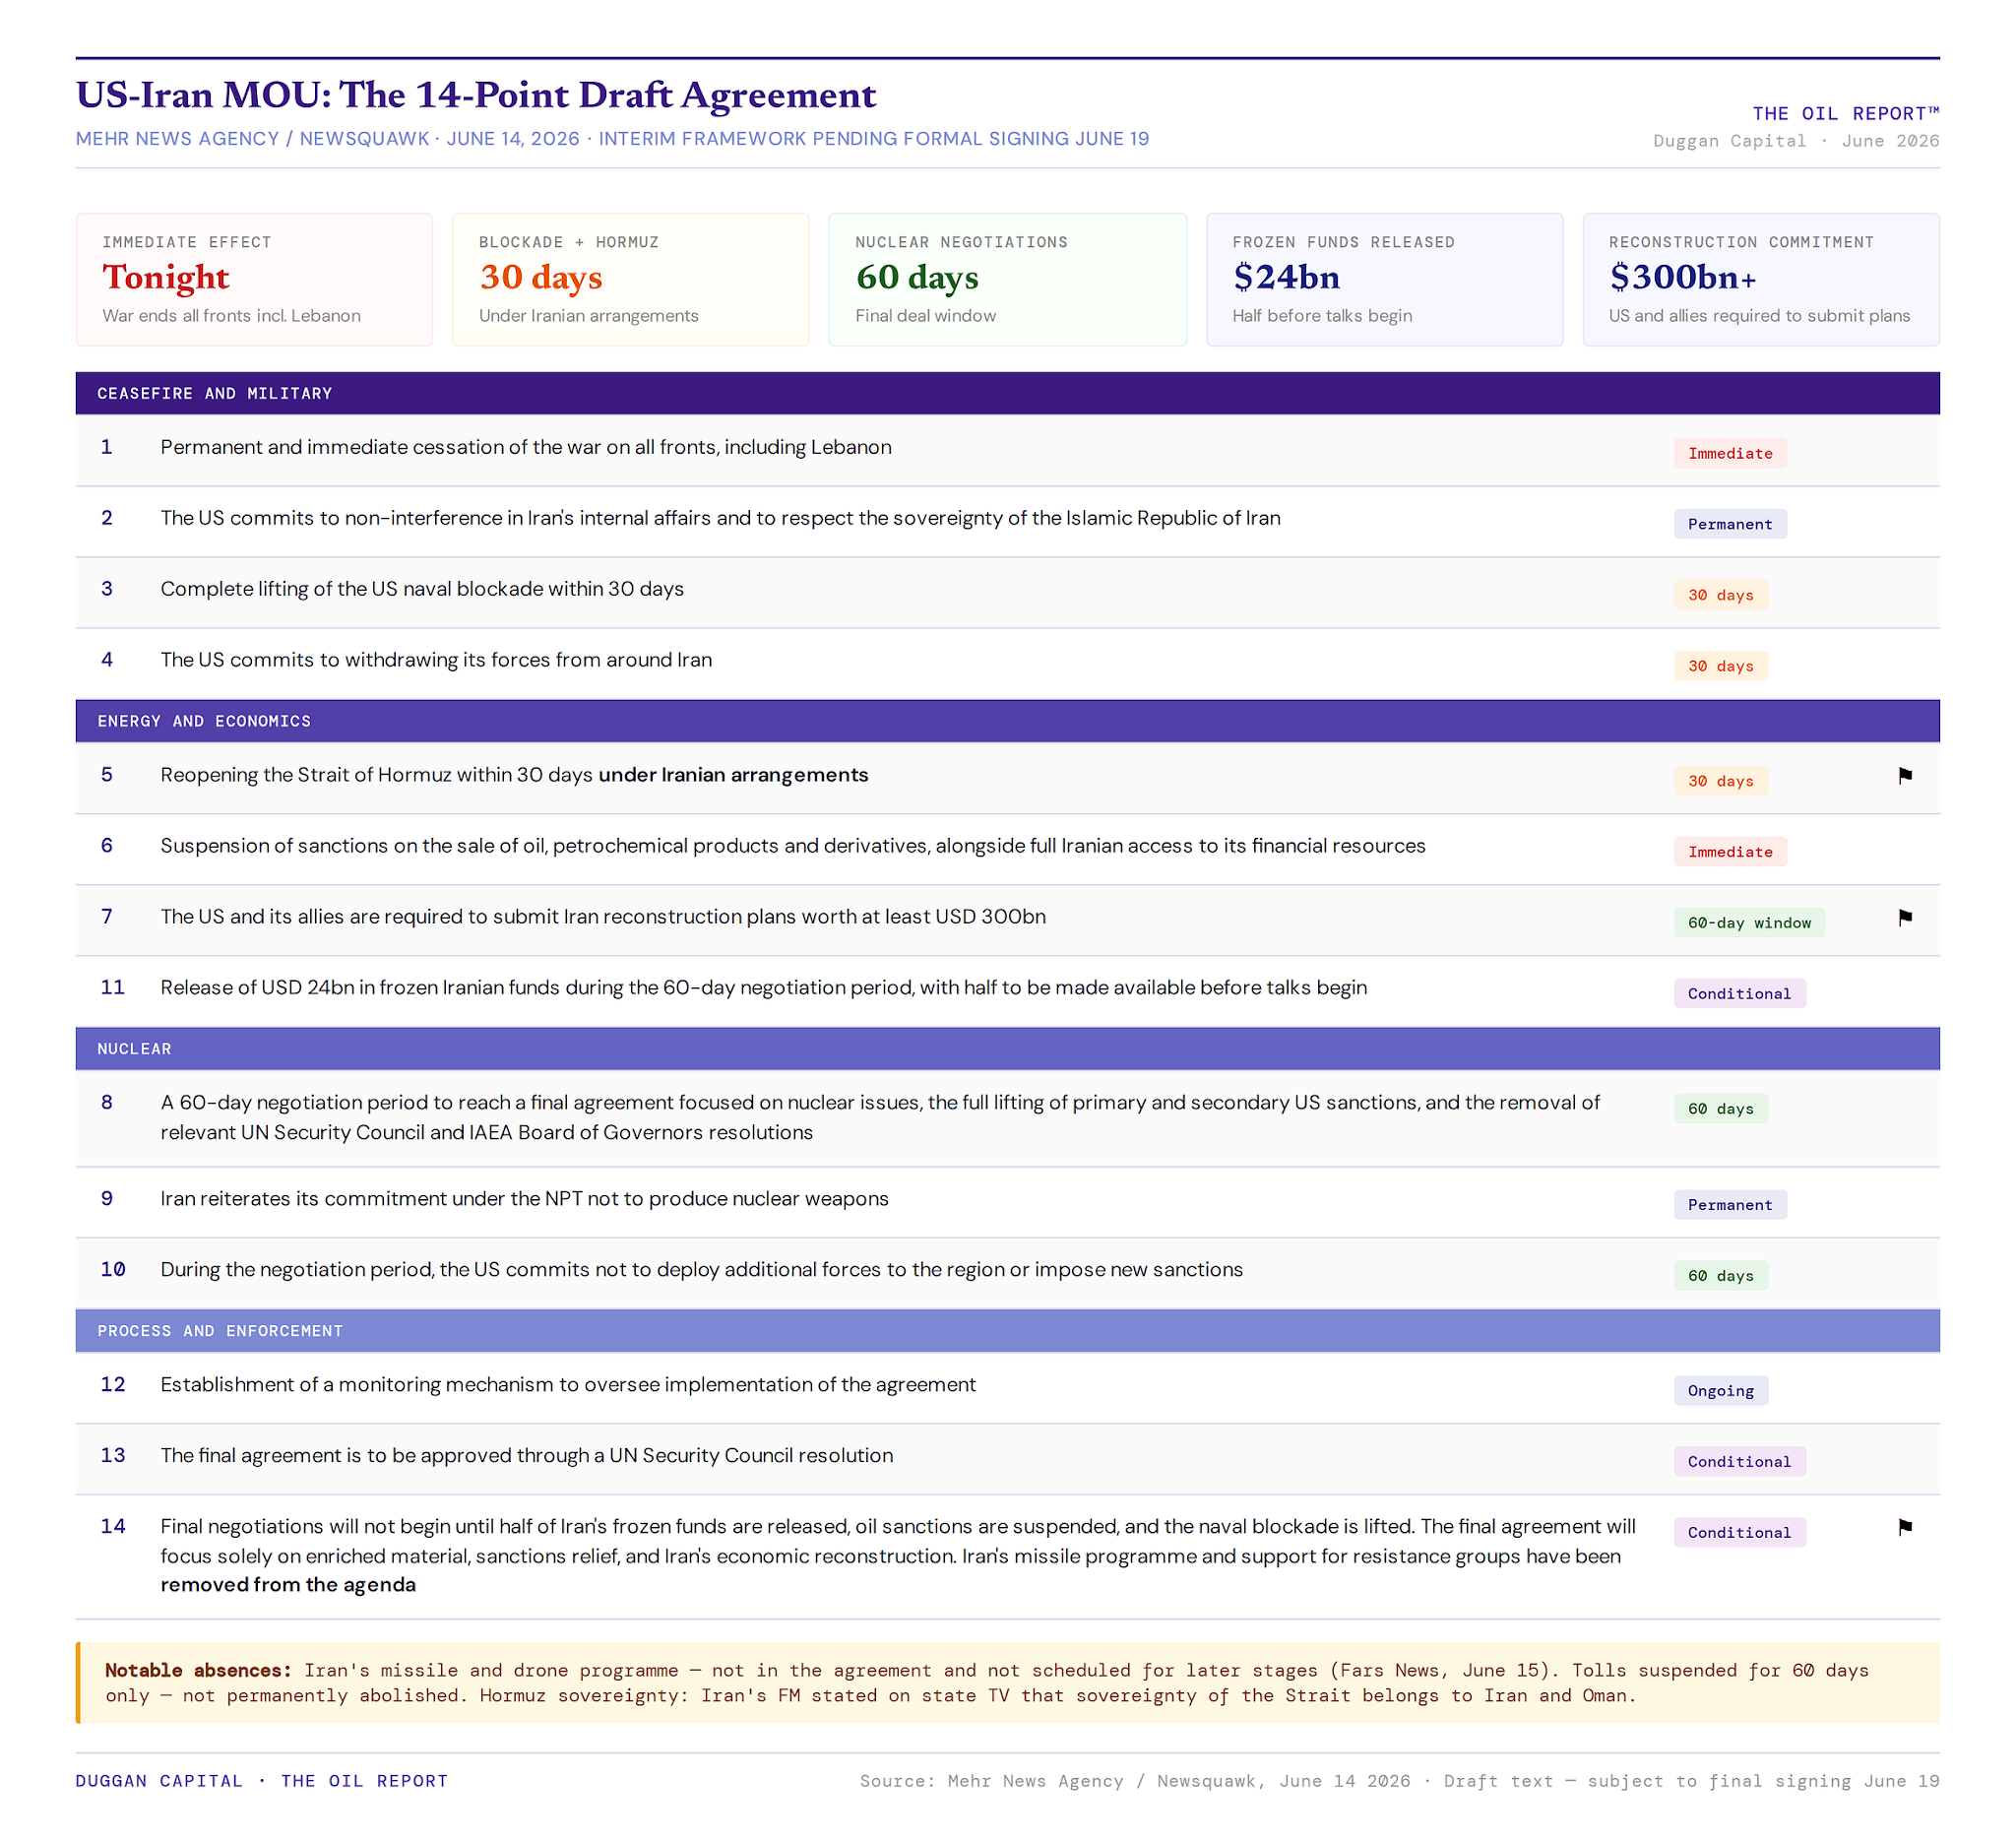
The 14-point draft published by Mehr News Agency sets out the terms. The war ends immediately and permanently on all fronts including Lebanon, however Israel are not recognising this deal MOU. The US naval blockade lifts within 30 days. The Strait of Hormuz reopens within 30 days – under Iranian arrangements. Oil and petrochemical sanctions are suspended. $24bn in frozen Iranian funds are released during the 60-day window, half before talks begin. The US and its allies are required to submit reconstruction plans for Iran worth at least $300bn. A monitoring mechanism is established. The final agreement requires UN Security Council approval.
The 60-day negotiation period that follows will focus on Iran’s nuclear enrichment program, the disposal of highly enriched uranium, and the full lifting of primary and secondary sanctions. Iran’s missile and drone program is not in the agreement and is not scheduled to be raised in later stages.
The Problem Is Not Fixed
Noted from a Kplr call last week, due to workarounds since the start of the war, we are actually in a surplus of about 1.5million barrels worldwide. The major influence on this is that Chinese refiners. The 5.6mb/d run cuts bar represents crude demand that simply disappeared because refiners stepped back. This suppressed refining will come back to market as demand now. This will provide a floor to how far front prices can slip. China will want to get back to normal refinery runs as will the rest of the world. The tracking of refiners global demand will be one to watch as we emerge out of the war.
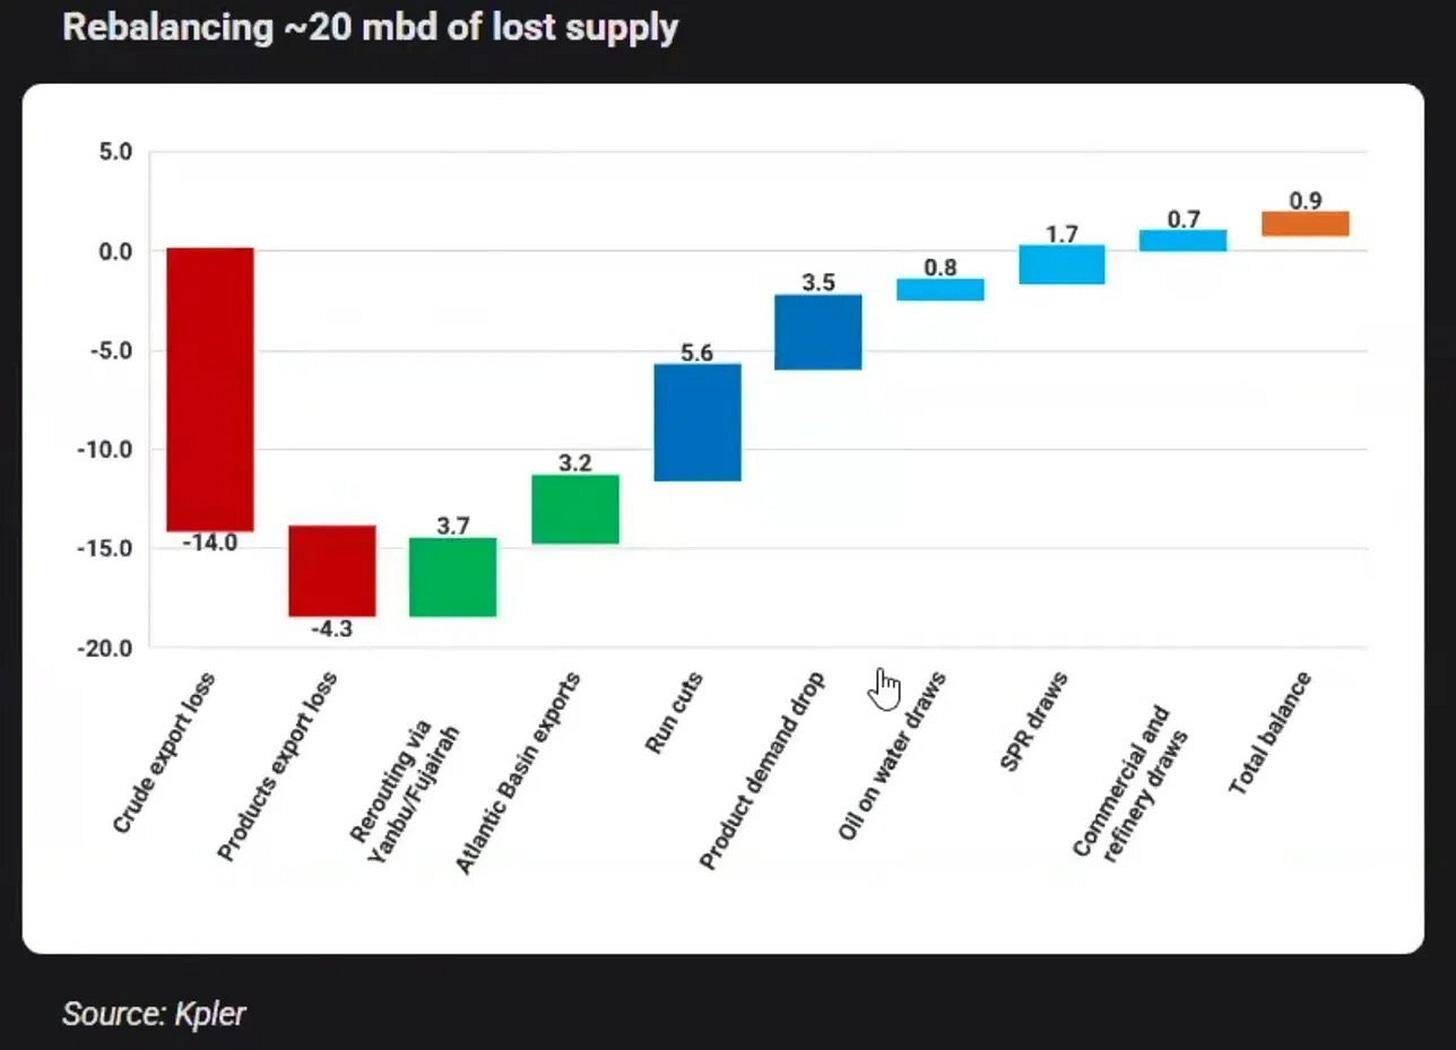
Axios confirmed it directly: fully reopening the strait may not happen immediately. Mine-clearing, infrastructure repair and guaranteeing security will take time before a full return to pre-war shipping volumes. Trump said as much on Truth Social – the strait opens upon signing, for purposes of mine removal. That is not a clean open. That is a controlled, sequenced process under Iranian supervision, on a 30-day timeline that has not yet started.
War risk insurance premiums do not reprice because a document was signed in Switzerland. The VLCC fleet that has been sitting idle off the Gulf of Oman does not immediately resume normal scheduling. Kpler’s shipping analysts put it plainly in their May webinar – confidence does not return with a ceasefire, it returns with time and incident-free transits. The market learned that in the Red Sea. It will learn it again here.
Production restart runs on its clock. Kpler estimated five months minimum to restore pre-war Gulf production levels even under an optimistic reopening scenario. ADNOC’s CEO Sultan Al Jaber put the realistic normalisation timeline at mid-2027. A billion barrels of cumulative production loss does not reverse in a quarter.
Qatar’s Ras Laffan sustained damage to two of fourteen LNG trains during the conflict. The repair timeline is measured in years. The MOU does not fix infrastructure.
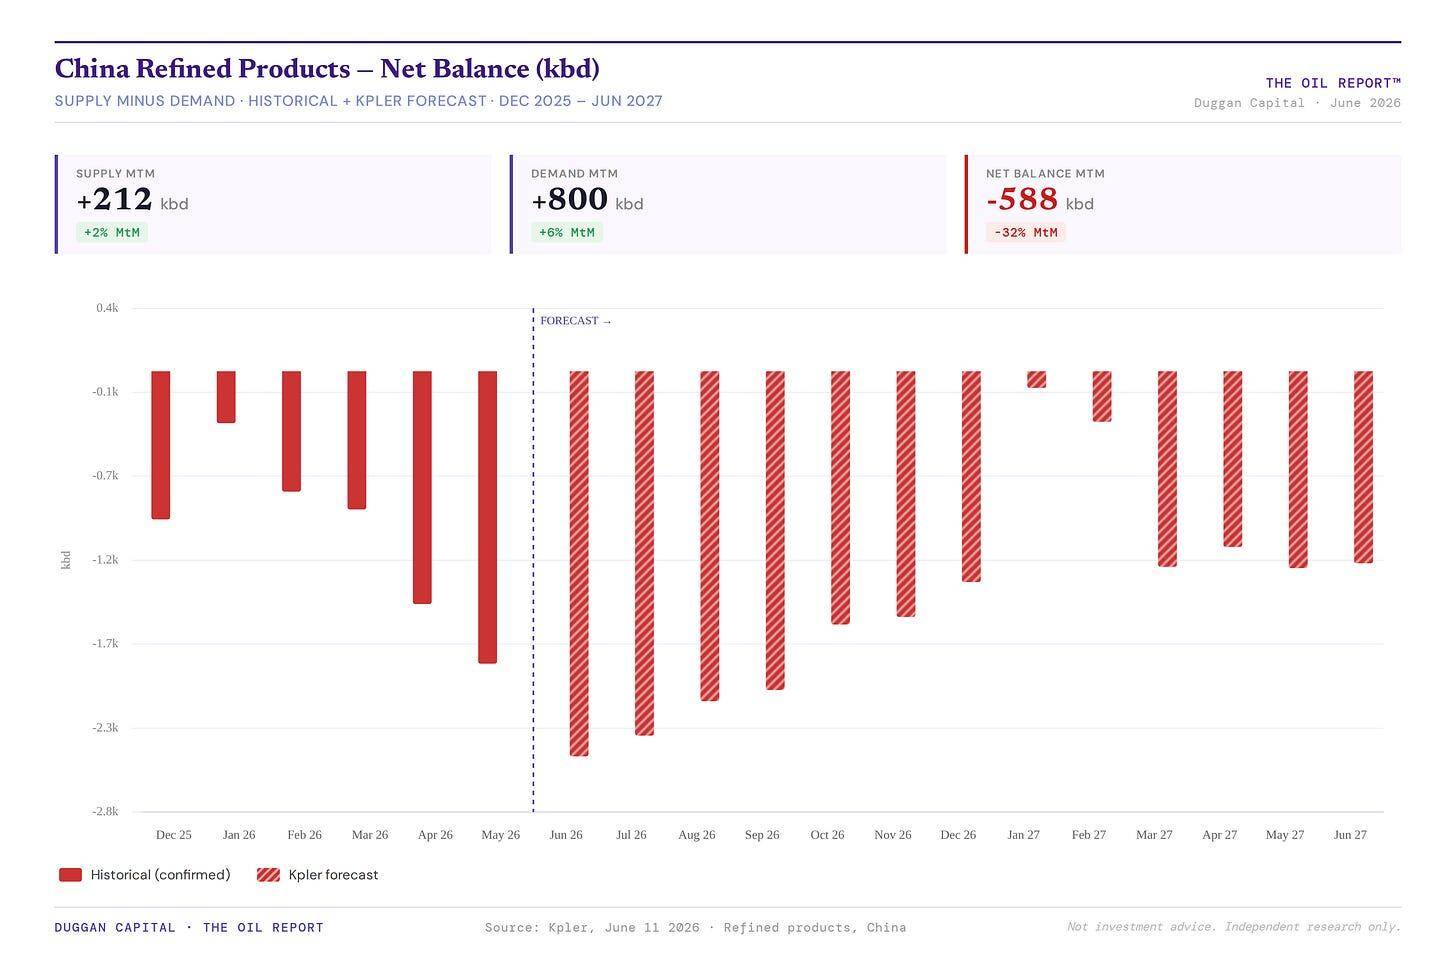
China’s refined product deficit is running at -1,858 kbd in May and Kpler’s forecast has it deepening to -2,447 kbd in June before a gradual recovery through the second half of 2026. That recovery is a function of crude availability, refinery restart, and inventory rebuild – none of which respond to a signing ceremony. The product market does not normalise until late 2026 at the earliest.
The 60-day negotiation window carries its own risks. The Lebanon front is not closed – Israeli Defence Minister Katz has told Trump directly that Israel opposes IDF withdrawal. Iran’s armed forces were in operational preparation for a strike on Israel on signing day itself, held back by US, Qatari and Pakistani mediators. One incident on that front reopens the military dimension before the 60 days are up. Iran was explicit: if the interim deal is not implemented, there will be no nuclear talks. The leverage is retained, not surrendered.
The Net Net
The bypass infrastructure continues. UAE second pipeline operational 2027. Basra-Haditha minimum 2028. The decisions that drove those projects were validated not reversed by the MOU. Qatar’s LNG trains remain damaged. Production restart runs on Al Jaber’s mid-2027 clock not Trump’s Truth Social timeline.
The 60-day window opens Friday. Netanyahu is not on board. Lebanon is not closed. Iran has retained its leverage explicitly and in writing. The market sold four percent on the announcement. What it has not yet priced is what happens if the 60 days produce nothing.
That is where we are.
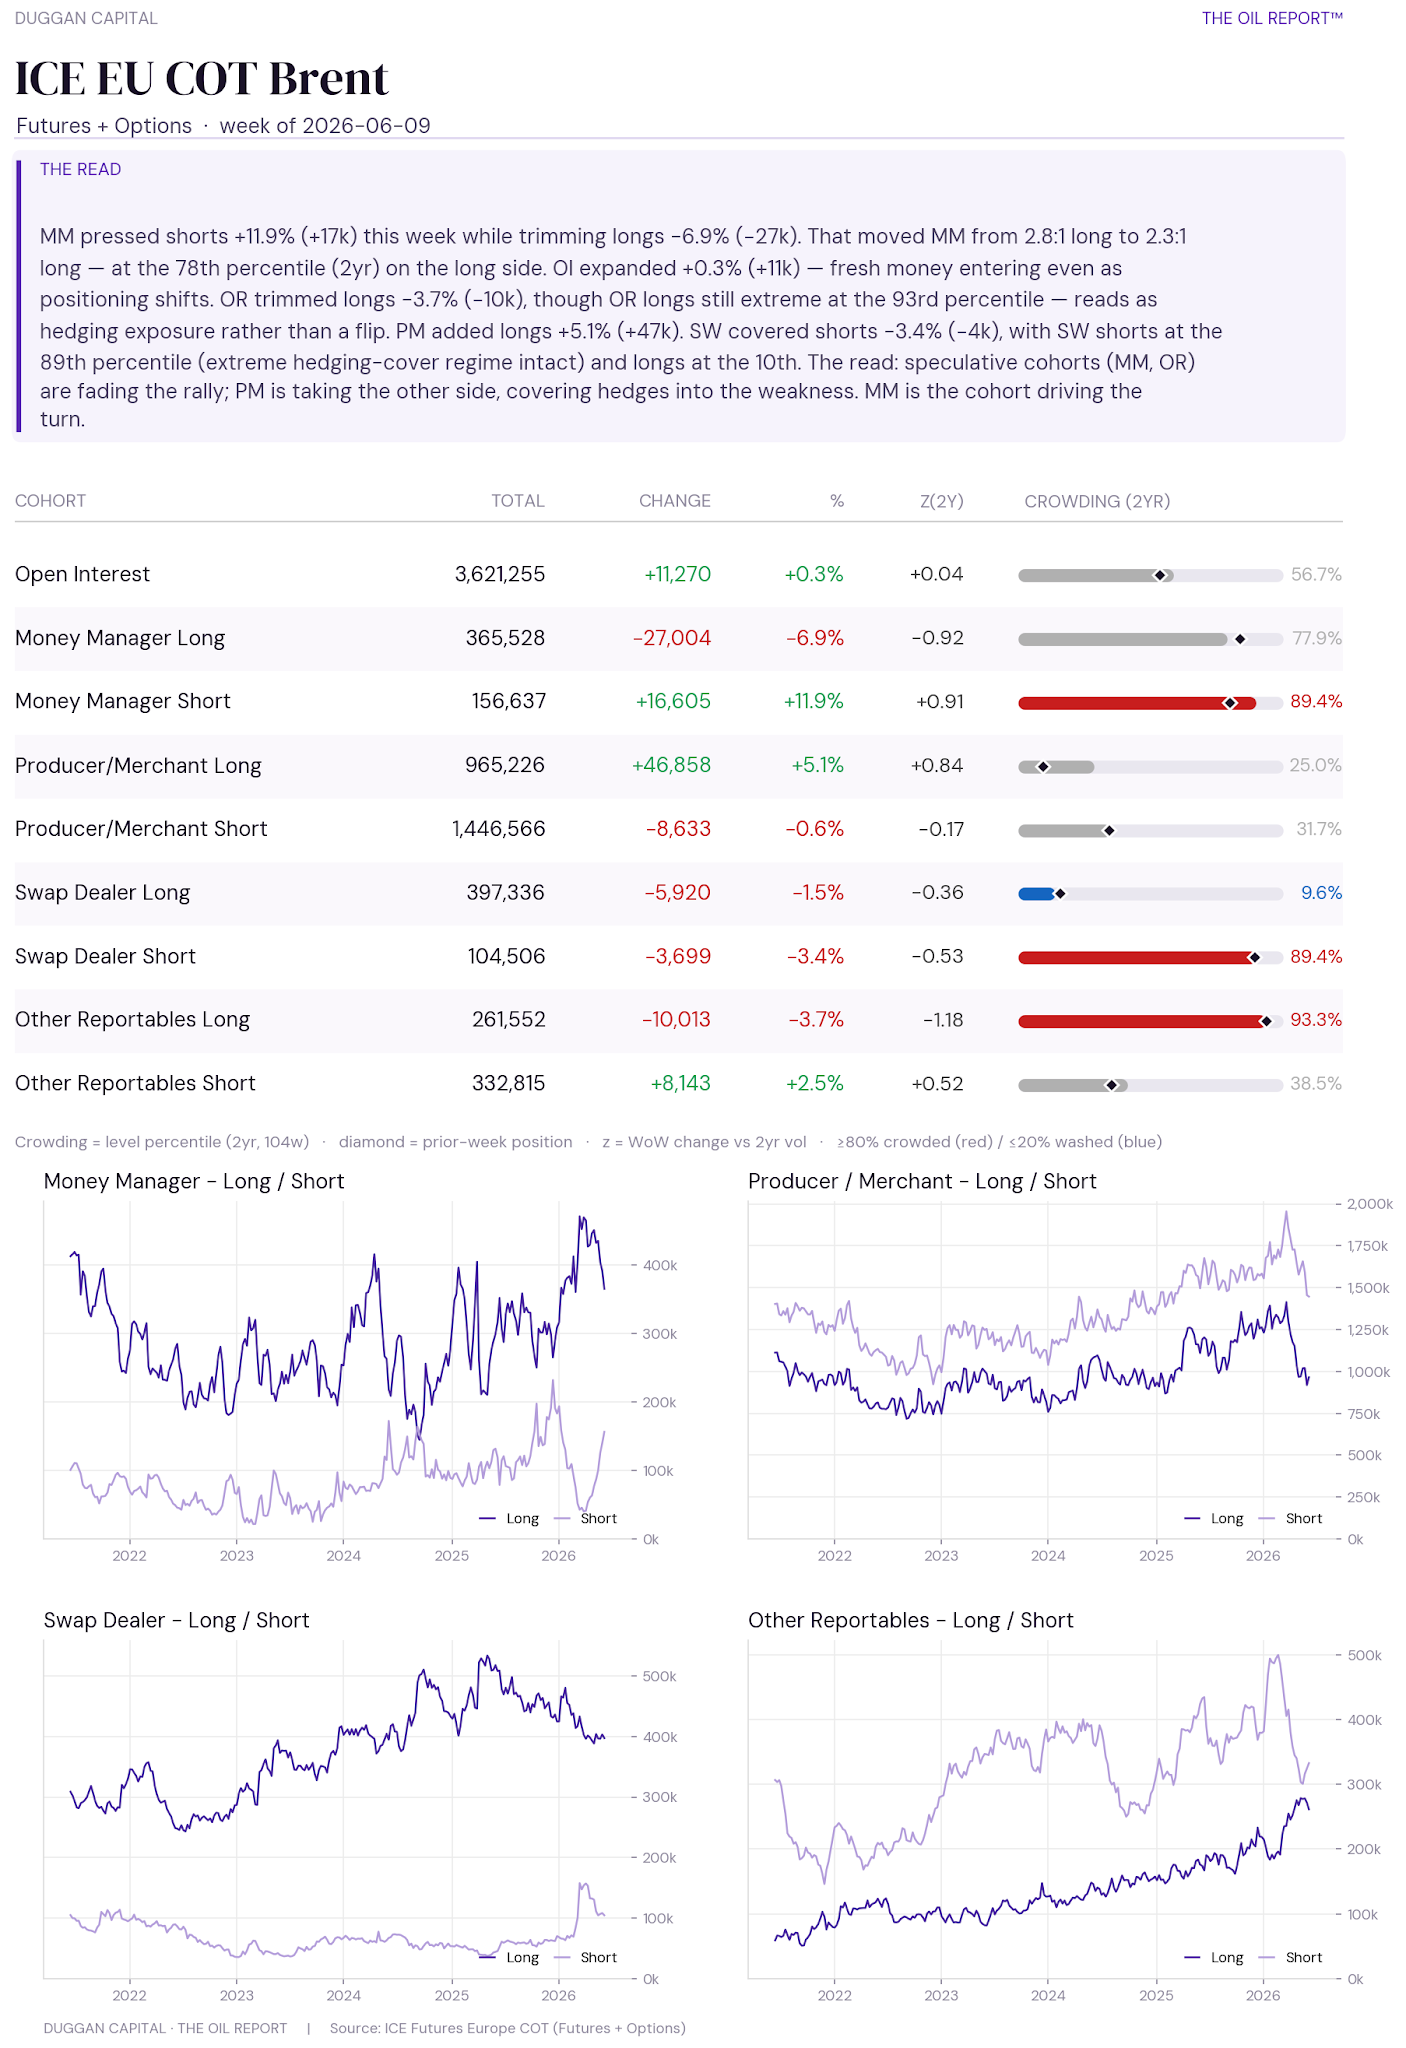
Commitment Of Traders Report
What’s the Next Move?
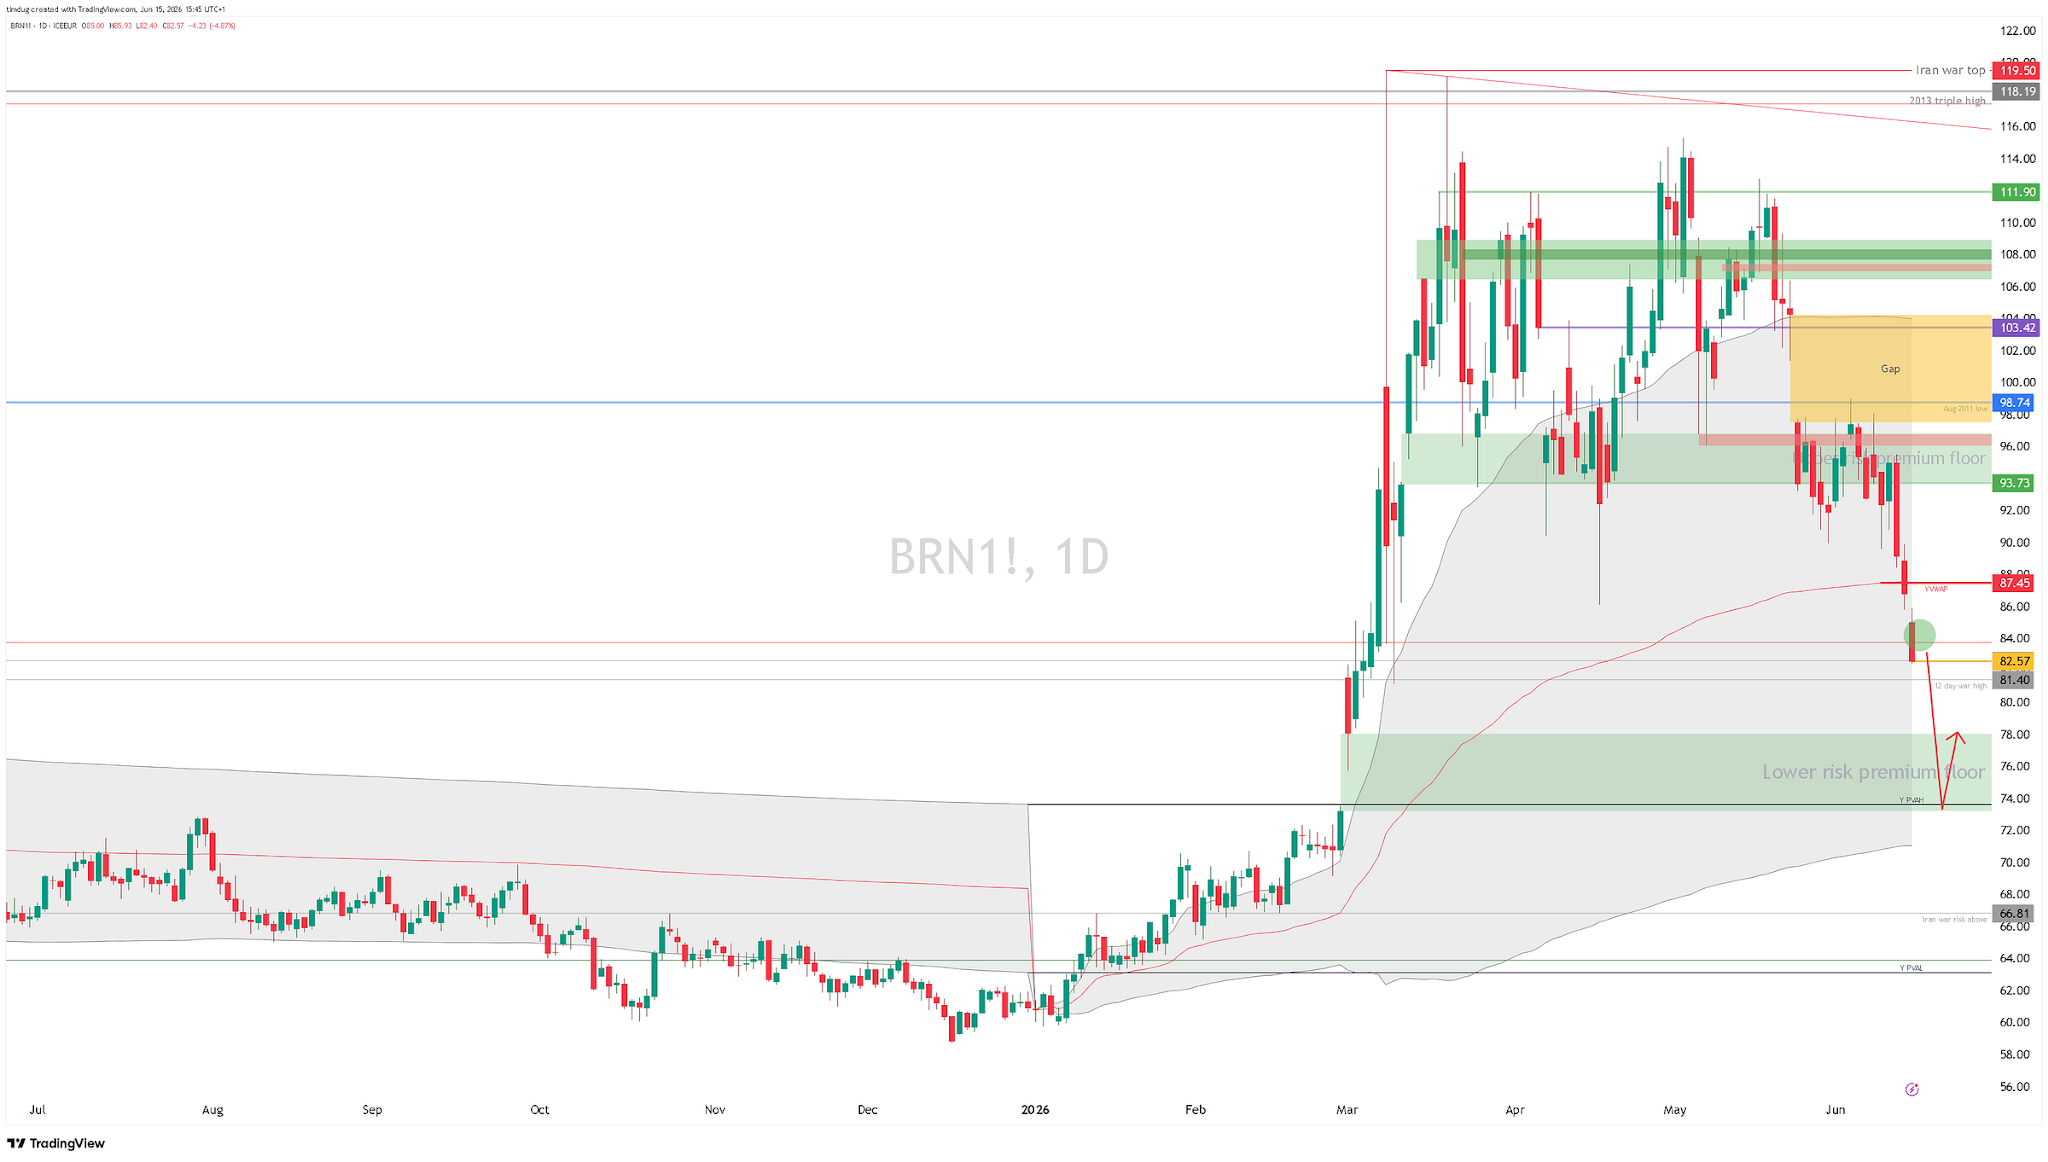
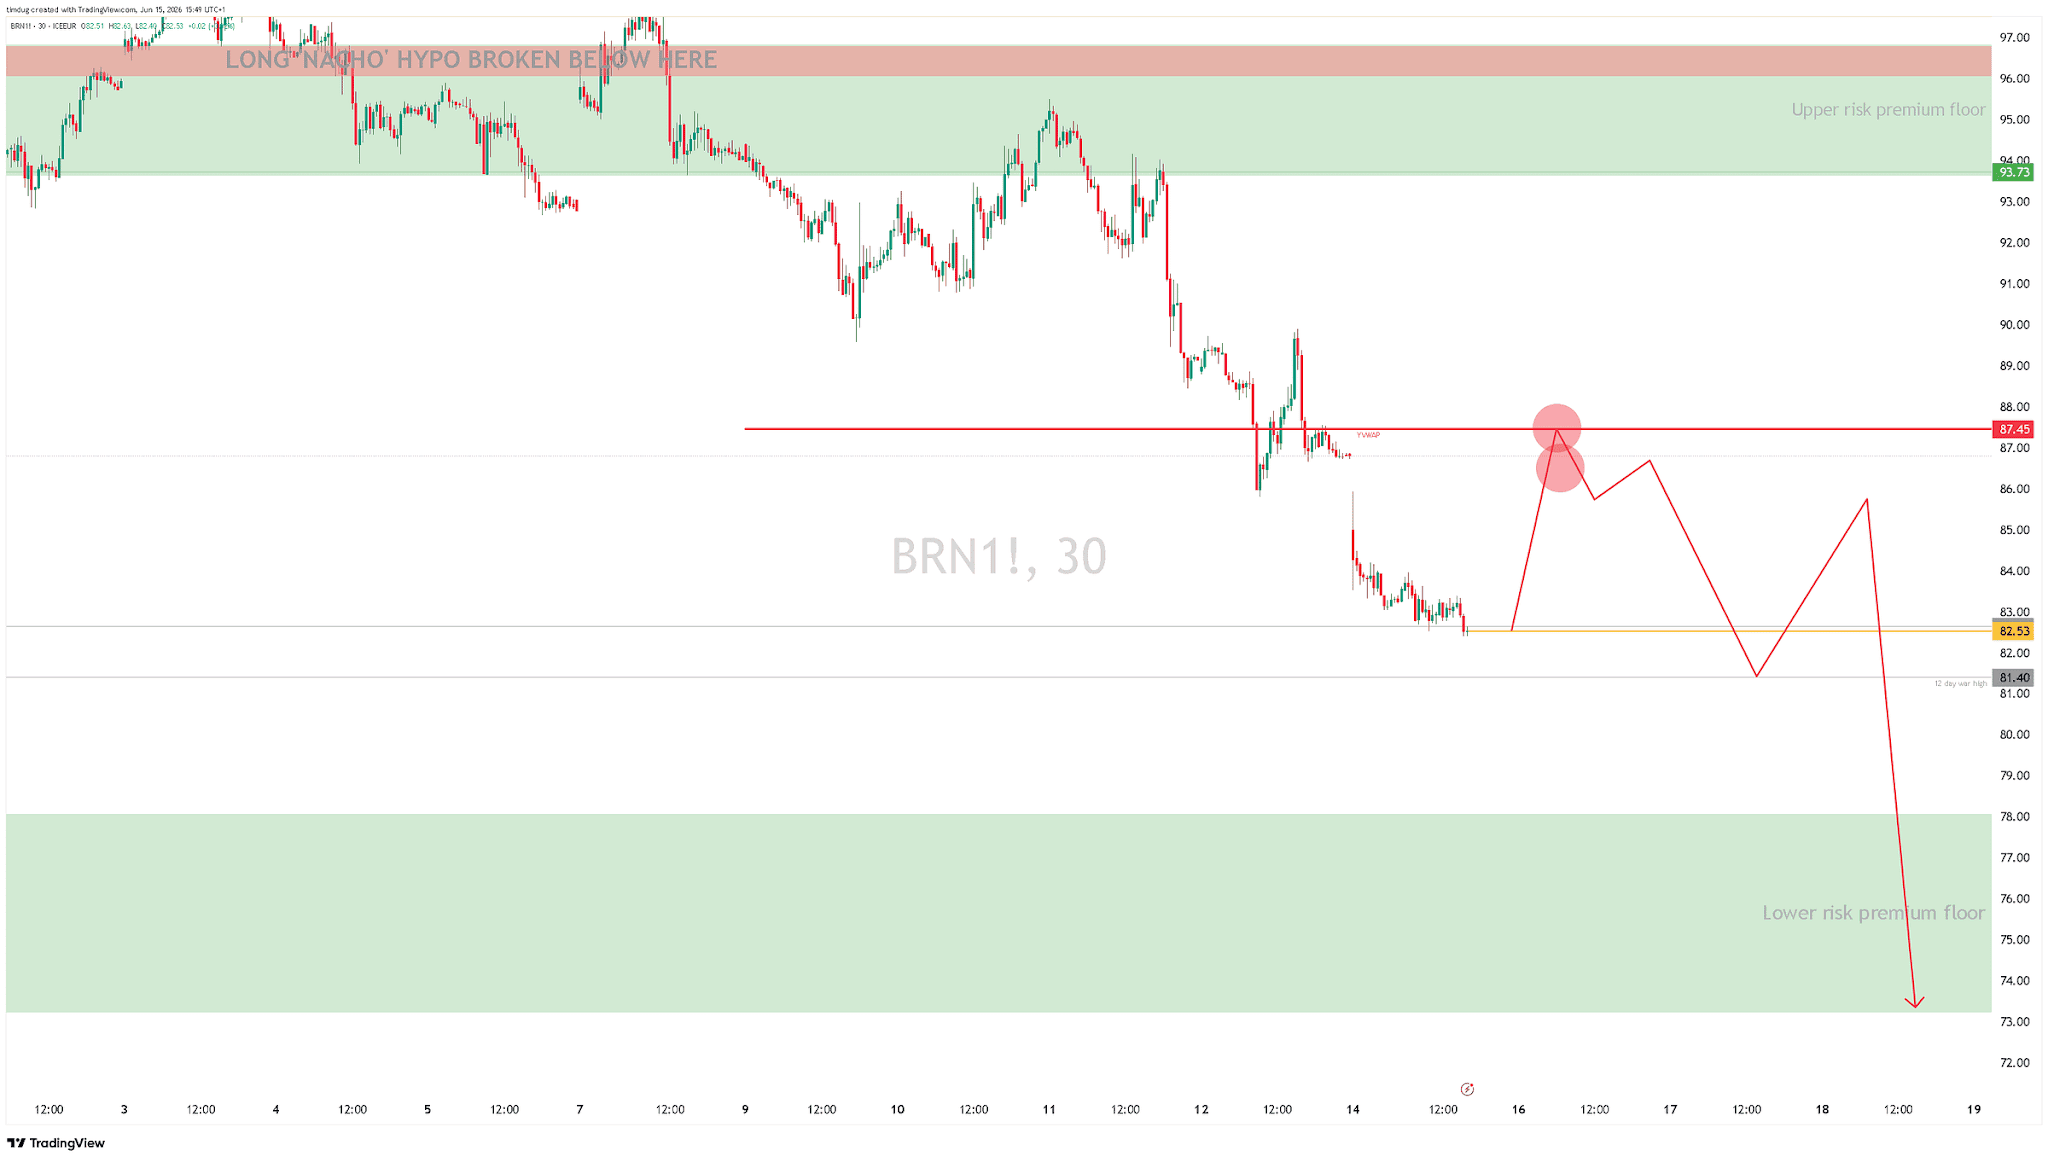
Okay, now down to the straight talking. Here below is the chart I posted May 31st in ‘Don’t fight the SPR’. All these areas on downside have traded now APART from the 12 day war top $81.40. We are moments away from trading it.
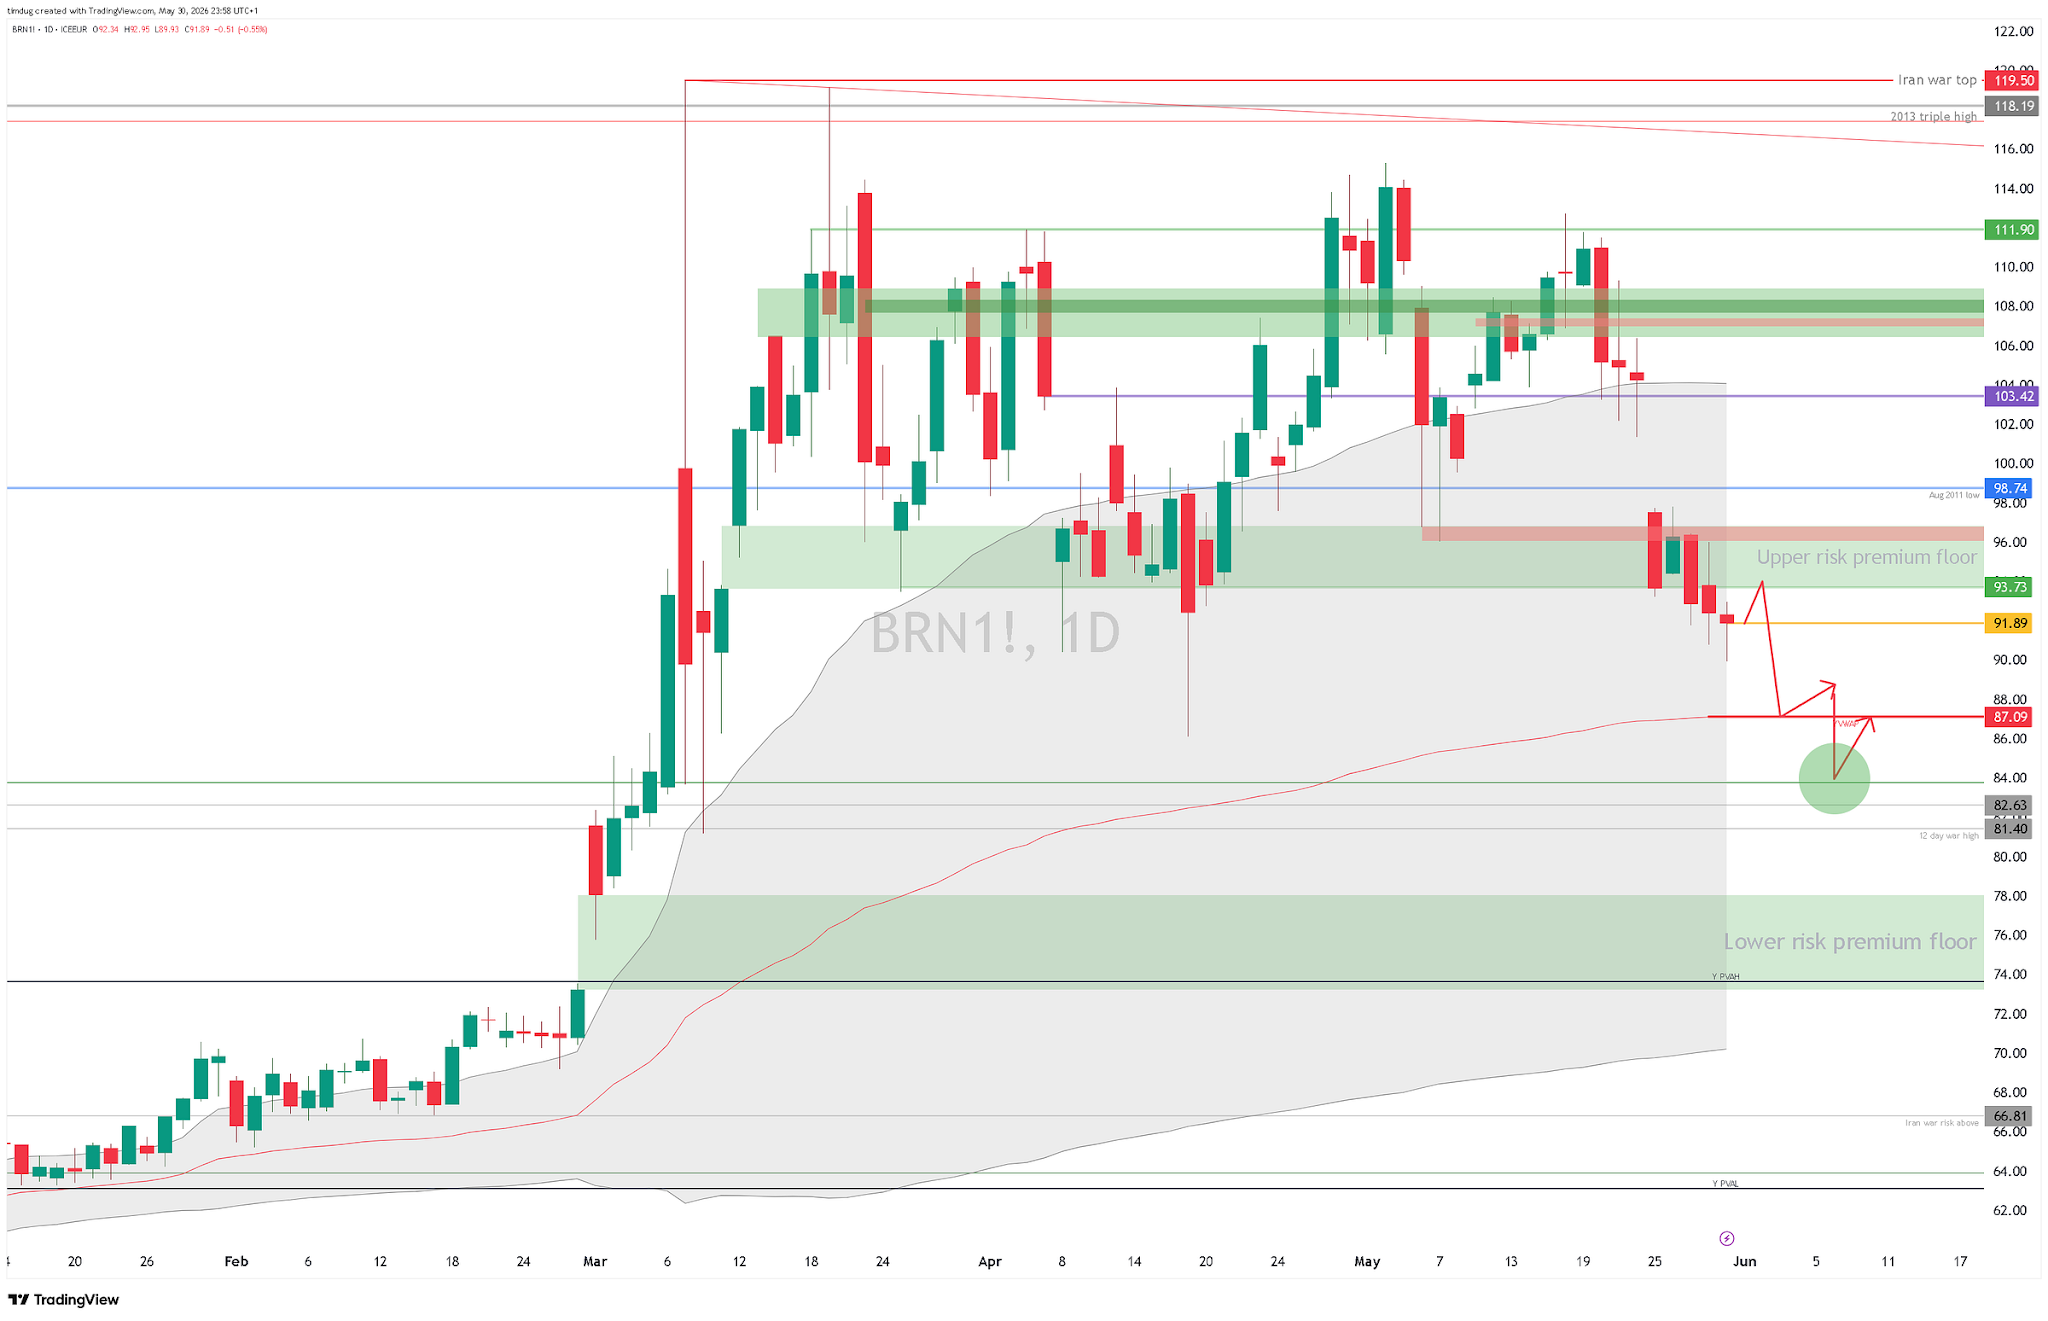
We must now reverse 120% approximately of the risk premium since the late Feb move up. The reason for the 120% is that China has stepped off the import market as buyer to the tune of about 7mb/d. This means that we not only reverse the move, but add in the softness of 7mb/d less buying. This will not return until we see it on the flow data from Kplr/Vortexa. I would rather not guess at it.