


Every election cycle brings a fresh wave of political debate, but for investors, the more important question is whether elections leave a measurable footprint on financial markets. I examined every U.S. mid-term election cycle since 1970 to answer a simple question: Does history provide any clues as to how the S&P 500 might move in the months leading up to, and following, the next U.S. mid-term elections?
The results gave food for thought. The empirical evidence points toward there being two distinct phases investors may consider preparing for: an initial period of consolidation before the election, followed by a more constructive backdrop once political uncertainty begins to fade.
One Of The Strongest Starts On Record
The S&P 500 is currently trading at 7,458 points, representing one of the strongest starts to the six-month pre-election period seen in the past 56 years. Looking back across the previous 14 mid-term election cycles since 1970, the current advance ranks as the fifth strongest opening during the first two-and-a-half months leading into the election. Only four years produced a stronger start:
- 1990: 7,678 points
- 1998: 7,647 points
- 2014: 7,589 points
- 2018: 7,580 points
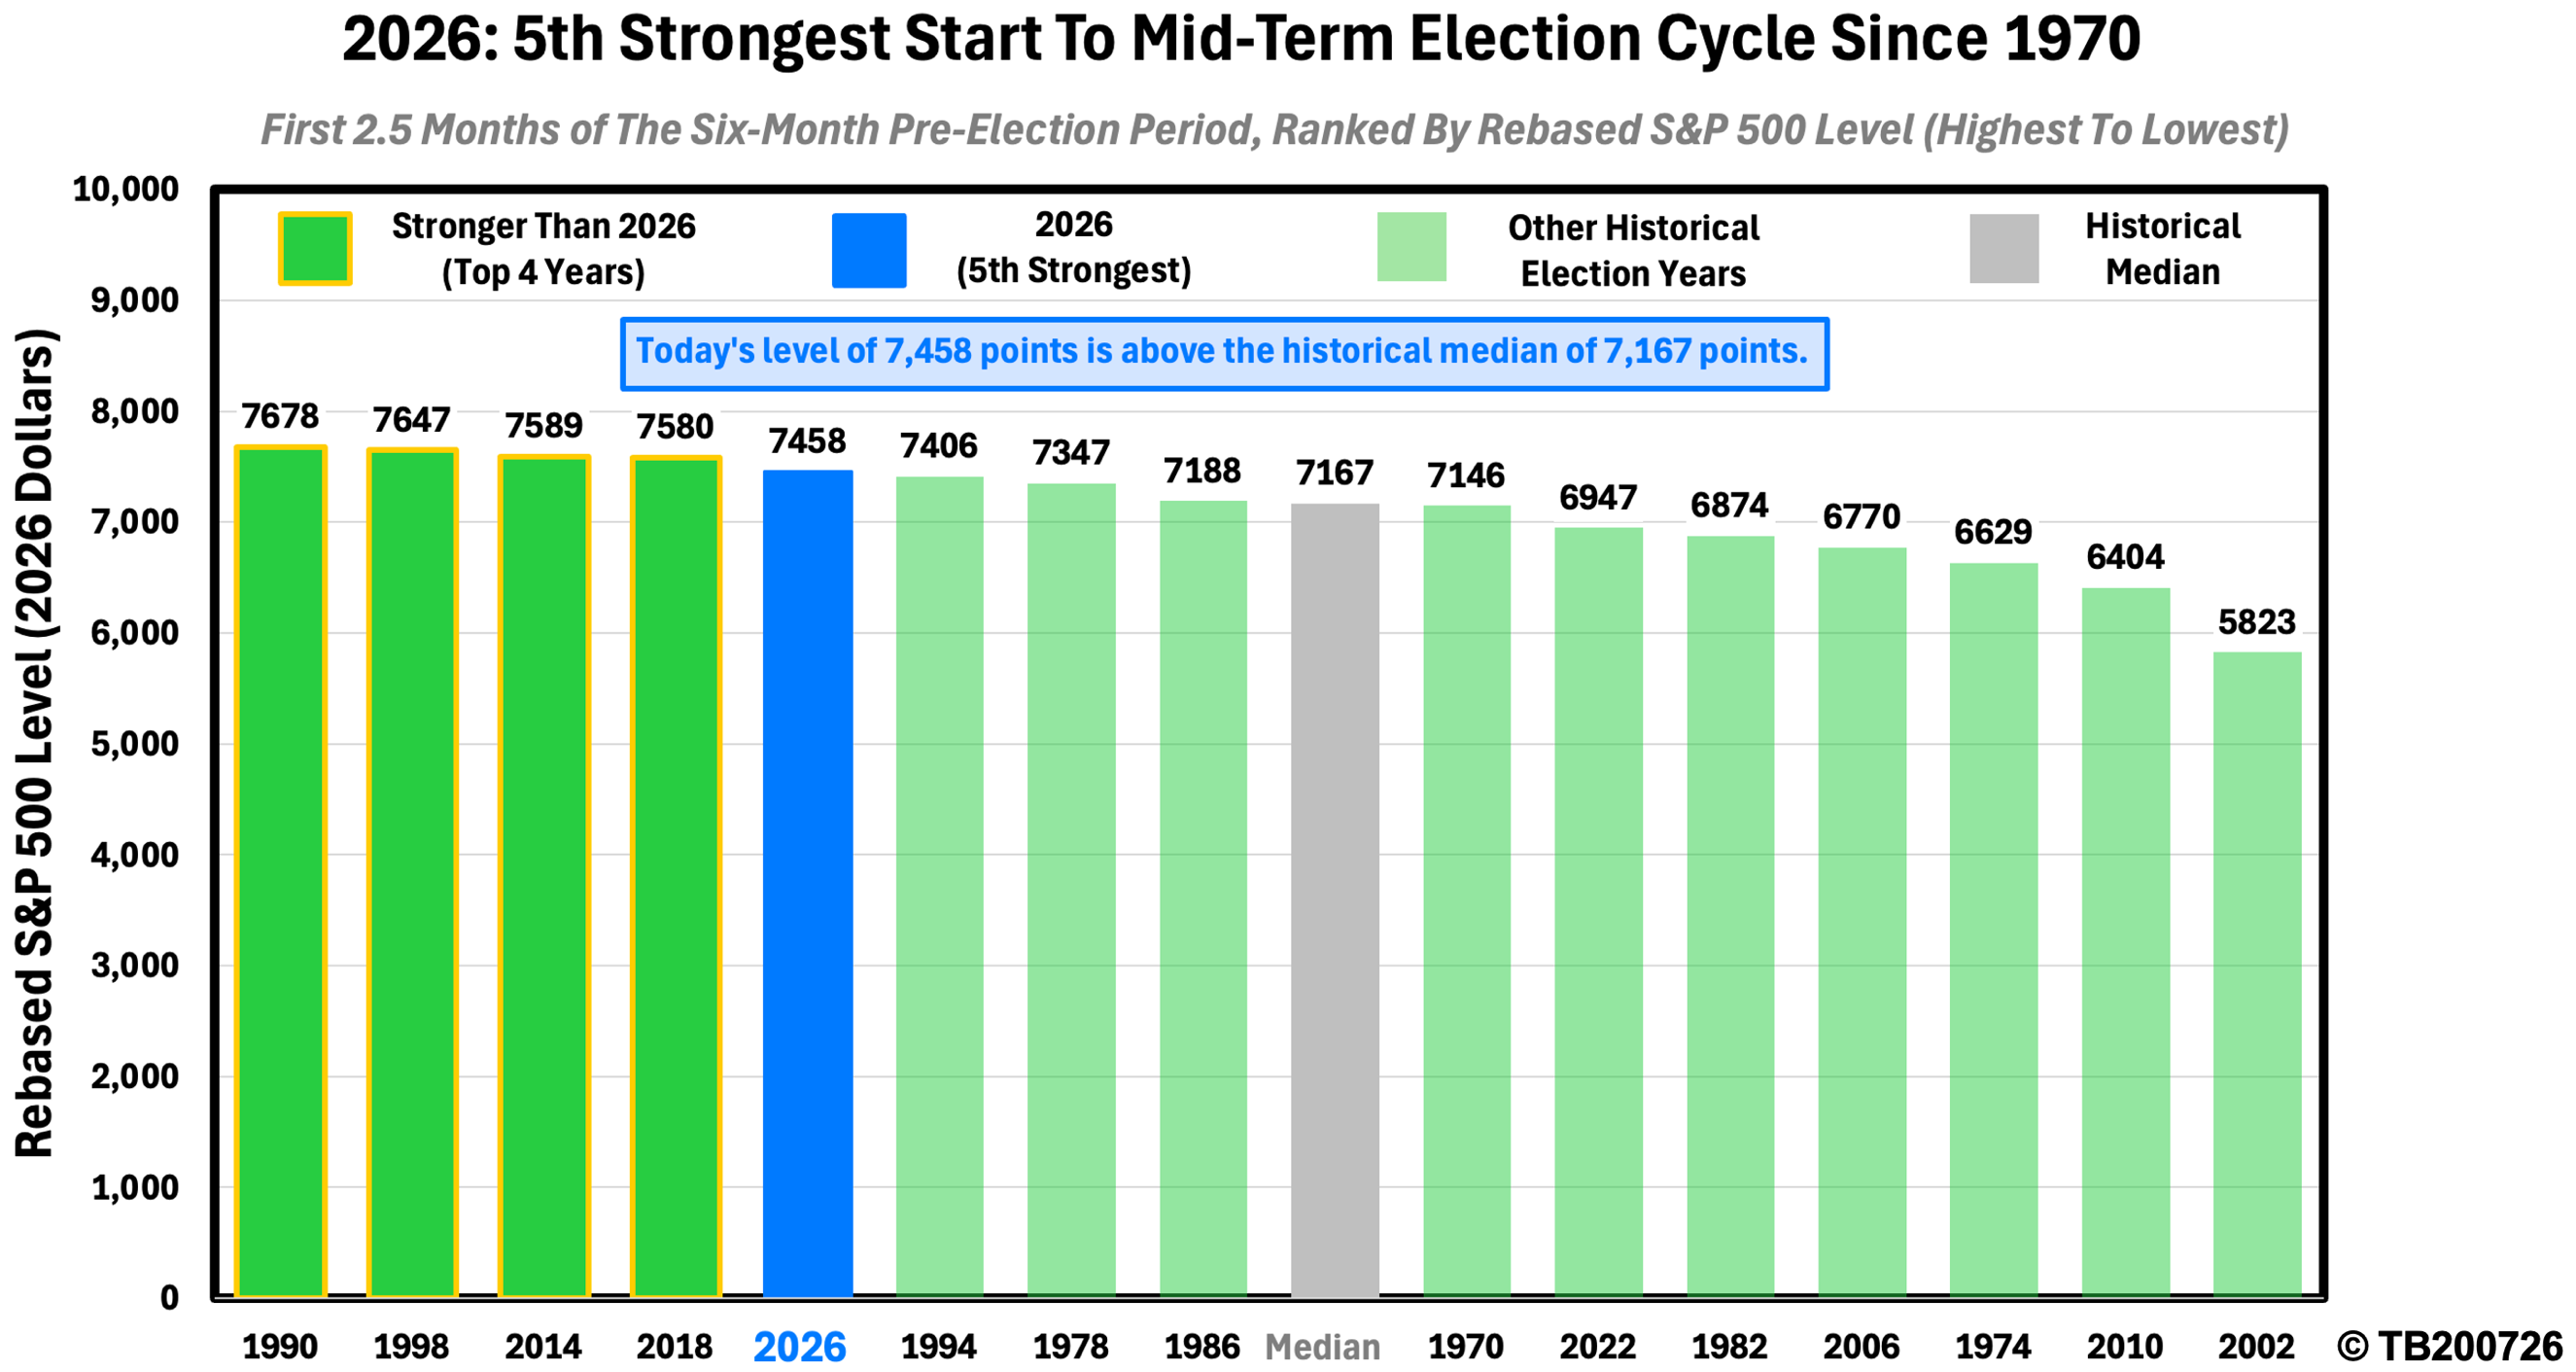
By comparison, the historical median level across all previous cycles stands at 7,167 points, meaning today’s market is trading comfortably above what has typically been observed at this stage in the cycle.
Could Consolidation Be Ahead?
The speed of the recent advance has been remarkable. The S&P 500 gained more than 16% during April and May, pushing to fresh all-time highs at a pace rarely witnessed. While such momentum is undeniably impressive, markets rarely move in straight lines indefinitely. Strong rallies are often followed by periods of consolidation as investors digest gains, rebalance portfolios and reassess valuations.
S&P 500 Price Forecast
Every new S&P 500 analysis as it publishes, today's technical signal and key levels, live price — on one page.
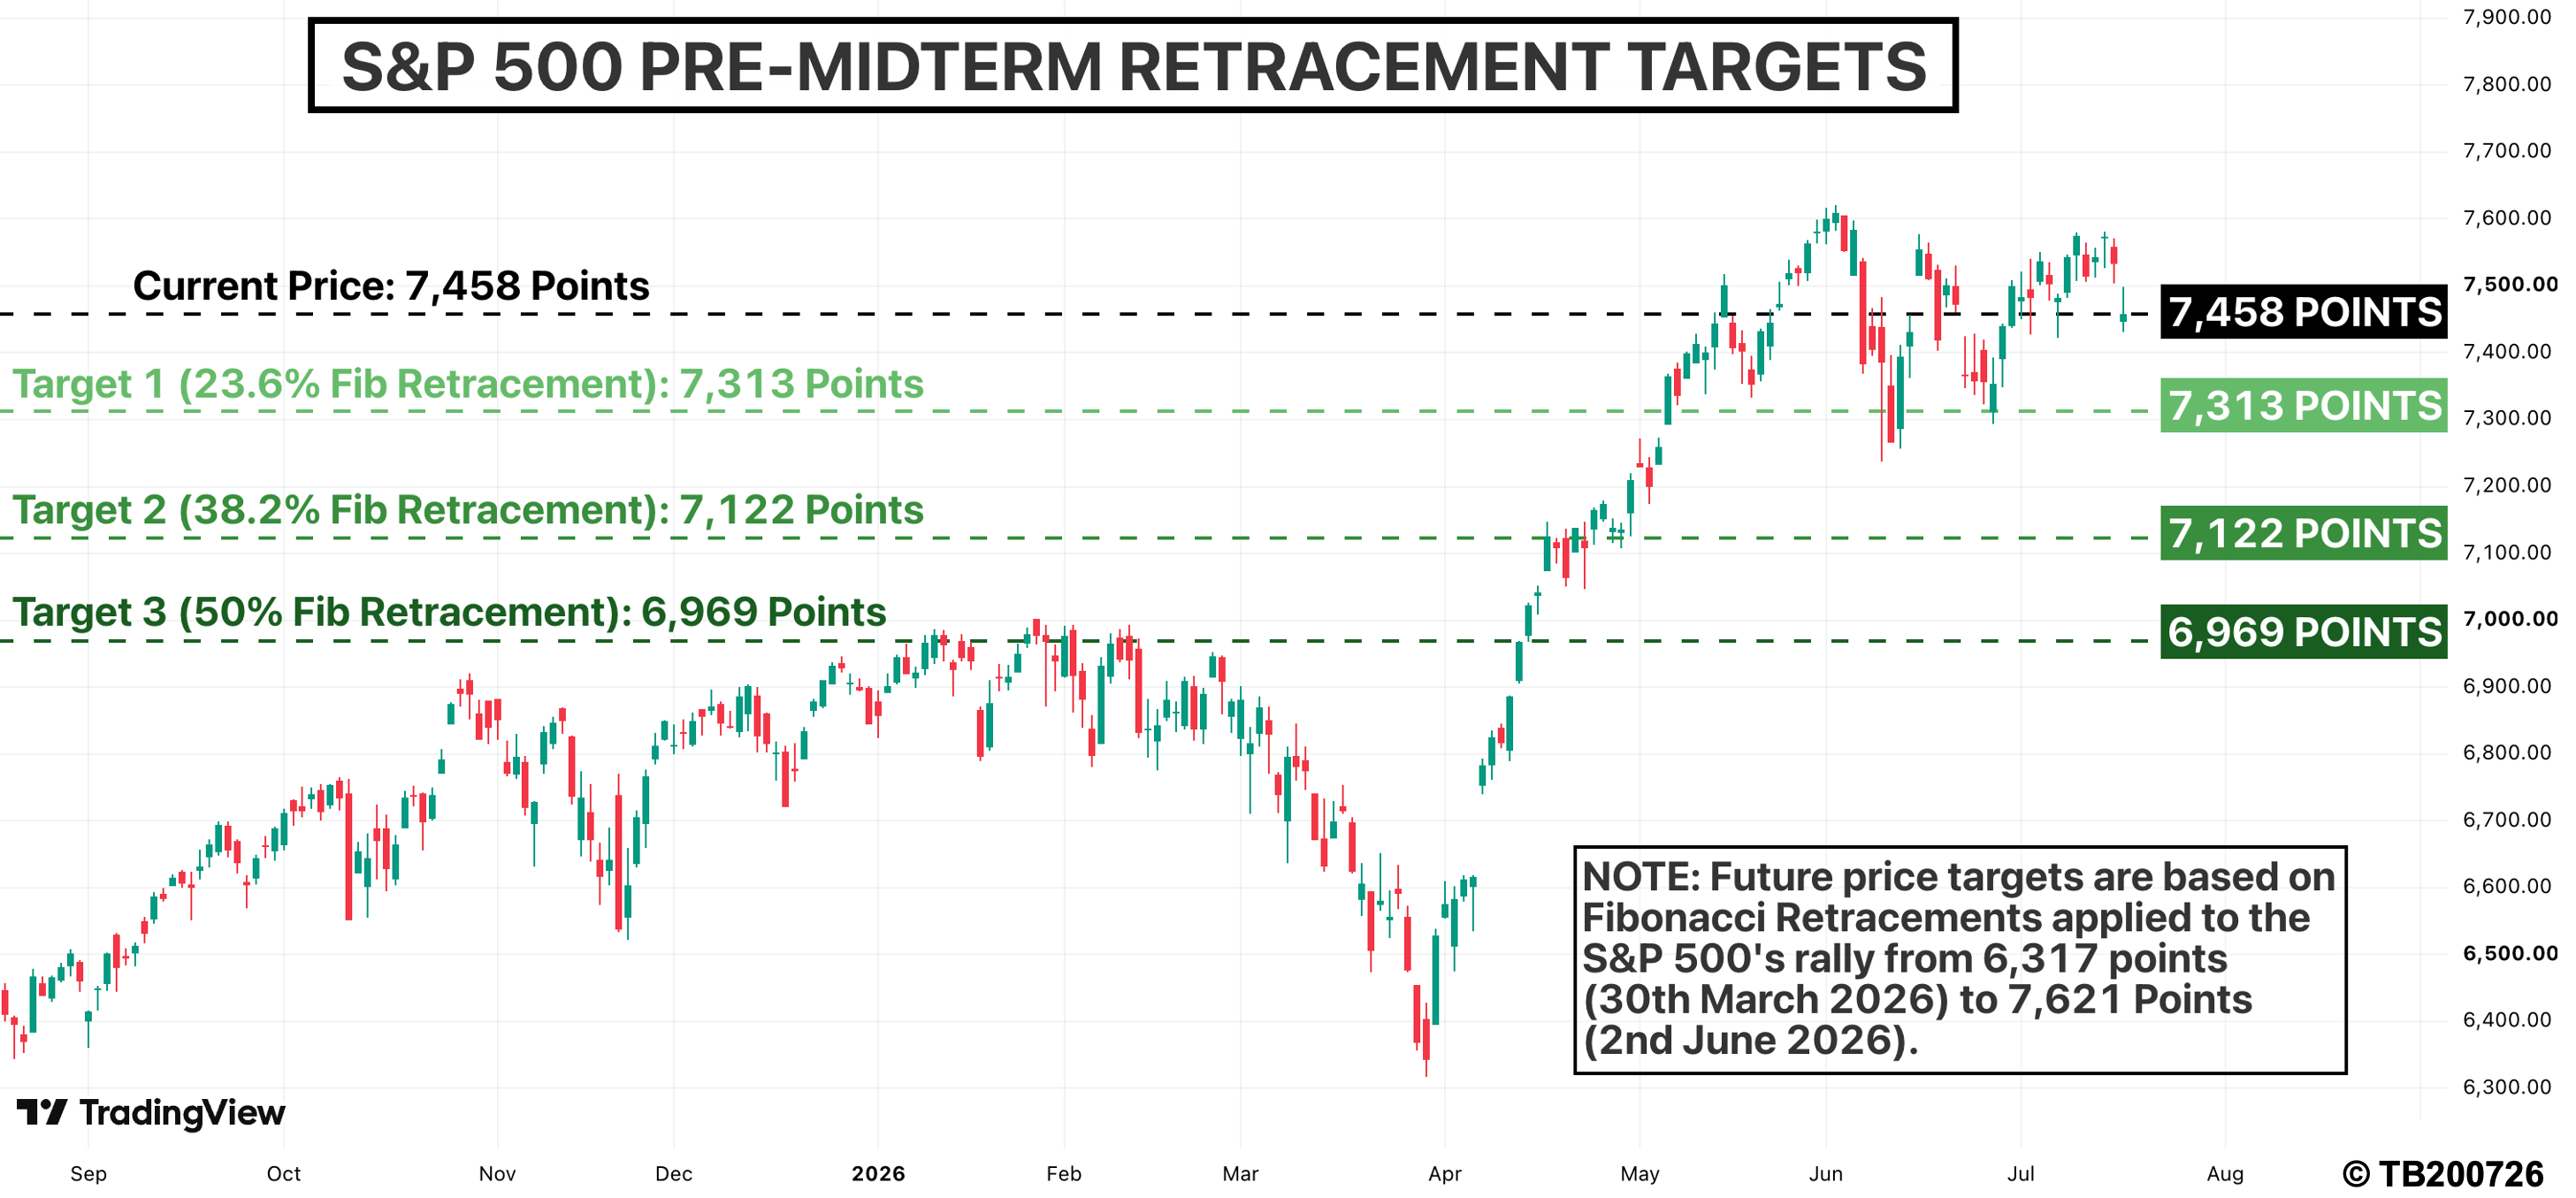
See all S&P 500 forecastsLooking across previous mid-term election cycles, one recurring theme has been that markets have frequently experienced a period of weakness before the election itself. If this pattern were to repeat, the current setup could allow for a pullback of 4%, bringing the index back toward the psychologically important 7,000-point level.
While predicting precise price targets is impossible, that position carries important technical significance. Previous breakout zones often become future support levels, with markets revisiting former resistance before resuming their broader advance. Such behaviour helps establish a stronger foundation for the next leg higher while shaking out speculative positioning accumulated during rapid rallies.
Why The Mid-Terms Matter For Markets
Financial markets rarely respond directly to political rhetoric. Instead, investors focus on how election outcomes may influence future economic policy. Mid-term elections determine control of Congress, shaping a President’s ability to implement legislation over the remaining two years of an administration.
With Republicans currently controlling both the House of Representatives and the Senate, President Donald Trump has greater flexibility to pursue his legislative agenda. Should either chamber change hands, though, the balance of power could shift considerably, increasing the likelihood of legislative gridlock.
Markets generally dislike uncertainty. In the months leading up to elections, investors often delay major allocation decisions until greater political clarity emerges, contributing to higher volatility during the pre-election period.
Markets Influence More Than Portfolios
The significance of the stock market extends well beyond institutional investors. According to recent estimates, 60% of U.S. adults own stocks, either directly or indirectly through retirement accounts, pension funds or mutual funds. As a result, equity market performance can influence:
- Household wealth.
- Consumer confidence.
- Retirement savings.
- Spending behaviour.
When portfolios rise, consumers often feel wealthier and become more willing to spend. Conversely, sustained market weakness can weigh on confidence even if broader economic conditions remain relatively stable. This relationship helps explain why financial markets frequently become an important backdrop through election periods.
The Historical Pattern After Mid-Terms
Perhaps the most interesting finding from the historical analysis comes after the election itself. Across the previous 14 mid-term election cycles, and over a six month period, the S&P 500 moved higher on 11 occasions. The historical median path suggests:
- Around the time of the mid-term election: 7,316 points
- Six months after the election: 8,076 points
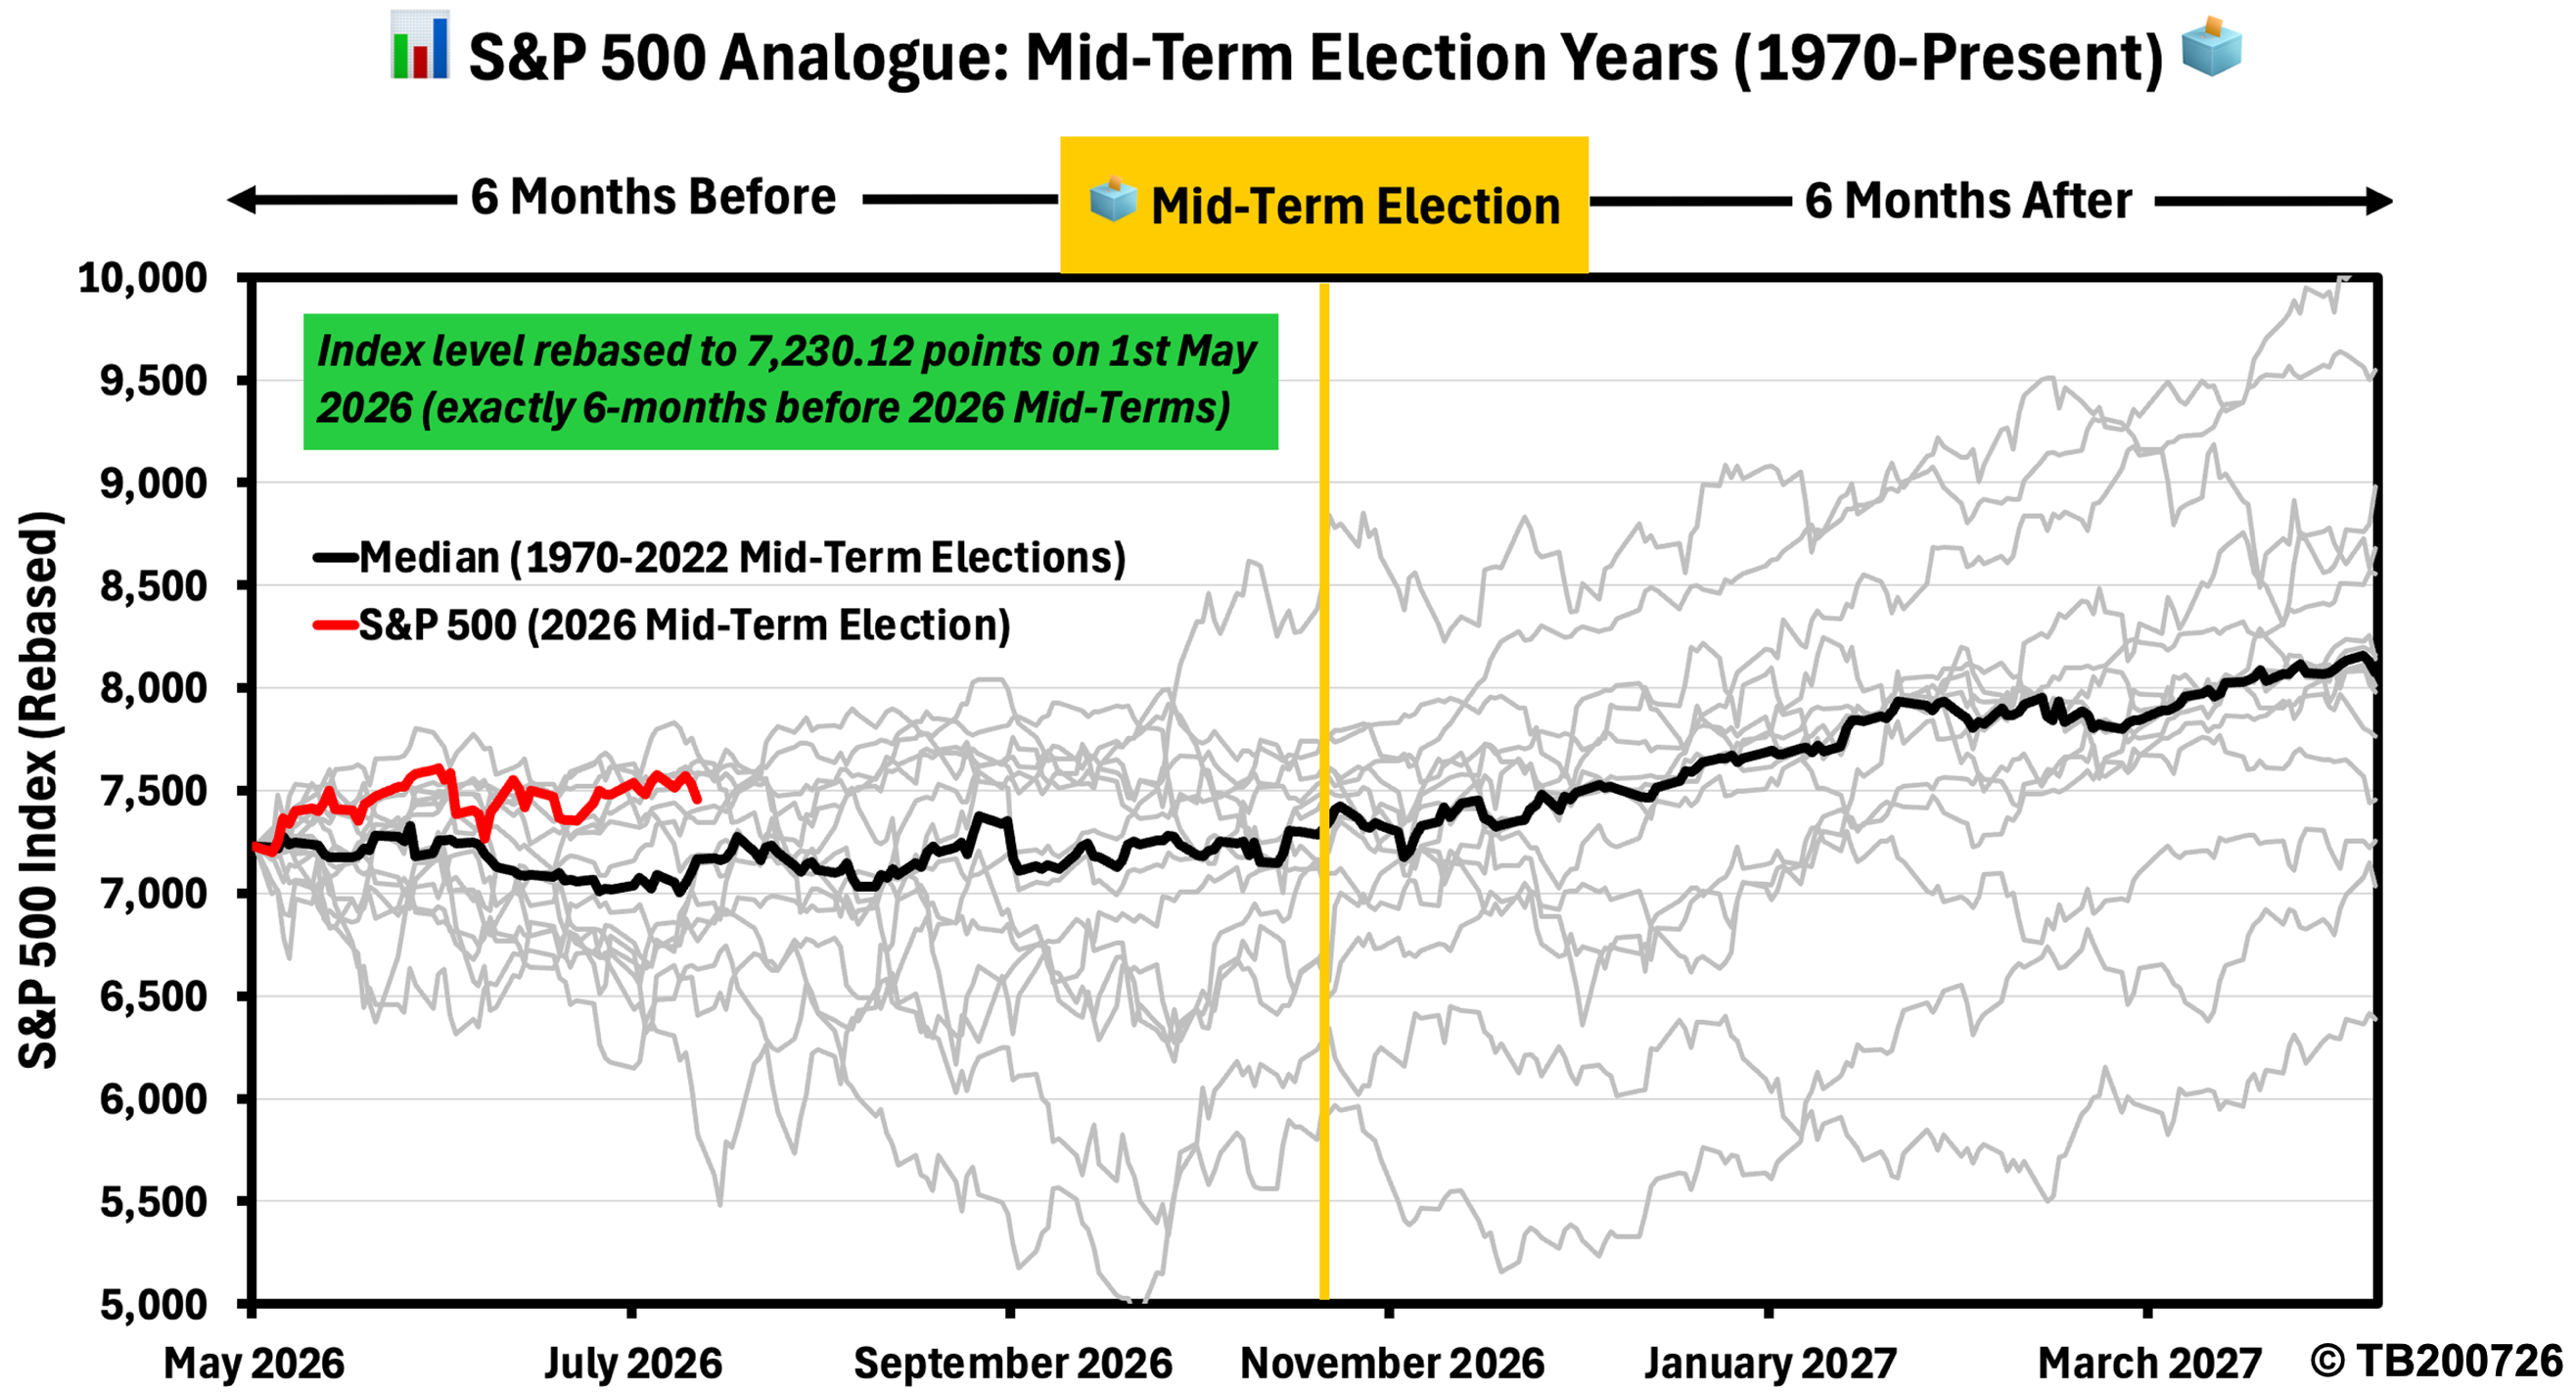
That equates to a gain of 10%. These figures should not be interpreted as forecasts. Every election cycle unfolds under different economic conditions, monetary policy settings and geopolitical risks. Nevertheless, the consistency is noteworthy.
Seasonality May Add Fuel
The historical pattern is further reinforced by market seasonality. The six months immediately following mid-term elections overlap with one of the strongest seasonal periods for U.S. equities, encompassing both the final quarter of the calendar year and the opening months of the next.
Historically, these periods have often delivered stronger-than-average returns as institutional investors reposition portfolios, earnings expectations improve and year-end capital flows support broader market strength. Five of the six months following the mid-term election fall within these historically favourable seasonal windows, potentially providing an additional tailwind if broader economic conditions remain supportive.
Expressing The View
For investors who believe the S&P 500 could broadly follow the historical mid-term pattern, the next question becomes how to participate in any post-election strength while managing the risk that history fails to repeat itself.
Scaling Into Weakness
Rather than attempting to identify the precise market bottom, an approach I would use would be to gradually build a position during periods of weakness. Instead of investing all my available capital, I would retain a cash allocation and scale into the market if the anticipated pullback unfolds.
Using the historical roadmap as a guide, one-third of my available cash allocation would be invested if the S&P 500 declined to 7,313 points. If weakness continued, 50% of my remaining cash would be deployed at 7,122 points, with the balance invested at 6,969 points should the correction deepen.
Assuming all three levels were reached, my average entry price would be 7,135 points. More importantly, this disciplined approach avoids the need to perfectly time the market while allowing me to average into lower prices if volatility increases.
The Critical Line in the Sand
The final accumulation level also carries considerable technical significance. Since breaking above the major market peaks established in 2000 and 2007 during 2013, the S&P 500 has displayed remarkable symmetry. Once the index has broken above a major cyclical high and gone on to record fresh all-time highs, it has never subsequently closed a month below that former breakout level. The most recent major pivot occurred in January 2026, when the S&P 500 peaked at 7,002 points. That level therefore becomes the critical line in the sand.
An intra-month move below 7,002 points would not necessarily invalidate the historical analogue. Markets frequently overshoot important technical levels before recovering. Provided the index reclaimed 7,002 points by month-end, the broader bullish structure would remain intact. Conversely, a confirmed monthly close below 7,002 points that was not subsequently recovered would represent a meaningful deterioration in the technical picture. Under that scenario, the historical mid-term analogue may no longer be applicable, increasing the probability that a significantly deeper correction is evolving. A disciplined risk-management approach I would use would involve exiting long positions and waiting for a confirmed monthly close back above 7,002 points before turning constructive once again.
From a risk-reward perspective, the setup appears compelling if the historical pattern ultimately plays out. Assuming the S&P 500 first retraced to all three of my accumulation levels before subsequently advancing toward the historical post-election median target of 8,076 points, the strategy would generate a gain of 13% based on the average entry price of 7,135 points. By contrast, if all three of my purchases were completed but the market instead confirmed a monthly close below the critical 7,002-point level and remained near 6,969 points, the implied loss would be 2% before I exited the position. While no historical analogue guarantees future performance, the asymmetry is noteworthy. Risking 2% for the potential opportunity to earn 13% represents a favourable risk-reward profile.
The Bigger Picture
Taken together, the historical evidence suggests investors may need to prepare for two distinct phases over the coming months. The first is the possibility of a healthy period of consolidation following one of the strongest pre-election rallies on record. The second is the historically favourable environment that has often emerged once election uncertainty subsides.
Naturally, inflation, monetary policy, corporate earnings, global growth and geopolitical developments will ultimately determine whether this cycle follows the historical script. Nevertheless, markets often leave behind recognisable footprints.
Whether this cycle ultimately follows the script – or writes an entirely new chapter – will be one of the defining market themes in the months ahead.