It was a relatively busy morning on the Eurozone economic calendar this morning. Key stats included German factory orders and German retail sales figures for January. The numbers were positive, delivering the EUR with brief respite ahead of the European open.
German Factory Orders
In January, factory orders rose by 1.8%, following an upwardly revised 3.0% increase in December.
According to Destatis,
- Not including major orders, new orders increased by 0.8%.
- Foreign orders jumped by 9.4%, with new orders from non-euro area countries up 17.0%.
- New orders from the euro area fell by 2.6%, with domestic orders sliding by 8.3%.
- In January, consumer goods orders were a drag, sliding by 4.6%, with producers of intermediate goods seeing a 2.6% decline.
- New orders for capital goods jumped by 5.5%.
- Compared with January 2021, new orders were 7.3% higher.
German Retail Sales
In January, retail sales increased by 2.0%, partially reversing a 5.5% slide from December.
According to Destatis,
- Compared with January 2021, retail sales were up 10.3% and by 4.1% compared with the pre-crisis month of February 2020.
Market Impact
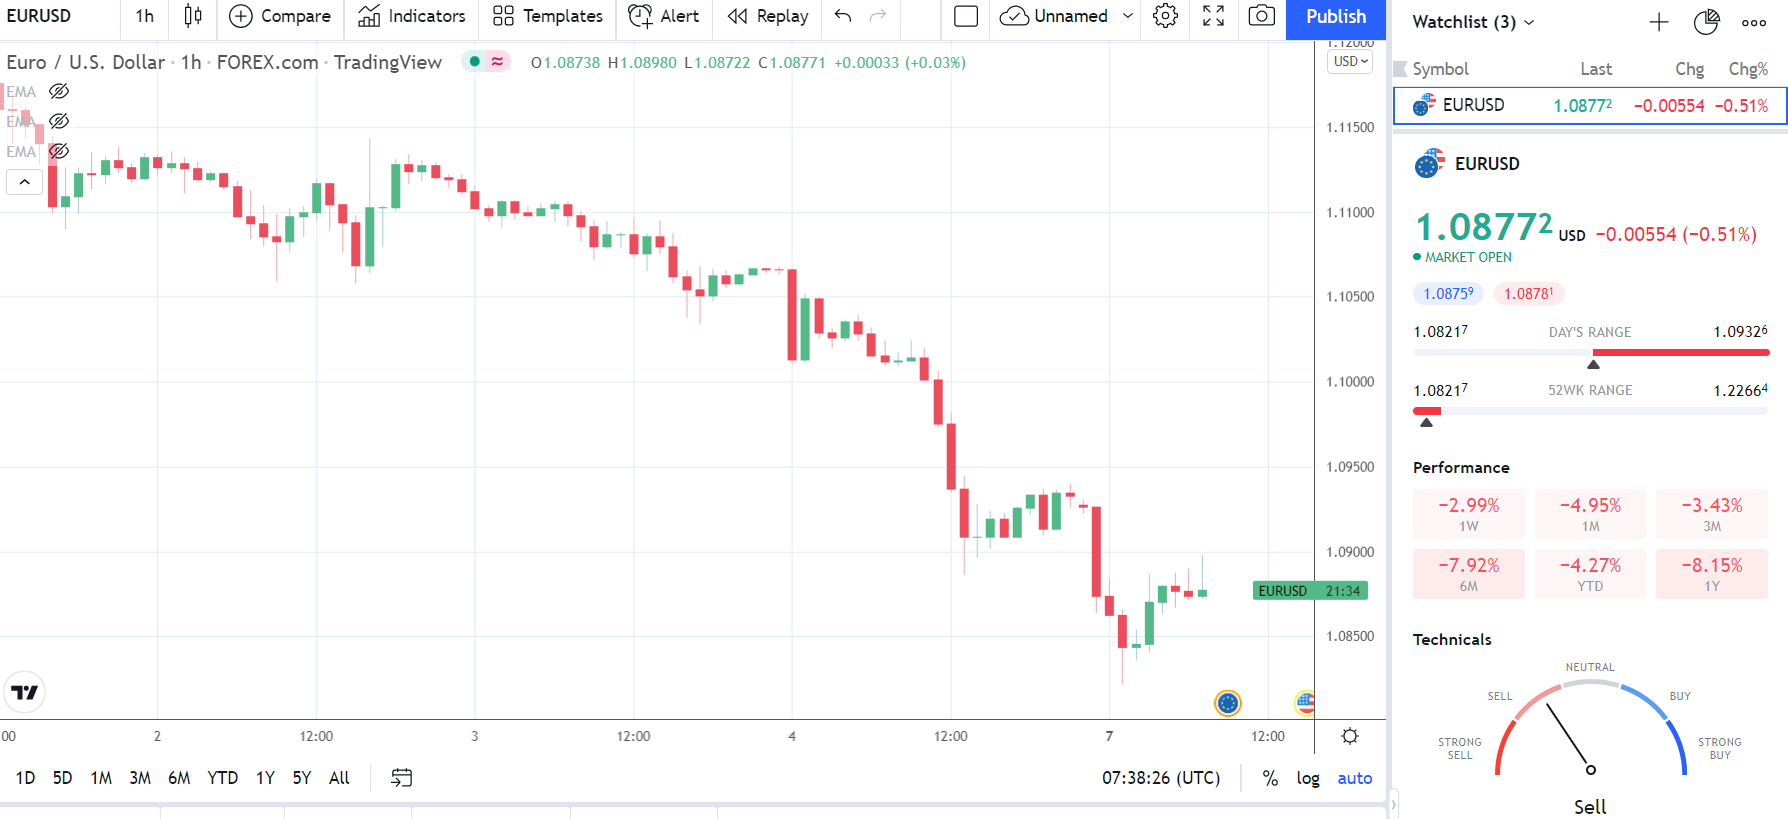
Ahead of today’s stats, the EUR struck a pre-stat and current day high of $1.09326 before sliding to a pre-stat and a current-day low of $1.08217
In response to today’s prelim inflation figures, the EUR fell to a post-stat low of $1.08722 before rising to a post-stat high of $1.0898.
At the time of writing, the EUR was down by 0.51% to $1.08772. Concerns over the impact of inflation and the Russian invasion of Ukraine on the Eurozone economy remained negative drivers for the EUR.