


It was a busy start to the European session this morning, with prelim private sector PMIs for France, Germany, and the Eurozone in focus.
From the ECB, the Economic Bulletin also drew plenty of attention, with the markets eyeing the ECB’s impact analysis of Russia’s invasion of Ukraine.
Member State Private Sector PMIs
According to prelim figures, the French manufacturing PMI fell from 57.2 to 54.8, while the services PMI rose from 55.5 to 57.4. Economists had forecast both PMIs to come in at 55.0.
Germany’s manufacturing PMI slipped from 58.4 to 57.6 versus a forecasted 55.8. The services PMI declined from 55.8 to 55.0 versus a forecasted 53.8.
Eurozone PMIs Reflect Modest Decline in Private Sector Activity
For the Eurozone, the manufacturing PMI fell from 58.2 to a 14-month low of 57.0, with the services PMI declining from 55.5 to a 2-month low of 54.8. Economists forecast PMIs of 56.0 and 54.2, respectively.
As a result, the Composite PMI slipped from 55.5 to a 2-month low of 54.5 versus a forecasted 53.9.
According to the prelim March survey,
- Despite the decline, the rate of expansion remained above the survey’s pre-pandemic long-run average.
- Renewed supply chain issues, uncertainty, higher costs, and weaker demand stemming from Russia’s invasion of Ukraine weighed on the manufacturing sector.
- Manufacturers reported a sharp fall in new orders, which fell to the lowest level since last October.
- New export orders for goods fell for the first time in 21-months.
- Average input prices across the private sector rose at the fastest pace on record.
- Business sentiment fell to its lowest level since October-2020.
ECB Economic Bulletin Focuses on Russia’s Invasion of Ukraine
The ECB Economic Bulletin painted a bleak picture. Sentiment was aligned with last week’s ZEW Economic Sentiment figures for Germany and the Eurozone.
In March, Germany’s ZEW Economic Sentiment Index tumbled from 54.3 to -39.3, with the Eurozone’s sliding from 48.6 to -38.7.
Salient points from the Economic Bulletin included:
- The Russian invasion will materially impact economic activity and inflation.
- Higher energy and commodity prices, disruption of international commerce, and weaker confidence will hit economic growth prospects.
- The degree of impact will depend on the impact of current and future sanctions and on how the conflict evolves.
- If the medium-term inflation outlook does not soften, the ECB will end net purchases under the APP in the third quarter.
- Net purchases under the APP will be €40bn in April, €30bn in May, and €20bn in June.
- Any adjustments to the key ECB interest rates will take place after the conclusion of the net purchases under the APP.
- Risks to the economic outlook have increased substantially and tilted to the downside.
Market Impact
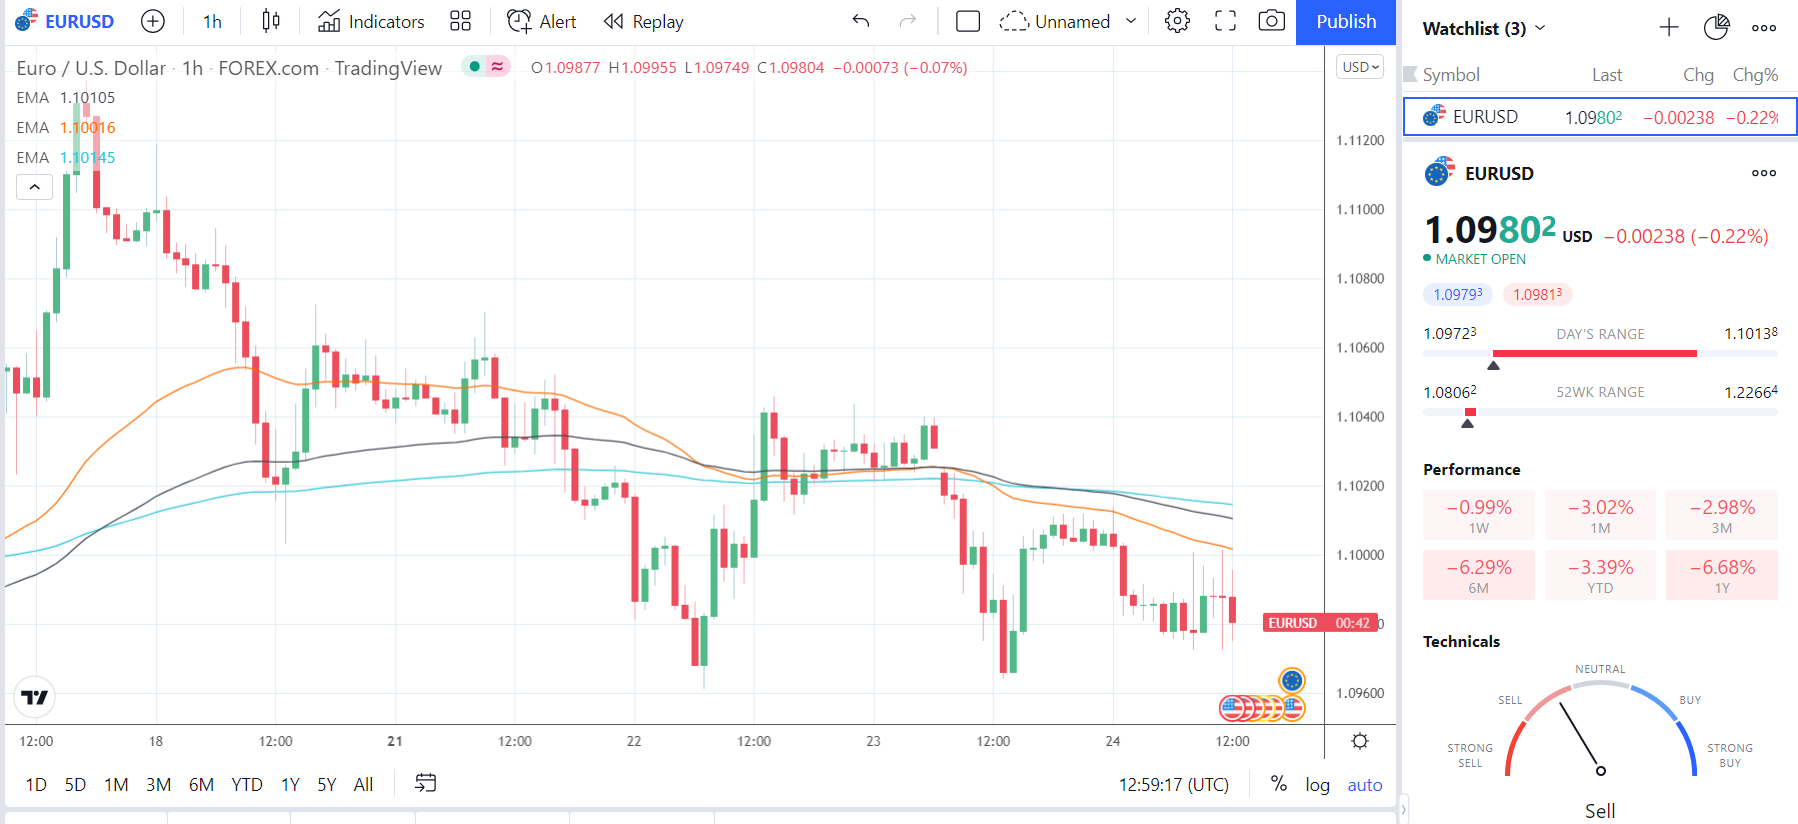
Ahead of today’s stats and bulletin, the EUR struck a pre-stat and current-day high of $1.10138 before sliding to a pre-stat low of $1.09724.
Following today’s figures, the EUR fell to a post-stat and current-day low of $1.09723 before finding support.
At the time of writing, the EUR was down by 0.22% to $1.09802.
Next Up
Prelim March private sector PMIs from the U.S. will be due out shortly.