


It was a busy day on the UK economic calendar. The UK GDP Report for February drew interest this morning.
UK economic indicators have continued to impress, reflecting a resilient economy despite the inflation-central bank influence on consumption. The recent economic indicators put a greater onus on today’s figures, with hotter-than-expected numbers likely to influence sentiment toward BoE monetary policy.
The numbers had to beat expectations to offset recent dovish Monetary Policy Committee member chatter.
In February, the UK economy stalled following a 0.4% expansion in January. Economists forecast growth of 0.1%.
According to the Office for National Statistics,
- Growth in construction offset falls in services and production.
- The services sector contracted by 0.1% after expanding by 0.7% in January.
- However, output in consumer-facing services grew by 0.4%, supported by growth in retail trade (excl. motor vehicles and motorcycles).
- Production output fell by 0.2%, following a 0.5% decline in January. Electricity, gas, steam, and air conditioning supply fell by 2.2%, the main contributor to the fall in production output.
- Manufacturing production was flat after a 0.1% fall in February.
- However, trade data was mixed. The UK trade deficit widened from £16.09 billion to £17.53 billion, while the non-EU trade deficit narrowed from £6.57 billion to £6.52 billion.
- On a three-month rolling basis, the economy grew by 0.1%
GBP/USD Reaction to the UK GDP Report
Ahead of today’s stats, the GBP/USD fell to an early low of $1.24809 before rising to a pre-stat high of $1.24965.
However, in response to the UK GDP Report, the GBP/USD rose to a post-stat high of $1.24852 before falling to a session low of $1.24775.
This morning, the GBP/USD was flat at $1.24849.
US Dollar Index Price Forecast
Every new US Dollar Index analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all US Dollar Index forecasts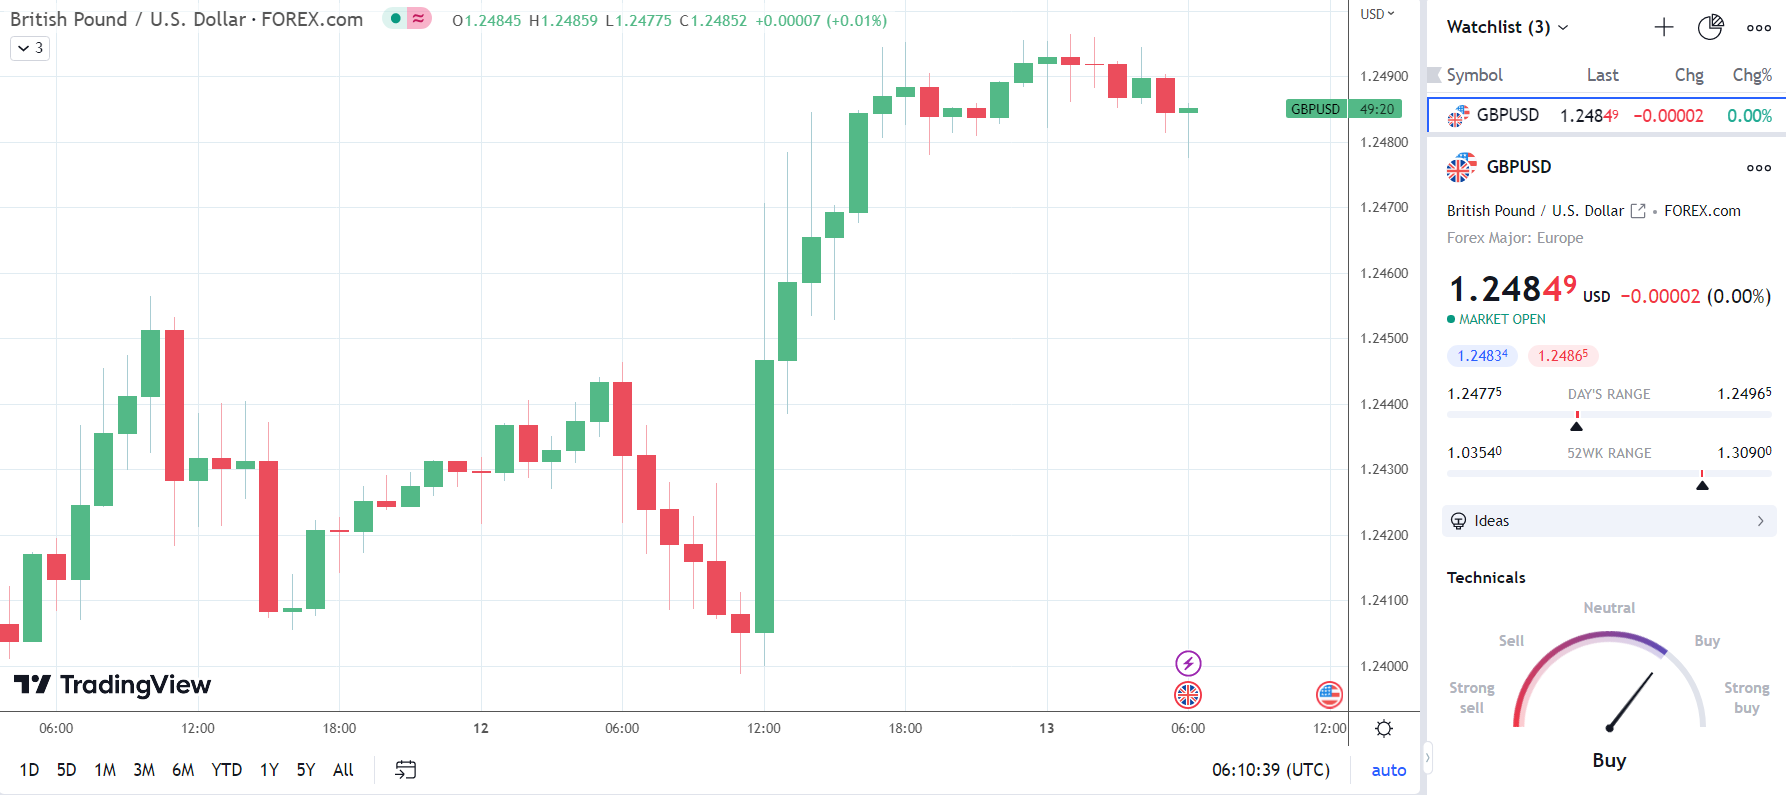
Next Up
Bank of England Governor Chief Economist Huw Pill will speak this afternoon. Forward guidance on inflation, the UK economy, and monetary policy will move the dial. Following the FOMC meeting minutes from Wednesday and recently bearish MPC member commentary, we expect Huw Pill to garner plenty of interest.
Last Tuesday, MPC member Silvana Tenreyro talked about cutting rates earlier and faster. Tenreyro was also in focus on Wednesday, discussing the impact of a persistent rise in bank funding costs on the UK economy.
Looking ahead to the US session, it is a busy day on the US economic calendar. US wholesale inflation and jobless claims will be in focus.
Following the softer-than-expected US CPI Report, a hotter-than-expected producer price index would test the theory of a Fed rate pause. However, initial jobless claims should increase modestly to support a hawkish policy outlook.
Investors should also monitor Fed chatter on monetary policy and the US economy.