


DAX Extends Losing Streak to Five Sessions
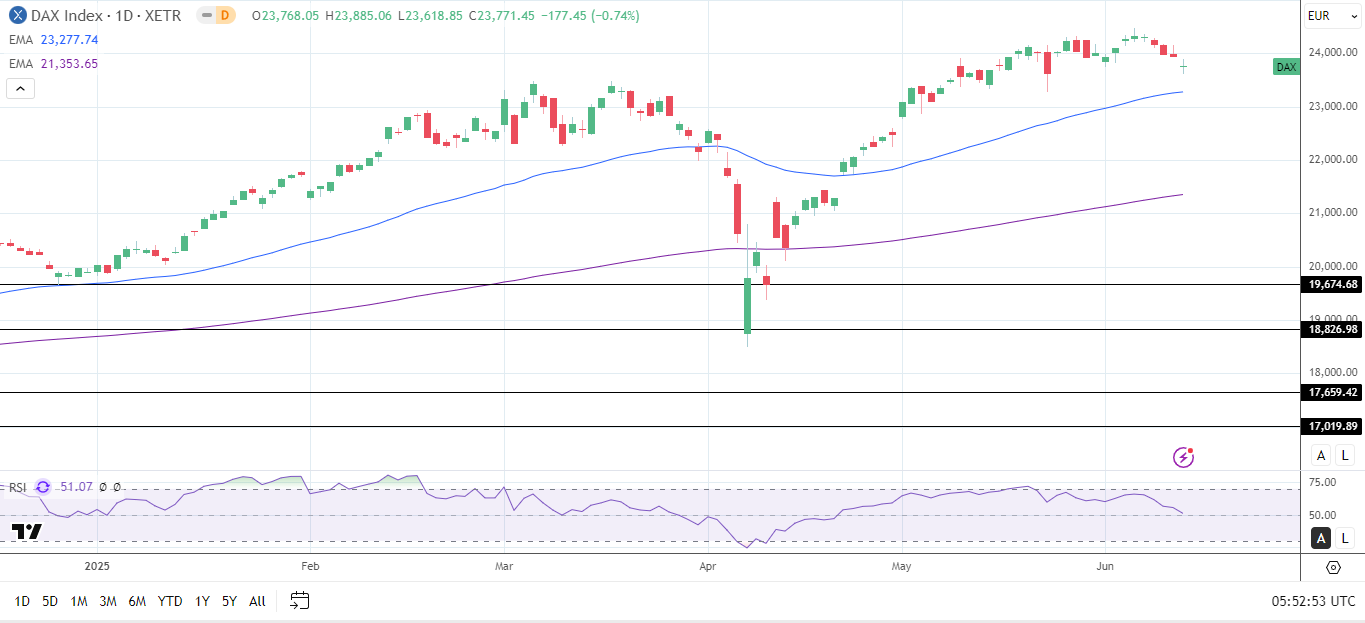
The DAX fell 0.74% on Thursday, June 12, adding to Wednesday’s 0.16% loss, closing at 23,772. Notably, the index extended its losing streak to five consecutive sessions.
Investors reacted to Israel’s threat of an attack on Iran. On June 12, Israel stated it was prepared to attack Iran after the Islamic Republic threatened the US if nuclear talks failed.
President Trump added to the risk-off sentiment, stating he would be sending letters to trading partners to settle unilateral tariffs.
Tech and Auto Stocks Drop on Tariff Warnings
Trump’s tariff announcement and rising Middle East tensions weighed on auto and tech stocks.
Infineon Technologies and SAP dropped 2.39% and 0.76%, respectively. Volkswagen declined 0.85%, with Mercedes-Benz Group, Porsche, and BMW also posting losses.
In contrast, Rheinmetall rallied 1.63% as geopolitical tensions intensified.
German Inflation in Focus as Oil Spikes
On Friday, June 13, German inflation numbers were in focus amid fears of Middle East tensions sparking a sustained oil price rally.
DAX Price Forecast
Every new DAX analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all DAX forecastsGermany’s annual inflation rate remained steady at 2.1% in May. Sitting just above the ECB’s 2% target, the inflation outlook may hinge on Middle East developments. An escalation in the Israeli-Iranian conflict could push oil prices higher, stoking inflation and potentially sinking central bank rate cut bets. Conversely, a de-escalation may support a softer inflation outlook, boosting demand for risk assets.
Wall Street Advances on Fed Rate Cut Bets
US markets advanced on June 12. US inflation and labor market data raised hopes of a 2025 Fed rate cut, boosting demand for risk assets. The Nasdaq Composite Index and the S&P 500 climbed 0.24% and 0.38%, respectively, while the Dow ended the session up 0.24%.
Key US economic indicators included jobless claims and producer prices. Core producer prices rose 3% year-on-year in May, down from 3.2% in April. As a leading inflation indicator, a downward trend may signal weakening demand and a softer inflation outlook. Jobless Claims 4-week average rose from 235.25k (week ending May 31) to 240.25k (week ending June 7), also supporting a more dovish Fed stance.
The DAX responded to the data, climbing to a session high of 23,885 before easing back.
US Consumer Sentiment in Focus
Later in the European session on Friday, June 13, the Michigan Consumer Sentiment Index will influence risk sentiment. Economists forecast the index to rise from 52.2 in May to 53.5 in June. A higher reading could signal a pickup in consumer spending, easing recession fears and lifting risk appetite. However, a lower print may revive recession jitters, pressuring risk assets, including the DAX.
US-EU Trade Developments, the Middle East, and the DAX
While economic indicators could influence market trends, geopolitical risk will remain the key market driver. An escalation in Middle East tensions and US-EU trade frictions would impact demand for DAX-listed stocks. On the other hand, a de-escalation could trigger a broad-based equity market rally.
Outlook: Key Catalysts for the DAX
The DAX’s near-term outlook hinges on the Middle East headlines, trade news, US data, and ECB commentary.
- Bullish Case: Positive trade developments, easing Middle East tensions, rising consumer sentiment, and dovish ECB cues could send the DAX above 24,000.
- Bearish Case: Intensifying geopolitical risks, weakened consumer sentiment, or hawkish ECB cues may pull the DAX toward 23,500.
At the time of writing on June 13, the DAX futures plunged 401 points, while the Nasdaq 100 mini tumbled 384 points, signaling a brutal end to the week.
Technical Setup Suggests Cautious Optimism
Despite a five-day losing streak, the DAX remains above the 50-day and the 200-day Exponential Moving Averages (EMA), signaling underlying bullish momentum.
- Upside Target: A break above 24,000 could pave the way to retesting resistance at the June 5 record high of 24,479.
- Downside risk: A break below 23,750 exposes the May 23 low of 23,275 and the 50-day EMA into play.
The 14-day Relative Strength Index (RSI), at 51.07, suggests the DAX has room to climb to 24,479 without entering overbought territory (RSI > 70).
Conclusion: Eyes on the Middle East, Trade Developments, and the ECB
Traders should closely track news from the Middle East, US-EU trade headlines, and ECB cues for guidance.
Explore our exclusive forecasts to assess whether improving trade sentiment could lift the DAX to new highs. Refer to our latest forecasts and macro insights here for further analysis, and consult our economic calendar.