


The EUR/USD was nearly unchanged testing higher levels early in the session, and faced tailwinds following the softer than expected U.S. payroll report. While Eurozone December inflation fell back, German retail sales were stronger than expected. French inflation edged higher and French consumer confidence also rose, providing a floor for the currency pair.
Technicals
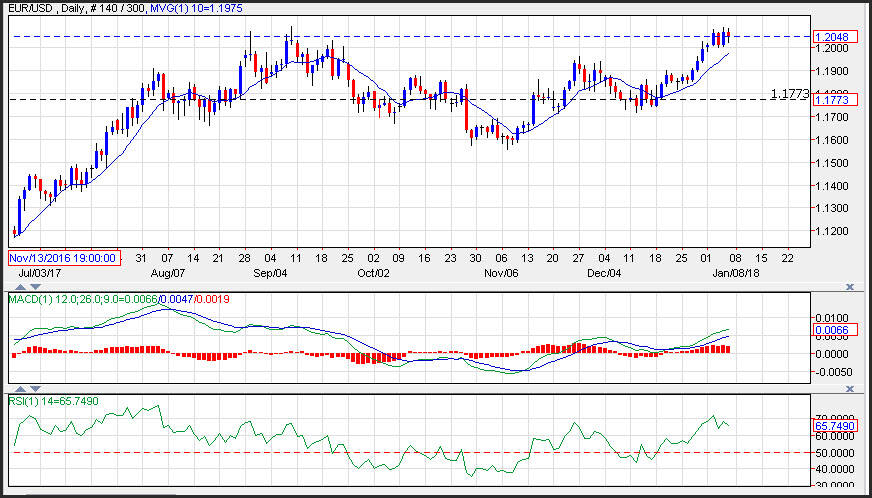
The EUR/USD is consolidating near the upper end of its recent range after pushing past the 1.1960 level and poised to test the September highs at 1.2092. Support is also seen near the 10-day moving average at 1.1975. Momentum is positive as the MACD (moving average convergence divergence) histogram is printing in the black with an upward sloping trajectory which points to a higher exchange rate.
Fed’s Bullard expects inflation in the low 2% range this year
Despite the gains in the job market, we’re still not seeing inflation, Bullard said in an interview. And he added expectations are low though have been moving up. Yet, he thinks the still modest rate affords the Fed the opportunity to wait and see. He reiterated yesterday’s comments that the FOMC should debate the yield curve and what the flattening means. In part it’s a function of the rate hikes. He doesn’t believe it’s currently portending a recession. Everything’s fine for now. He doesn’t want to mess with the 2% goal. Bullard become more dovish last year, worried about the soft price pressures.
Eurozone Inflation Fell Back
Eurozone December HICP inflation fell back to 1.4% year over year from 1.5% year over year, as expected. The deceleration in the headline rate was mainly due to abating price increases for energy and food prices, leaving the rate excluding energy unchanged at 1.2% year over year and core inflation at 0.9% year over year. The latter was slightly below consensus and will add to the arguments of the doves at the ECB. Still, while headline numbers seem to support the ECB’s very cautious approach to the phasing out of net asset purchases November PPI inflation jumped higher to 2.8% year over year from 2.5% year over year. Again energy price fluctuations are partly to blame, but with PMI surveys suggesting a capacity constraints and still strong underlying price trends and labor markets improving further, the overall data picture still suggests a gradual rise in headline rates ahead, even if base effects will lead to some fluctuations.
French Consumer Confidence Rose
French consumer confidence rose to 105 from 103 in the previous month, as consumers turn less pessimistic about the future standard of living as well as purchasing opportunities, with the latter in particular a sign that consumption will continue to underpin overall growth as the labor market improves.
French Inflation Rose
French December HICP inflation nudged higher to 1.3% year over year from 1.2% year over year in the previous month. The national rate remained steady at 1.2% year over year. Data were in line with expectations and do not change the outlook for a slight uptick in the overall Eurozone rate, due to be released later this morning. Indeed, French inflation has been below the Eurozone average for while. Base effects from food prices and energy inflation, which both abated in December, were counterbalanced by sharply higher tobacco prices and prices for manufactured products declined less than in November. The latter in particular indicates that inflation is set to pick up further next year, especially as the French manufacturing sector has made a remarkable come back and jobless numbers are coming down.
German Retail Sales Beat Estimates
German retail sales beat expectations. Sales rose 2.3% month over month in November, up from -1.0% month over month in October and leaving the annual rate at a strong 4.4% year over year. The November number left the three months trend rate at 0.5%, up from -0.2% in the three months to October.
U.S. Payrolls Missed Estimates
U.S. nonfarm payrolls rose 148k in December, disappointing expectations for a stronger gain. But it follow a revised 252k gain in November (was 228k) and a 211k October increase. The job market has posted gains since October 2010. The unemployment rate was steady at 4.1%. The labor force edged up 64k after the prior 162k rise, with household employment up 104k from 71k. The labor force participation rate steady at 62.7%. Earnings edged increased 0.3% versus 0.1% previously. The workweek was flat at 34.5. For other details, private payrolls increased 146k (ADP was 250k), with the goods producing sector adding 55k and construction 30k. Manufacturing employment increased 25k. Jobs in the service sector were up 91k. The government added 2k.