


AI Trade Finds its Footing
Market sentiment turned noticeably brighter this morning, as Anthropic’s long-awaited IPO filing revived appetite for the AI trade and Meta’s ambitious fundraising plans briefly eased investor anxieties about long-term AI profitability.
This ‘AI revival’ follows a particularly bruising spell in the equities complex. However, while we also saw a number of funding deals land alongside it – somewhat easing worries about the AI build-out – I remain cautious, as a number of key players are reporting earnings this week. These include Amazon, Apple, and Microsoft.
Chips Lead & the Dow Lags
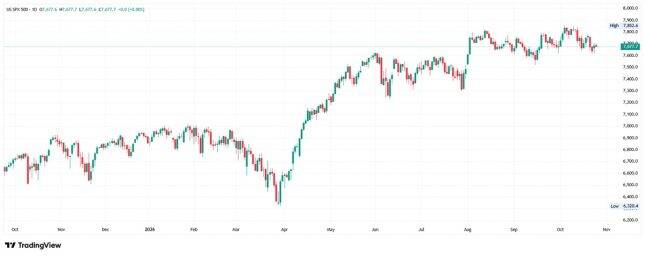
The S&P 500 gained about 0.7% on Monday, the Nasdaq Composite added 0.8%, and the Nasdaq 100 rose 1.1%, while the Dow lagged, up 0.3%. Semiconductors had their best session in over a month, and Nvidia was among the leaders.
Microsoft rose 1.5% after announcing buyouts for around 60,000 of its roughly 223,000 staff. Apple slipped amid reports of cracked screens on its new foldable, while Instacart jumped nearly 8% and DoorDash fell more than 6% on reports of advanced takeover talks.
KOSPI Jumps on Tech and GDP Beat
Asian equities – especially in tech-heavy sectors – reflected recent AI-driven enthusiasm, with notable gains in indices like South Korea’s KOSPI. This was helped by a Q3 GDP beat (3.4% YY against 3.1% expected), and talk of larger shareholder returns at SK Hynix, which is up about 6.5%.
Brazil: Lula’s Win Rattles Investors
I would be remiss not to mention Brazil. Assets sold off hard after President Lula’s surprise re-election dashed hopes of a fiscal tightening. The iShares MSCI Brazil ETF fell as much as 26% intraday, and economists warned that the central bank has little room to cut rates, with its policy rate at 13.75%.
Yields Ease as Brent Slips
The US 10-year Treasury yield eased to roughly 4.97%, down more than 30 bps this month, while the two-year is around 4.71%.
Brent has slipped about 1% to around US$114.70 as officials from Saudi Arabia, Pakistan and Turkey travelled to Tehran to revive talks, although Washington is reportedly weighing renewed military action.
Australian CPI & RBNZ Decision Ahead
As a reminder, the Australian CPI inflation will land at 12:30 am GMT tomorrow, closely shadowed by the RBNZ rate decision at 1:00 am. Of the two, I think CPI could have more ‘juice’ for a market response, given RBA rate pricing and recent hawkish rhetoric from Deputy Governor Hauser and Assistant Governor Christopher Kent.
An in-line print should largely reaffirm this and be enough to lift the AUD, but a clear beat – coupled with CFTC data showing the AUD is overstretched to the downside – could notably add fuel to an up move.
Written by FP Markets Chief Market Analyst, Aaron Hill