


RBNZ Delivers a Surprise Hold
Last week was an interesting one. The RBNZ surprised everyone by holding the OCR at 2.75% – markets and economists had widely expected the central bank to hike to 3.00%. I was at the screen during the meeting, and the move higher in AUD/NZD was punchy, to say the least. Meanwhile, the BoC hiked its overnight rate as expected, while the Fed, ECB, and BoJ held steady.
Live Fed Meeting in December
On the Fed, I thought the 10-2 vote split was more noise than anything else, with Fed Governor Lisa Cook’s dissent effectively signalling independence and sending a rather direct message to President Trump. December’s meeting is certainly still live; you will recall the September dots projected one more rate hike this year, and, as of writing, OIS pricing is discounting 16 bps of tightening (63%).
Hot GDP; Stretched Consumer
Per the BEA’s initial Q3 26 estimate, US GDP came in hot at 3.4% versus 3.2% consensus last week. While better than expected and certainly making headlines, this growth was propped up by inventories and federal spending, both of which tend not to repeat. As a result, Q4 may not follow suit.
The data was also accompanied by firmer September US PCE inflation, which rose 0.5% MM and 3.6% YY at the headline level, with core also rising 3.1% YY. Under the hood, however, consumer spending is looking stretched. Real disposable income fell 0.3%, and the savings rate dropped to 3.8% from 4.1%. So, consumers are funding their spending by saving less, putting the Fed in a tricky spot.
AI Trade Takes a Hit
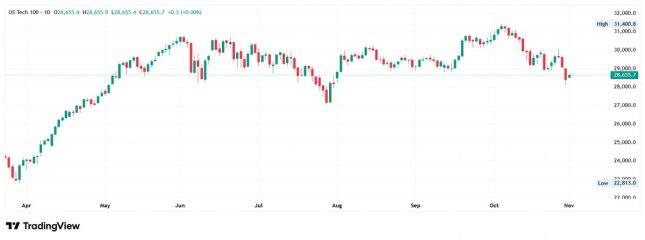
In equities, the AI trade took a hit last week amid scepticism over the AI buildout, with the Nasdaq 100 shedding 3.5% on Friday and nearing its third correction this year. I think it is fair to say ‘much’ of the AI trade was down in recent trading, from Amazon and Alphabet to chip stocks and software makers.
Ultimately, it boils down to whether spending can last, and if it pulls back, what happens next. And let’s be frank: no one has an explicit answer, as everyone expects this spending to continue.
Week Ahead: Payrolls & Midterms in Focus
This week, the focus will naturally be on the US Midterms on Tuesday and a slew of US jobs data that culminates with the October non-farm payrolls on Friday. Personally, I think the data will drive more of a market response than the election, given September payrolls came in soft at 29k and markets are only pricing in about a 60% chance of a December Fed hike.
This means the labour data could help decide what the Fed does ahead of the October CPI print. A firmer-than-expected payrolls reading would likely nudge Fed rate pricing back toward a fully discounted hike and give the USD a boost, while another soft print would perhaps prompt investors to pull back further on rate-hike bets and unwind some long positions – CFTC positioning suggests the buck is modestly overbought.
One thing I would say about the upcoming elections, and this is a question I have been asked a number of times, is whether the US equity market will continue to move higher following the Midterms. While I will be the first to say that history can never guarantee future performance, studies by JP Morgan suggest that since the 1950s the S&P 500 has delivered positive returns in the year following each Midterm election. If we see a divided Congress, not much changes, in my view, and it could ease some pressure on longer-dated yields. A Democratic sweep, nevertheless, would raise questions about corporate taxes and regulation and perhaps serve as a headwind for stocks.
Have a great week ahead!
Written by FP Markets Chief Market Analyst, Aaron Hill