


Stocks Down as Tech Gains Fade
Equities were green again on Wednesday, with the tech-heavy Nasdaq leading the way. Solid earnings from major AI names eased some of the market’s concerns about AI build-outs; SpaceX posted its first operating profit as a public company, and Meta beat revenue expectations.
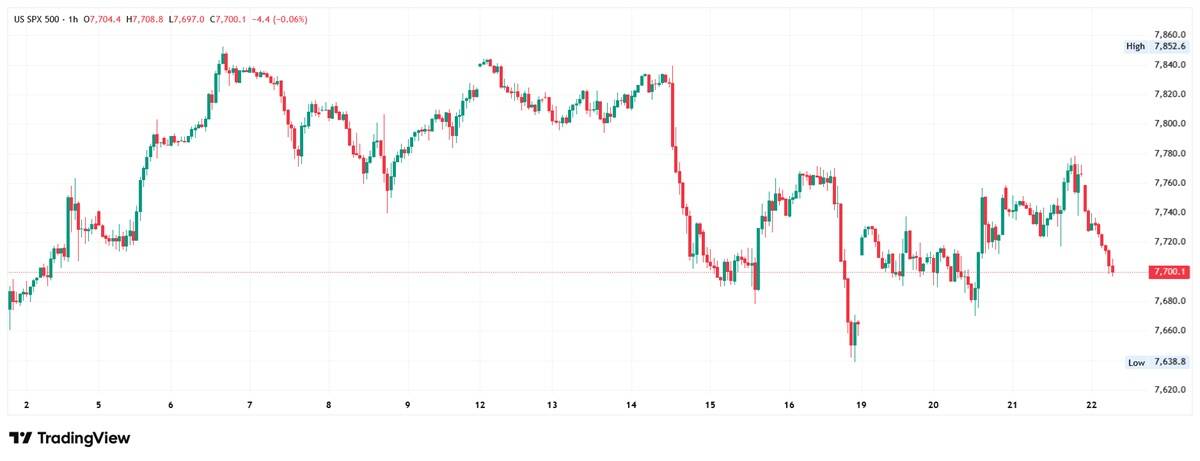
That optimism has not traveled well, however, with US equity index futures on the ropes this morning and Asia-Pac shares down: Japan’s Nikkei is off 2.1%, and South Korea’s KOSPI is down 3.3%.
Yen in Focus
FX was on the quiet side yesterday, which has largely carried through into today. The USD index continues to hover around daily support at 101.60, while EUR/USD is steady just north of the US$1.12 handle.
I am closely watching the JPY this morning. USD/JPY is off about 0.3%, breaking through daily support at ¥157.89 and perhaps eyeing lows around ¥156.97. I believe this move has been fuelled by recent comments from BoJ Deputy Governor Himino, who signalled readiness to raise borrowing costs.
Oil Remains Bid
For commodities, oil benchmarks finished another day at elevated levels. Brent crude is up 0.9% this morning and is once again attempting to manoeuvre north of US$110/barrel – a five-month high – while WTI remains near US$98.50.
Recent reports suggest that the US ordered non-emergency diplomats out of Saudi Arabia amid the growing Houthi threat, and the New York Times reported that the US and Israel have drawn up plans for renewed strikes on Iran after the Midterms.
Brent Oil Price Forecast
Every new Brent Oil analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Brent Oil forecastsHot UK CPI & Heavy Borrowing
On the macro front, the September UK CPI inflation came in hotter than expected, but the market reaction – FTSE 100 lower and GBP higher – was swiftly reversed; I believe this was just not enough of a beat to satisfy what is currently priced in the OIS curve: more than four BoE rate hikes, with November’s meeting fully priced (99% probability).
This – coupled with the UK government borrowing nearly £25 billion in September, with public debt estimated to have exceeded £3 trillion for the first time – comes a week ahead of UK Chancellor John Healey’s first Budget and illustrates the dilemma he faces.
Today’s Session
Today’s session is relatively quiet, with little tier-1 event risk. That leaves the earnings fallout and the AI trade in the driving seat. Havens are in demand, with the US 10-year yield down about four basis points to roughly 5.08% and the 30-year at a one-month low near 5.38%.
The takeaway is that the market is hard to please on capex: it frets when companies spend more and when they pull back. With the Philadelphia Semiconductor Index’s eight-session losing streak and last week’s 5.5% Nasdaq 100 drop, the bar for an earnings beat is now very high. Also, with Microsoft and Alphabet not reporting until mid-next week, oil may take centre stage in the interim.
Written by FP Markets Chief Market Analyst, Aaron Hill