


International markets have kicked off the week trying to stabilize after last week’s technology sell-off, with cheaper oil offering relief. Ahead of a critical U.S. inflation report tomorrow in the form of CPI, the recovery remained uneven, though early European trading showed the STOXX 600, FTSE 100, and DAX each up approximately 0.3%, while France’s CAC 40 slipped 0.1%.
Energy Provided the Clearest Link Between Geopolitics and Financial Conditions
Reuters reported that crude declined as President Donald Trump downplayed the likelihood of renewed strikes on Iran. The global market report placed the 10-year Treasury yield near 4.84%, slightly lower on the day. These were intraday observations and have since seen rates climb even higher.
Sustained declines in energy costs can ease pressure on household budgets and business margins, potentially reducing inflation expectations. That can support bonds and interest-sensitive shares. However, cheaper crude does not immediately reverse earlier price increases, and renewed supply disruptions could quickly change the calculation.
Canada Rising Despite Oil
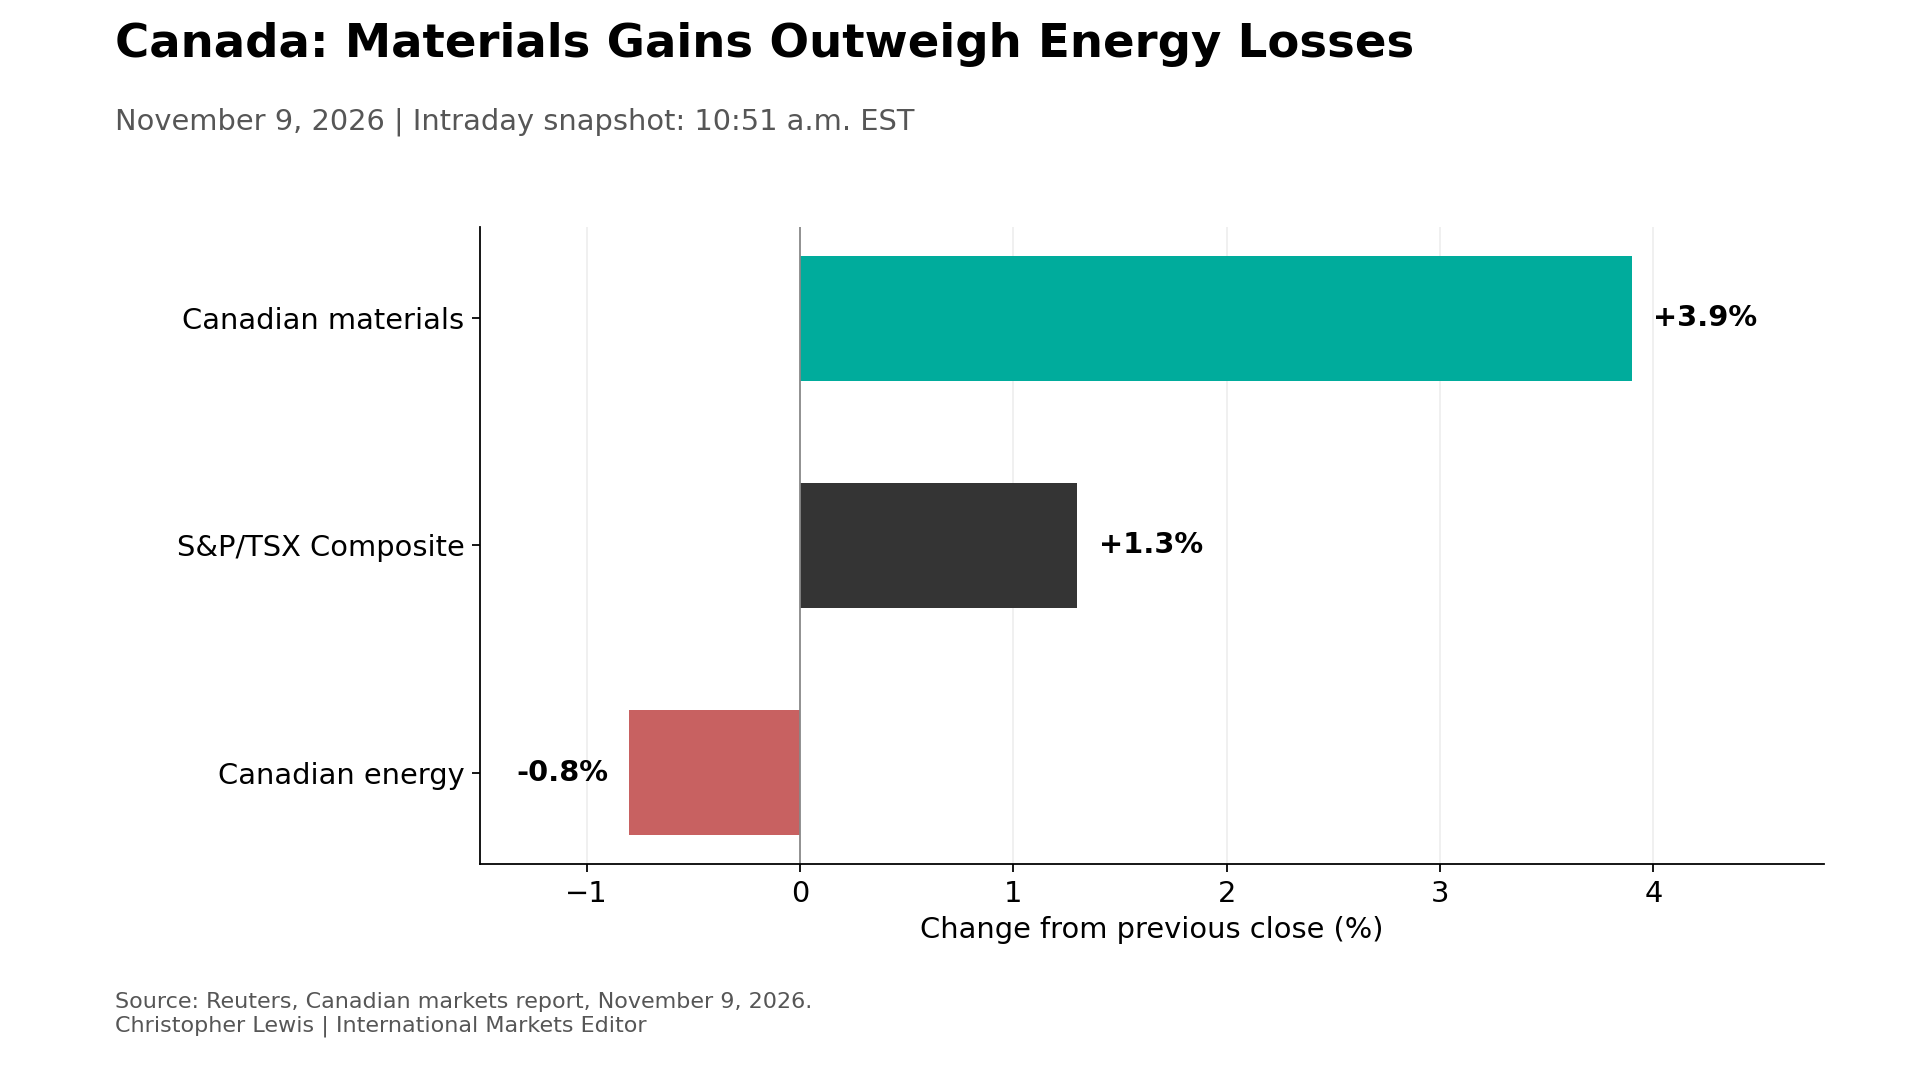
Canada illustrated why falling oil need not translate into national equity benchmarks. The S&P/TSX Composite is up 1.3%, while materials gained 3.9% and energy shares declined 0.8%. This divergence shows how much gains in mining companies could outweigh weakness amongst oil producers.
Brent Oil Price Forecast
Every new Brent Oil analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Brent Oil forecastsCurrency markets also unwound part of Friday’s defensive positioning. A separate foreign-exchange report from Reuters recorded the euro up a bit, sterling up 0.5%, and the dollar down slightly against the Japanese yen. This combination will deserve a certain amount of attention, as a softer dollar during an equity recovery does not necessarily signal that markets have abandoned expectations for tighter U.S. monetary policy. Reduced demand for defensive dollar holdings can temporarily outweigh interest-rate support.
U.S. Employment
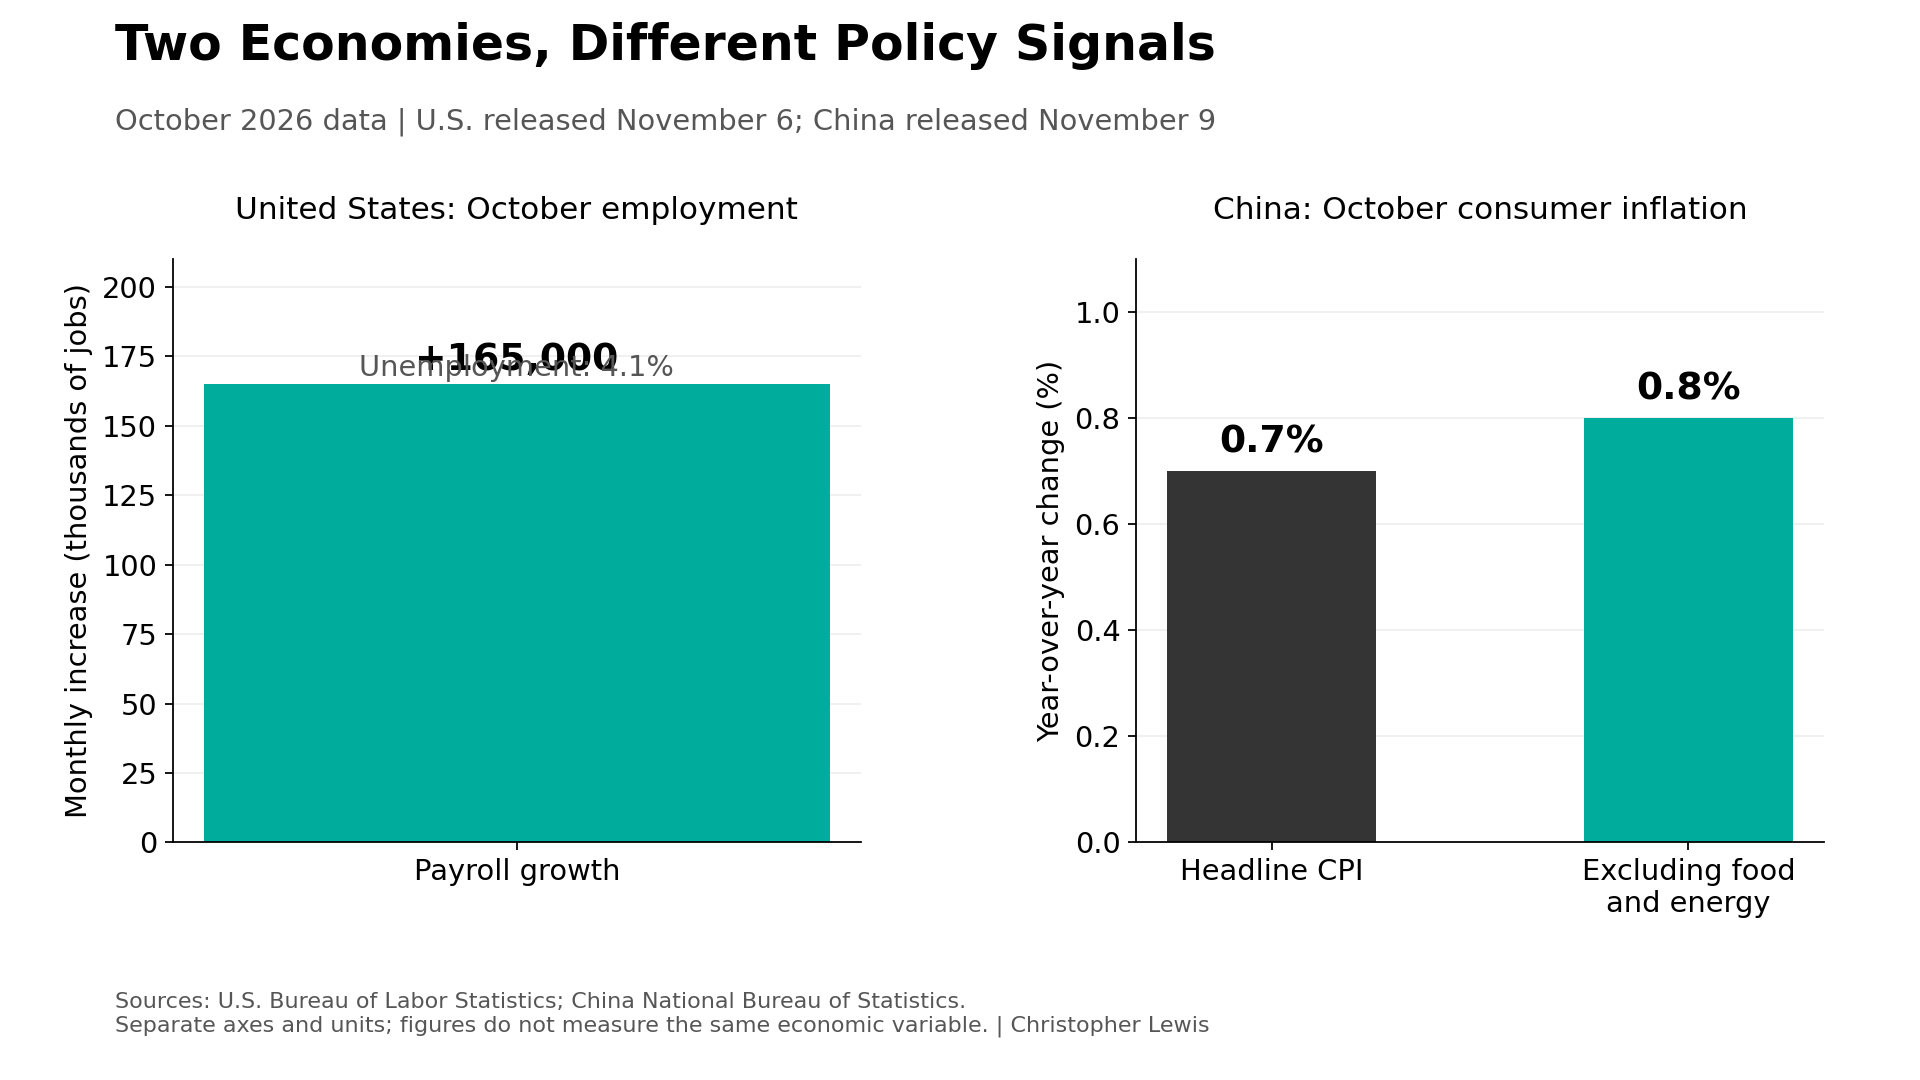
The U.S. employment backdrop remains resilient. Friday’s Bureau of Labor Statistics release found that October nonfarm payrolls increased by 165,000, while unemployment changed little at 4.1%. Employment gains included professional and business services, healthcare, and transportation and warehousing.
Chinese Consumer Prices
China’s latest figures highlighted a different inflation mix. The National Bureau of Statistics on Monday reported that October consumer prices rose 0.7% from a year earlier and were unchanged from September. Food prices fell 2.9% annually, while nonfood prices increased 1.5%. Excluding food and energy, consumer inflation was 0.8%.
The next scheduled U.S. test is October CPI, due Tuesday, November 10, at 8:30 ET. October producer prices follow on Friday, November 13, at the same time, according to the BLS calendar. Monday’s recovery is best thought of as conditional relief, with lower energy costs improving the outlook.