


Gold has an immediate problem: demand for protection has to compete with expectations for restrictive monetary policy, particularly from the Federal Reserve. Reuters’ Monday report described renewed pressure on bullion as investors weighed hawkish Federal Reserve signals and a firm U.S. dollar.
PPI Numbers Last Week
Friday’s producer price figures show why the inflation debate has not gone away. The BLS reported final-demand PPI up 0.3% during October, slower than September’s revised 1.4% increase but 6.5% above a year earlier. The measure excluding food, energy, and trade services rose 0.5% on the month and 4.9% annually.
For gold, slower headline inflation is helpful only if it changes the expected path of policy or inflation-adjusted returns. A softer monthly number alongside persistent underlying pressure does not guarantee that particular outcome. The relevant question will be how policymakers interpret the composition rather than simply that one headline is lower than the previous month.
CFTC CoT Report
Gold also has a dated catalyst this afternoon that is easy to overlook after the holiday. Last week’s delayed Commitment of Traders release from the CFTC comes out at 3:30 p.m. Eastern. This older snapshot will provide a bit of a baseline for the market. Legacy non-commercial gold futures positions comprised 223,530 long contracts and 40,982 shorts, giving a net long of 179,548. Spreading positions are separate and excluded from that subtraction.
These are broad legacy non-commercial categories, not the narrower managed-money classification in the disaggregated report. The distinction between gross and net exposure will be useful when the next report arrives. Net longs falling can reflect buyers closing positions, sellers adding shorts, or possibly both. Those mechanisms, of course, are going to be different. Considering an unchanged long book alongside a larger short book, the net figure declines, but describing the move solely as long liquidation would miss what happened.
Gold Price Forecast
Every new Gold analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Gold forecasts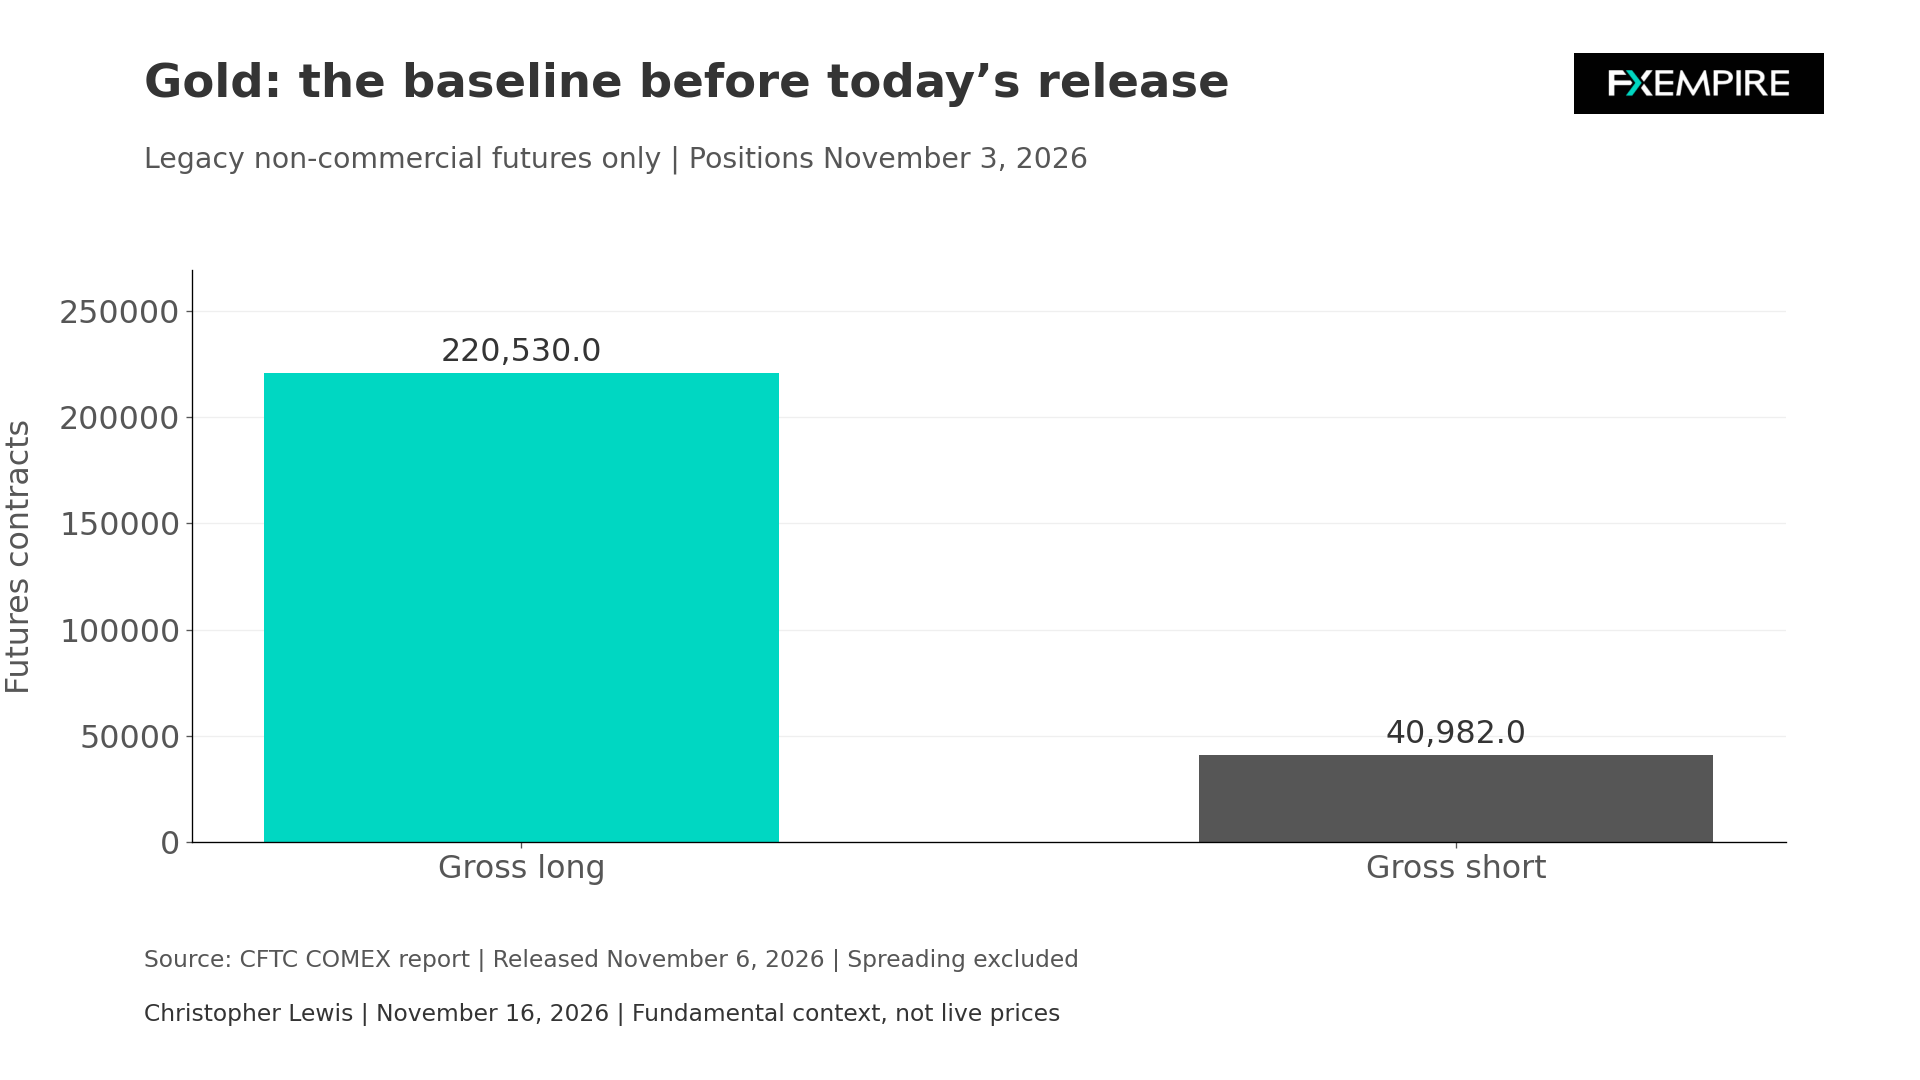
Warsh Speaks Today
There is also policy communication on the calendar today. The Federal Reserve lists opening remarks by Chair Kevin Warsh at noon Eastern at its Productivity and Jobs Task Force conference. The event’s subject does not guarantee a monetary policy signal. Any market interpretation should follow the actual remarks rather than assume that apparent changes are going to be made to the interest-rate outlook.
FOMC Meeting Minutes
The Fed’s calendar also schedules the October 27 and 28 FOMC minutes for October 18 at 2 p.m. Eastern. They can reveal the discussion behind that meeting, but they will predate the latest information releases. Their value is in showing the committee’s reasoning in areas of agreement or disagreement when setting monetary policy.
Investment flows provide a separate, older reference point. The World Gold Council’s November 5 report says October physically backed gold ETF holdings increased by 19 tonnes even as assets under management fell 6%. The falling portfolio value, therefore, did not mean investors collectively withdrew metal exposure. These are October observations, not evidence of buying at the moment.
The regional split is more informative than the global tone alone. European gold ETFs attracted $1.8 billion in October, while North American funds lost $512 million, according to the council. Demand was therefore uneven before the latest session. These flows do not establish which region will be driving trading on Monday, but they show why a single description of investment appetite can be far too broad in describing the market.
A rebound in the gold market would be more convincing if several independent measures improved together. Policy communication, fund demand, and futures participation all answer different questions. Agreement among them would provide stronger support than treating any single release as a turning point.
The Price Action on the Chart Is Pretty Dreadful
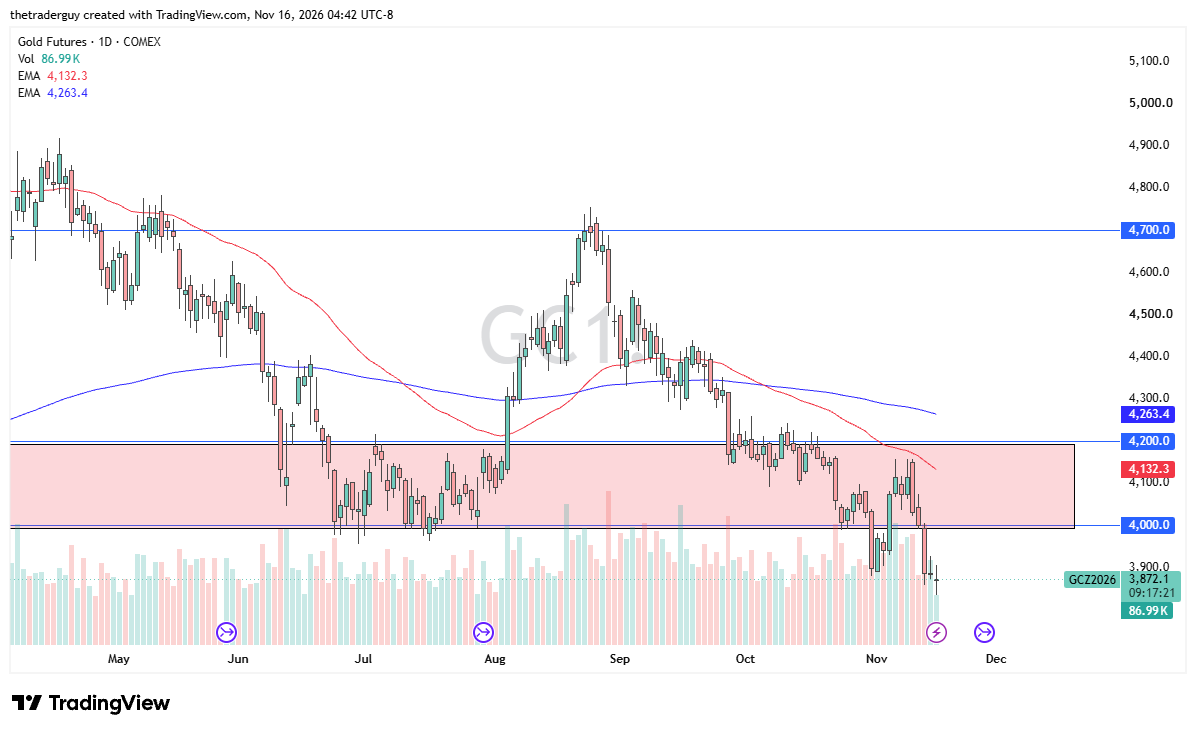
The immediate question for me is going to be whether the next positioning release shows a change in the balance between outright buying and short exposure. Even then, the observation date lags, so while it can improve the backdrop, it does not necessarily change the price action.
The price action on the chart is pretty dreadful, although it is probably worth noting that gold is at least pushing back a bit against the sellers during the trading session. I suspect rallies at this point will continue to be selling opportunities in a market that continues to face major headwinds, with real yields in America working against them. I remain relatively bearish, but recognize that we are perhaps a touch oversold in the short term.
If you’d like to know more about how to trade gold and silver, please visit our educational area.