


Life After Huang for Nvidia?
Market chatter was well and truly focused on former CEO Nvidia Jensen Huang, following reports of extramarital affairs. Just ahead of the US cash open yesterday, we learnt that Huang resigned and will have no role at all in the company. CFO Colette Kress – who has been with the company for 13 years and is well known on the Street – will serve as interim CEO while the Board searches for a permanent replacement.
I have seen two camps among investors; one side thinks Nvidia sinks without Huang at the helm, while another side believes this is not the end. I think we need to look at this in the near term and the long term. Ultimately, the company’s share price will likely see some volatility going forward, but I think the market will start looking ahead and assessing who is fit to take the reins.
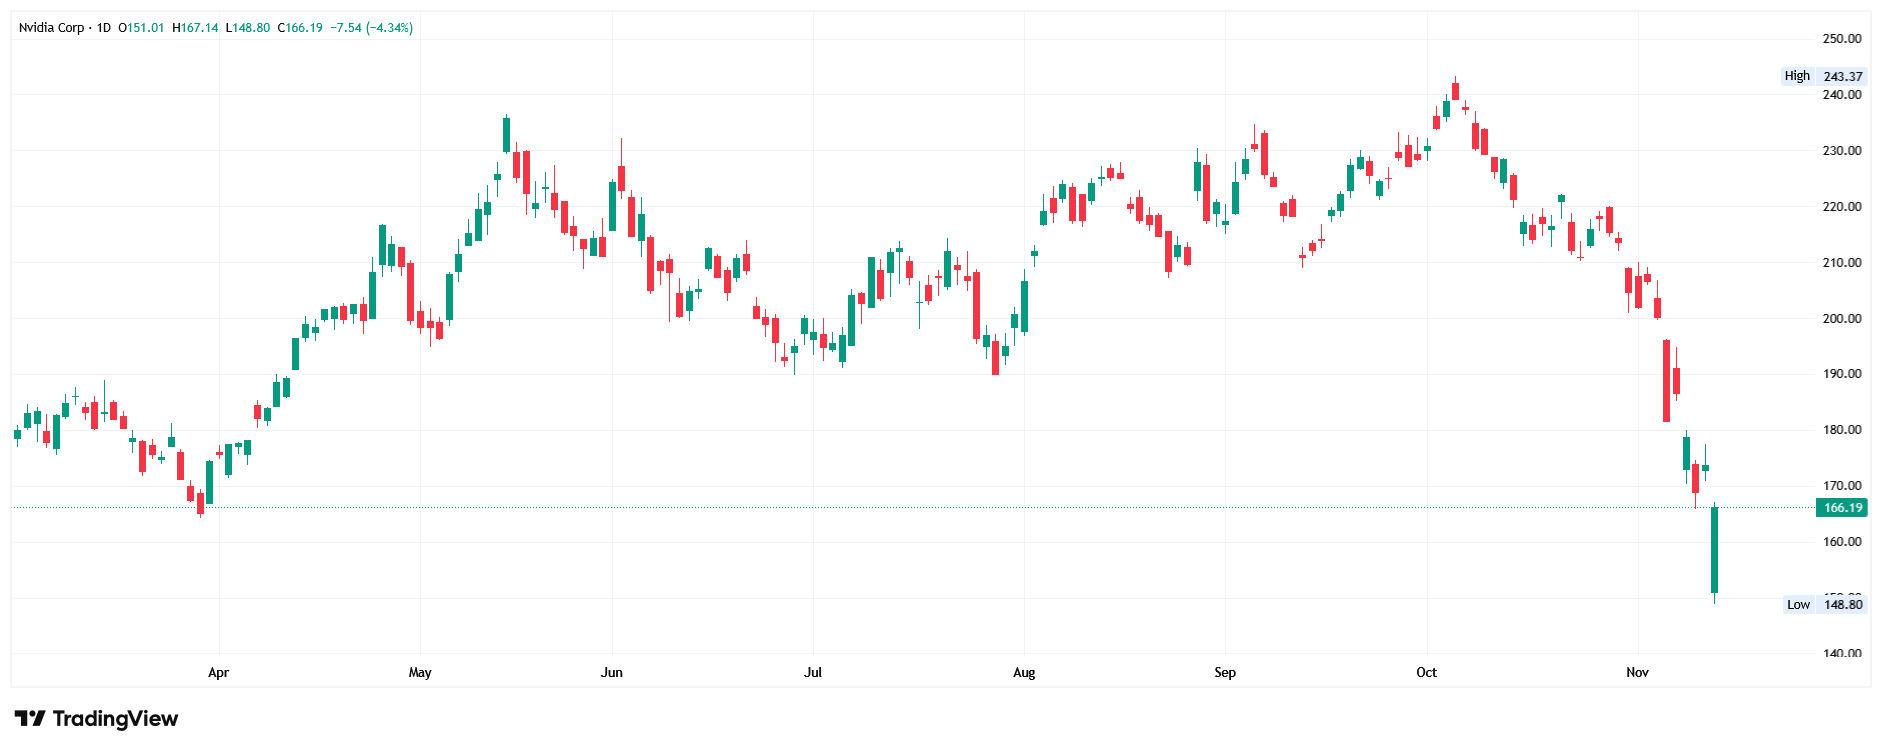
We saw this uncertainty at the open yesterday: Nvidia’s share price gapped nearly 14% lower, hitting its lowest level since July last year at US$148.80 and testing key weekly support around US$152.89. However, the move south was short-lived, and dip-buyers clearly entered the fray from the noted support, ending the session down about 4%.
Nvidia Headline Risk Remains
This is not a story that will die down anytime soon. Huang has agreed to testify regarding his relationship with Alice Huang – the alleged Chinese spy. Ultimately, the headline risk remains very much alive. Then there is the search for a credible CEO for Nvidia; the company’s Board is working with an outside firm to help with this active search. Not much has been said about this, but it appears they are casting a wide net, both internally and externally.
Market Snapshot
Overnight trading in Asia saw regional indices largely in the red, with South Korea’s KOSPI down nearly 1%, as of writing. Surprisingly, the Nasdaq 100 barely budged on Thursday; it opened down but quickly recouped most of the session’s losses.
In FX and rates, we have seen the USD refresh YTD highs north of 103.00 – levels not seen since early April last year. While I am sure more is driving the buck higher right now, we have to remember we had a hot October Jobs print, better-than-expected CPI inflation, and, not to mention, some rather hawkish Fed rhetoric of late. For US Treasury yields, the 10-year benchmark is up 27 bps this week. This has certainly dampened hopes that US bonds reclaimed their safe-haven role, a move largely driven by similar forces: inflation concerns and a hawkish Fed.
Macro Front
UK GDP numbers came in better than expected for some key prints on Thursday, including the MM report, showing 0.2% growth, versus the 0.0% forecast. It was quite refreshing to see the beat move both GBP/USD and the FTSE 100 above their average moves this year.
NASDAQ 100 Price Forecast
Every new NASDAQ 100 analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all NASDAQ 100 forecastsHowever, while we did see a jump in GDP growth, breadth is notably thin, which is quite concerning. Strength is concentrated in services – particularly business-facing and possibly AI-related activity – while production, construction, and the consumer side are weak. With high energy prices, soft housing data and downward revisions to August, downside risks certainly remain in my view.
We do have the October US PPI inflation numbers out today, and while YY headline is expected to tick higher to 6.6% (up from 6.3% in September), the report is anticipated to be mixed. Generally, this is not a big market mover, even with strong beats or misses.
Written by FP Markets Chief Market Analyst, Aaron Hill