


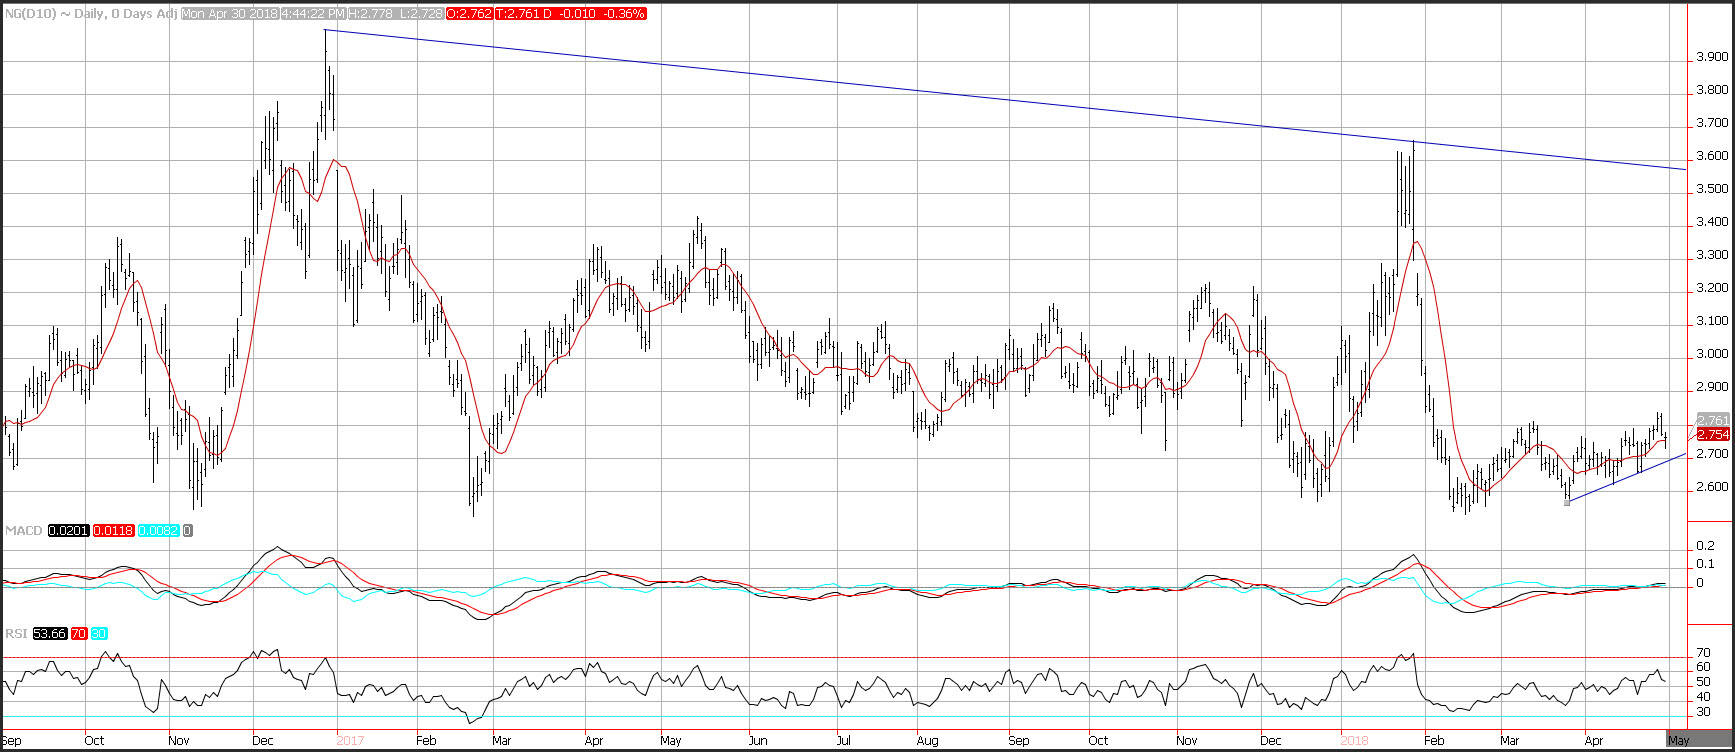
Natural gas prices moved lower but finished well of the session lows. Prices dipped below support but recaptured the 10-day moving average into the close. Resistance is seen near the April highs at 2.84. Momentum is neutral as the MACD (moving average convergence divergence) histogram prints in the black with a flat trajectory which reflects consolidation.
Supply Increases
According to data from the EIA, the average total supply of natural gas rose by 1% compared with the previous report week. Dry natural gas production grew by 1% compared with the previous report week. Average net imports from Canada increased by 2% from last week.
Demand falls as temperatures warm
Total U.S. consumption of natural gas fell by 6% compared with the previous report week, according to data from the EIA. In the residential and commercial sectors, consumption declined by 14%, as weather was warmer than normal west of the Rocky Mountains and close to normal on the eastern seaboard. Natural gas consumed for both power generation and in the industrial sector declined by 2% week over week. Natural gas exports to Mexico decreased 1%.
U.S. liquefied natural gas exports remain flat week over week. Six LNG vessels from Sabine Pass and Dominion Energy Cove Point liquefaction terminals departed the United States from April 19 to April 25. Four vessels departed the Sabine Pass liquefaction facility, and one vessel was loading at the terminal on Wednesday, April 25.
U.S. personal income rose
U.S. personal income rose 0.3% in March, with spending rising 0.4%. The 0.4% income gain from February was revised to 0.3%, while the 0.2% spending increase was bumped to down unchanged. Wages and salaries increased 0.2% versus the prior gains of 0.4% in February which was revised from 0.5% and 0.5% in January revised from 0.6%. March disposable income was up 0.3% versus the prior 0.3% revised from 0.4%. The savings rate dipped to 3.1% from 3.3% revised from 3.4%. The PCE deflator was unchanged versus February’s 0.2%. The core rate was up 0.2%, as it was in February. On a 12-month basis the headline index rose to 2.0% year over year compared to 1.7% year over year previously revised from 1.8%, with the core rate at a 1.9% year over year clip versus 1.6% year over year.