


The Day Ahead Market Overview: Markets Hold Ground as Fed Meeting Kicks Off and Tariff Risks Linger
U.S. equity futures were slightly weaker early Tuesday as Wall Street turned its focus to the Federal Reserve’s two-day policy meeting and continued tariff uncertainty. S&P 500 futures dipped around 0.2%, Nasdaq-100 futures slipped 0.35%, and Dow futures were marginally lower by 26 points.
Monday’s session saw the S&P 500 fall 0.6%, breaking a nine-day winning streak—the index’s longest since 2004. The Nasdaq declined 0.7%, while the Dow shed 0.2%. While stronger-than-expected ISM Services data offered a brief cushion, sentiment remains capped by uncertainty around U.S. tariff policy and its potential growth impact.
Trade Balance Data in Focus as Investors Weigh Growth Signals
- U.S. Trade Balance (March) – 12:30 GMT
Consensus and previous figures were not provided, but this data may be scrutinized more closely given ongoing tariff discussions.
Tech Earnings Take Center Stage with AMD and SMCI on Deck
Before the Open:
• Datadog (DDOG) – Expected EPS: $0.43
• Duke Energy (DUK) – EPS: $1.59
• Ferrari (RACE) – EPS: $2.49
• Marriott (MAR) – EPS: $2.25
• Global Payments (GPN) – EPS: $2.68
• Constellation Energy (CEG) – EPS: $2.18
• Zoetis (ZTS) – EPS: $1.41
After the Close:
• Advanced Micro Devices (AMD) – Expected EPS: $1.01, Revenue: $7.29B
Traders will watch for commentary on data center GPU demand and any tariff-related outlook cuts.
• Super Micro Computer (SMCI) – EPS: $0.30, which represents a significant decrease of 95% year-over-year.
• Kinross Gold (KGC) – EPS: $0.23
• Electronic Arts (EA) – EPS: $1.05
Fed Meeting Begins: Powell’s Comments Could Shift Market Tone
The Fed’s policy meeting begins Tuesday, with no rate change expected. Fed Chair Powell will speak Wednesday at 18:30 GMT following the 18:00 GMT policy release. Market pricing shows just a 2.7% chance of a cut this week, and a declining probability of a June cut. Investors will be parsing Powell’s remarks closely, especially in light of recent tariff developments and political pressure from President Trump.
Gold Steady, Oil Slips as Investors Watch Policy and Supply Trends
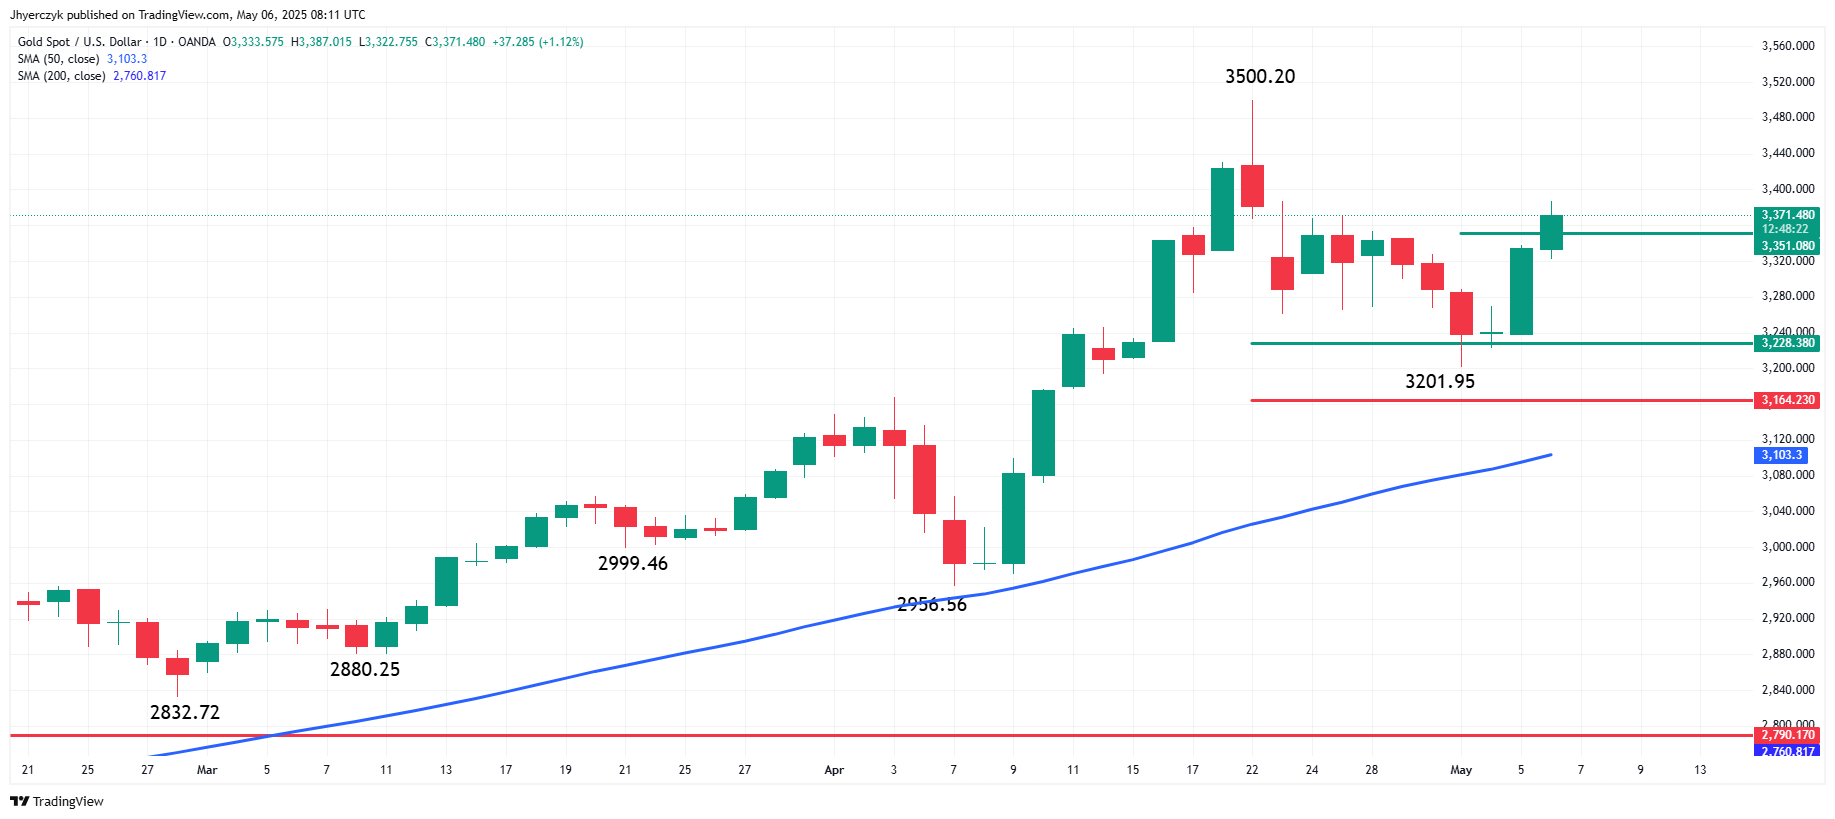
Gold remains elevated, up 44% year-over-year and 21% since the November election. Iamgold and Kinross report after the bell. Brent crude sits near $60/bbl, with WTI around $57 following OPEC comments on supply increases. Energy sector performance is mixed, with standout gains in Texas Pacific Land and EQT, and heavy year-to-date losses in APA, Halliburton, and Occidental.
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecastsS&P 500 Futures Hover Above 50-Day; Key Resistance Ahead
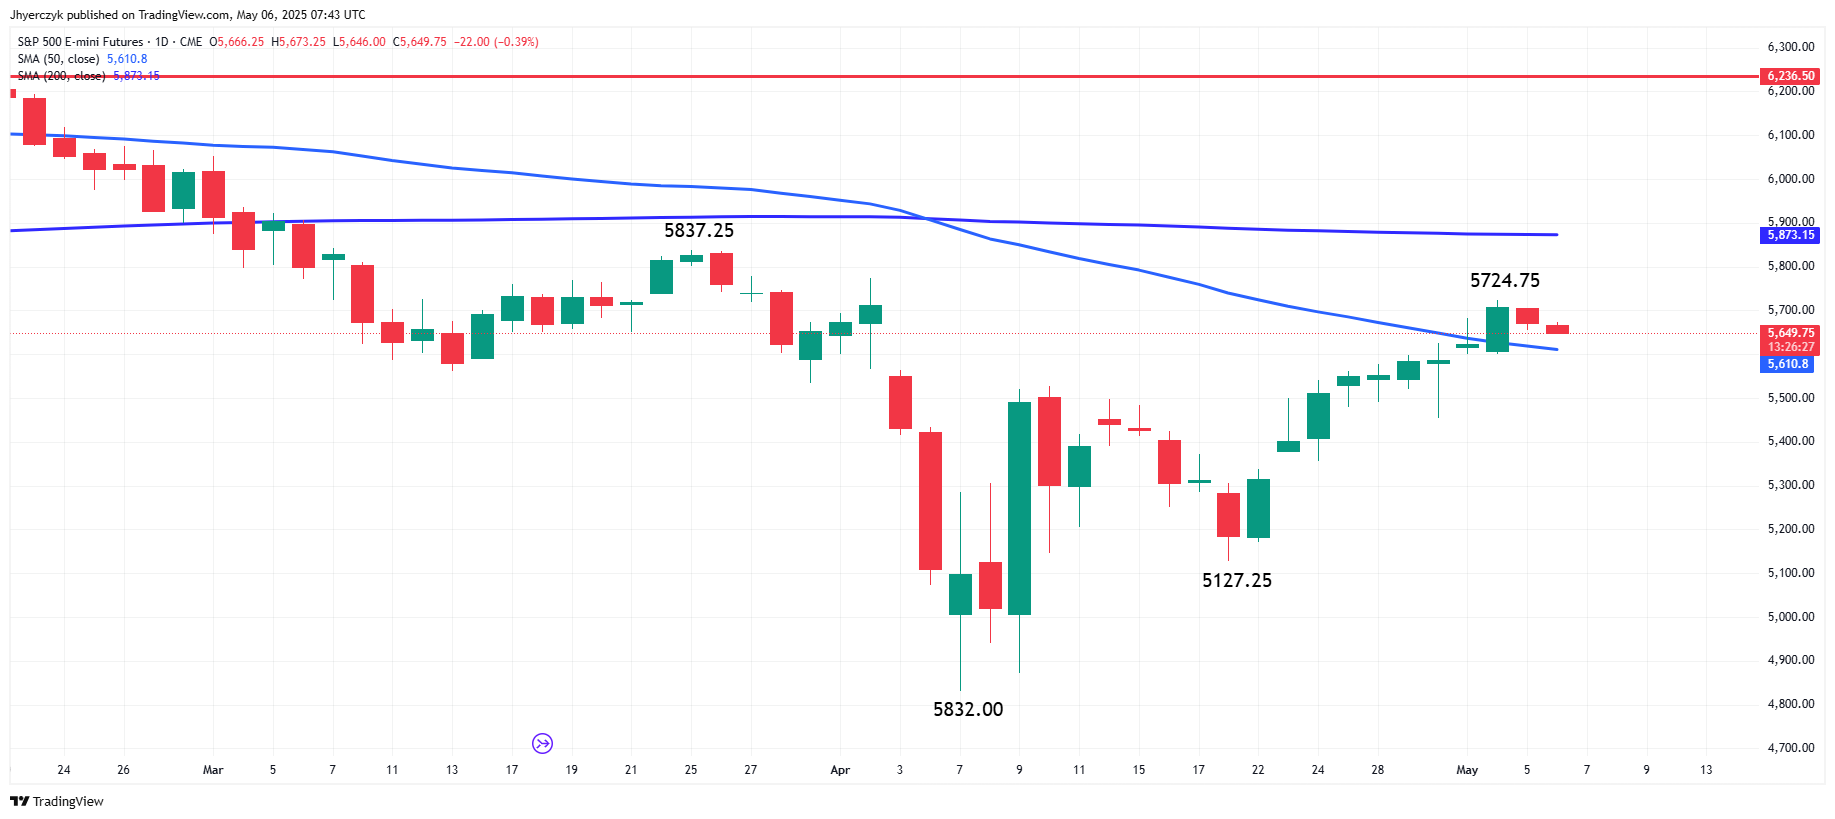
S&P 500 E-mini futures are holding just above the 50-day simple moving average at 5610.8 after failing to clear resistance near last week’s 5724.75 high. Despite a minor pullback, price remains above the 50-day SMA, keeping the recent uptrend intact for now. Initial resistance stands at 5724.75, followed by the 200-day SMA at 5873.15. Support is anchored at the 5601.00 level—losing that could open a drop toward 5500.00.
The Day Ahead Market Outlook: Caution Sets Tone Today Ahead of Fed, Earnings, and Trade Clarity
Tuesday’s trade hinges on early earnings, tariff headlines, and positioning ahead of the Fed. AMD’s report and Powell’s upcoming press conference are the top event risks. Caution may dominate as traders await policy clarity from both the Fed and the White House.
More Information in our Economic Calendar.