


Leadership Shakeup at Nvidia Hits Asia
Well, it was quite the week.
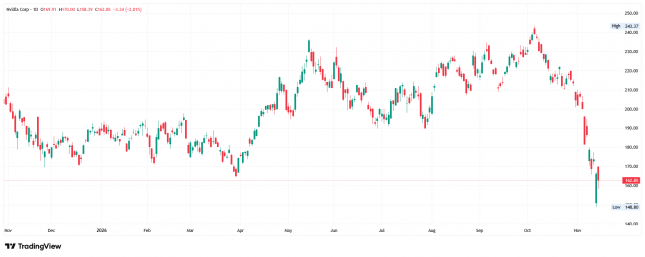
The main headline, of course, was the ousting of former Nvidia CEO Jensen Huang, which sent NVDA stock down nearly 13%. This marks its sixth weekly loss, clearing the path to shake hands with lows of US$148.80 – its lowest point since mid-2025. CFO Colette Kress will temporarily take the helm as interim CEO while the Board searches for a permanent replacement. However, I did recently read that Huang is discussing a potential return; this is doubtful, as he is under investigation!
The tech sell-off hit Asia overnight. Taiwan’s TAIEX has sunk more than 5%, and South Korea’s KOSPI shed nearly 4.0%, with MSCI’s broader Asian gauge down 1.9%. Nasdaq 100 and S&P 500 futures are also on the back foot, down 1.3% and 0.6% after erasing earlier gains, respectively.
Fed & Rates
Fed speak was on the up last week. Of note was Fed Governor Christopher Waller, who said that he was open to a 50 bp hike next month if the October CPI report showed core price pressures at 0.3%, and we got just that. Kansas City Fed President Jeff Schmid also said price pressures are running too hot and more work remains. While the OIS curve is not pricing in a weighty 50 bp increase for December’s Fed meeting, it is fully discounting a 25 bp hike, as I write.
On the data front, the October US CPI inflation report was hotter than expected. MM, headline inflation reached 0.4%, beating the 0.3% consensus, though it remained below September’s 0.6%; as I noted above, core came in above the 0.2% estimate and matched September’s print.
In rates markets, while I am sure there are other drivers, the two key determinants of yield pricing have been oil prices and AI sentiment. Rising (falling) oil prices translate to higher (lower) inflation, which often pushes the Fed to embark on a tightening (easing) cycle. I also see it as meaning that when the AI trade takes a hit, it can increase unemployment, which can have a knock-on effect on demand, thereby lowering inflationary pressures and prompting a dovish Fed.
Week Ahead
Macro focus this week kicks off with the October Canadian CPI inflation report today, followed by the September UK jobs report and October US retail sales figures on Tuesday. Wednesday welcomes the October UK CPI inflation release, along with minutes from the October Fed meeting. Then, on Thursday, October Australian jobs data hits the wires, followed by October UK retail sales on Friday.
For Canada’s CPI inflation, this has been a tricky print to trade given how contained underlying price pressures have been – the BoC’s preferred measures: CPI median and CPI trim. These have both circled around 2% since April, even as headline inflation has been lifted by energy. That leaves the market debating whether higher energy costs will spill into broader prices, and so far the evidence of that is thin. Unless we see marked deviations – median and trim coming in north of 2% – I do not see much tradable volatility from the CAD.
Away from data, Nvidia’s earnings are the big event Tuesday, and Anthropic’s expected listing at a valuation talked up to around US$1.5 trillion will further test AI appetite. President Trump also begins a trip to Asia, with a bilateral meeting with Xi Jinping expected Thursday.
Written by FP Markets Chief Market Analyst, Aaron Hill