Beijing Aims Stimulus at Housing Sector as Economic Indicators Flash Red
Beijing raised efforts to minimize the effects of US tariffs on China’s economy, eager to achieve the 5% GDP growth target for 2025. However, efforts to revive consumer sentiment and boost domestic consumption have failed to gain traction.
Economists have attributed historically low consumer sentiment and weakening private consumption to the effects of US tariffs on industrial production and housing sector woes.
On Monday, August 25, Beijing announced policy measures aimed at bolstering the housing sector. According to CN Wire, new housing policy adjustments in Shanghai, effective August 26, included:
- Easing housing purchase restrictions.
- Raising individual housing provident fund loan limits.
- Allowing withdrawal for down payments.
Additional measures included:
- Temporary property tax exemption for first homes purchased by eligible non-local resident families.
- Deduction of exemption area for second and subsequent home purchases by non-local resident families.
- Commercial personal home loans no longer differentiate between first and second homes.
The government reportedly stated:
“The move, to be effective Aug.26, is aimed at supporting the real estate market and meeting the housing needs of residents.”
The latest measures followed more disappointing housing sector data, forcing policymakers into action. Key real estate sector stats include:
- Real estate development fell 12% year-on-year, January to July.
- Residential housing sales areas declined by 4% year-on-year in July after declining 3.5% in June, with total sales dropping 6.5%.
- New home prices fell 0.3% month-on-month in July, mirroring June’s trend. From January to July, average home prices declined 4.5% year-on-year.
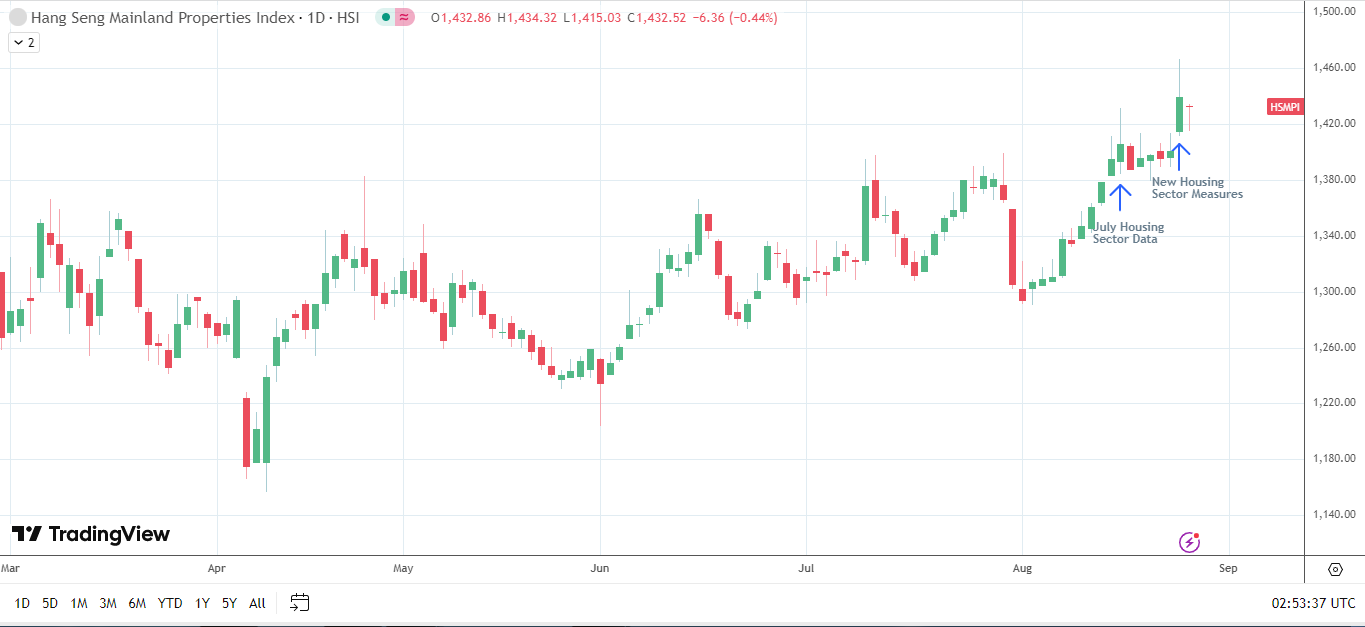
Investors reacted positively to Monday’s announcement. The Hang Seng Mainland Properties Index initially rallied 3.64% before easing back to close the session up 2.72%.
China Equity Markets Another Potential Trigger for Consumer Spending
Monday’s housing sector policy adjustments boosted investor sentiment, another crucial piece of the jigsaw puzzle.
Leading economist Hao Hong recently remarked on the potential effect of a Mainland China equity market recovery on consumer sentiment, stating:
“There is no quick fix to boosting household confidence except for a stock market rebound. This is a topic that we economists have been discussing in the closed door meetings in Beijing.”
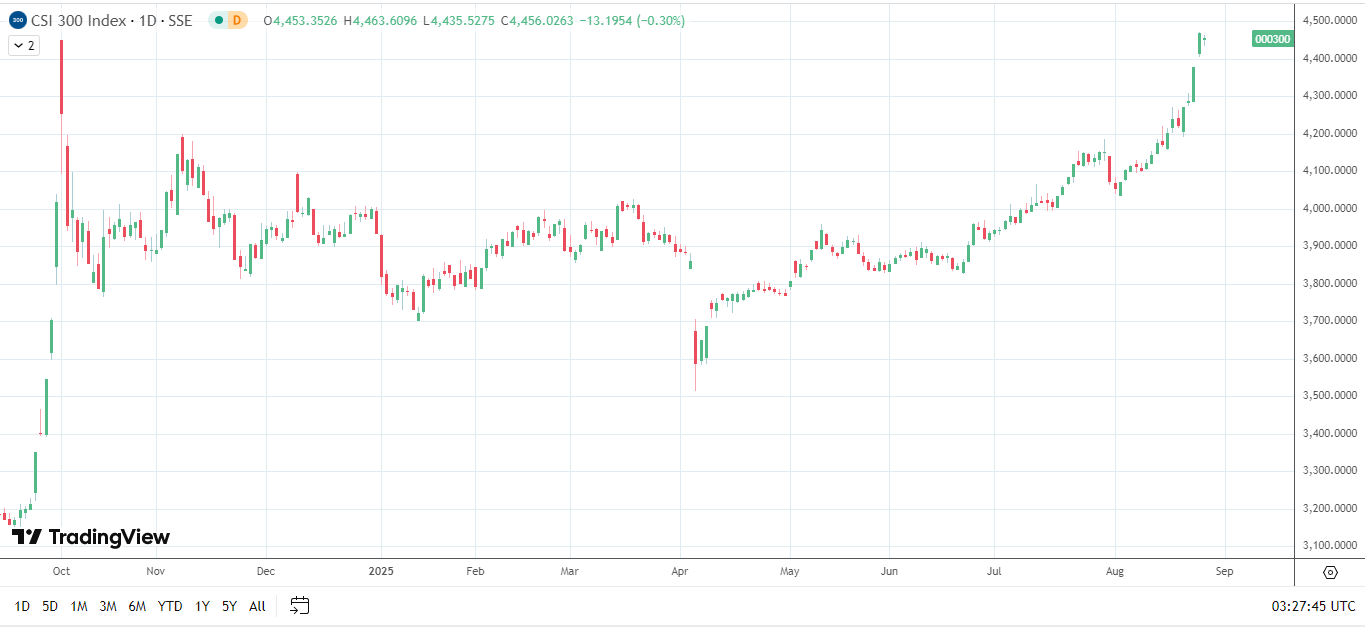
On Monday, August 25, the CSI 300 extended its winning streak, rising to a three-year high. Meanwhile, the Shanghai Composite Index soared to a 10-year high, potentially boosting consumer sentiment. However, Hao Hong warned retail participation is measured, contrasting with last September’s rally.
Nevertheless, Beijing’s efforts to bolster the housing sector and the broader economy could drive retail participation.
CN Wire reported:
Hong Kong Hang Seng Price Forecast
Every new Hong Kong Hang Seng analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Hong Kong Hang Seng forecasts“Analysts say the absence of retail euphoria in China’s stock rally may give the market greater sustainability, even as the Shanghai Composite hit a decade high. The CSI 300 Index’s 10-day volatility remains near this year’s lows, suggesting measured positioning by investors, unlike past policy-driven surges.”
Hopes of Fresh Policy Measures Key to Mainland Stock Market Rallies
Beijing’s latest housing sector policy adjustments aligned with market expectations of a ramp-up of government policy support, lifting Mainland-listed stocks.
Last week, China’s premier Li Qiang pledged to boost spending, stabilize the housing market, and address labor market strains. Beyond the housing sector, unemployment remains a key concern. Youth unemployment rose from 14.5% in June to 17.8% in July, the highest in 11 months. The national unemployment rate sits at 5.2%.
Economists Expect More Policy Support as China’s Economy Loses Momentum
Natixis Asia Pacific Chief Economist Alicia Garcia Herrero recently remarked on the need for more government support, stating:
“China can reach its 2025 growth target but with even more stimulus and the second half will be tougher. All in all, while the Chinese economy has a greater likelihood of meeting the government’s growth target, there are significant uncertainties down the road. Despite foreseeable headwinds from trade friction and persisting deflation, the government does have more bullets for further stimulus if needed.”
The Kobeissi Letter remarked on China’s economy, underscoring the pressing need for policy support, stating:
“China’s economy is slowing. Fixed-asset investment growth in the first 7 months of 2025 slowed to +1.6%, the weakest in over 5 years. Property investment declined -12.0%, the largest drop since the 2020 pandemic low. Retail sales grew +3.7% in July, down from +4.8% in June, marking the slowest pace this year. Industrial production also slowed, rising +5.7% in July compared with +6.8% in June, the slowest rate since November.”
Credit demand also deteriorated, highlighting Beijing’s challenge to revive consumption, and noting:
“Growth in Yuan-denominated new loans contracted for the first time in 20 years in July.”
Mainland Stock Markets Reach Highs on Stimulus Bets
On Tuesday, August 26, Mainland China’s CSI 300 and the Shanghai Composite Index fell 0.30% and 0.18%, respectively, putting a four-day winning streak at risk. Despite the morning session losses, the indexes remain close to the previous session’s highs.
Despite hitting multi-year highs, both indexes trade well below their all-time peaks, signaling potential room for an extended bull run.
- CSI 300: +9.41% in August, +13.25% YTD.
- Shanghai Composite: +8.47% in August, +15.62% YTD.
- Hang Seng Index: +28.6% YTD, outperforming both Mainland equity markets and the Nasdaq (+11.07% YTD).
Trade headlines and Beijing’s next stimulus measures remain key. However, an escalation in US-China trade tensions and delays in policy support could derail the rally.
The Road Ahead: Trade Talks and Stimulus
US-China trade talks and Beijing’s policy measures will be pivotal for market trends in the coming weeks. On Tuesday, August 26, news broke of China’s top trade negotiator Li Chenggang planning a return to the US to resume trade talks.
However, upcoming economic indicators will also affect sentiment. Industrial profit numbers for July will draw interest on Wednesday, August 27, ahead of August’s NBS private sector PMIs on Sunday, August 31. Weak numbers could pressure Beijing to deliver further policy support.
Track our real-time updates on China trade policy and equity market trends, and consult our economic calendar.