


After a busy session on the Asian economic calendar, it was a relatively busy Eurozone economic calendar this morning.
The ECB’s Financial Stability Review was in focus ahead of finalized October inflation figures for the Eurozone.
ECB Financial Stability Review
Salient points from the ECB’s Financial Stability Review “Overview” included:
Near-term pandemic risks lessen, but vulnerabilities ahead build up.
- Improved economic conditions have reduced near-term tail risks to financial stability.
- Supply disruptions and rising energy prices pose risks to inflation and the economic recovery.
- Corporate default risk and bank losses are likely to be lower than feared earlier.
- Near-term debt sustainability concerns have been alleviated by favorable financial conditions.
- Further ahead, vulnerabilities from growing stretch in property and financial markets, risk-taking by non-banks, and elevated sovereign and corporate debt are building up.
- Tighter macroprudential policies can address vulnerabilities ahead, notably for property markets in some countries.
- Strengthening the regulatory framework for banks and non-banks, and managing climate risks, will enhance long-term resilience of the financial system.
Eurozone Inflation
In October, the Eurozone’s annual rate of inflation accelerated from 3.4% to 4.1%, which was in line with prelim figures.
The Eurozone’s annual core rate of inflation picked up from 1.9% to 2.0%, which came up short of a prelim 2.1%.
According to Eurostat,
- The lowest annual rates of inflation were registered in Malta (1.4%), Portugal (1.8%), and Greece (2.8%).
- Lithuania (8.2%) and Estonia (6.8%) had the highest annual rates of inflation in October.
- The highest contribution to the annual rate of inflation came from energy (+2.21 percentage points).
- There were also contributions from:
- Services (+0.86pp)
- Non-energy industrial goods (+0.55pp)
- Food, alcohol, & tobacco (+0.43pp).
Market Impact
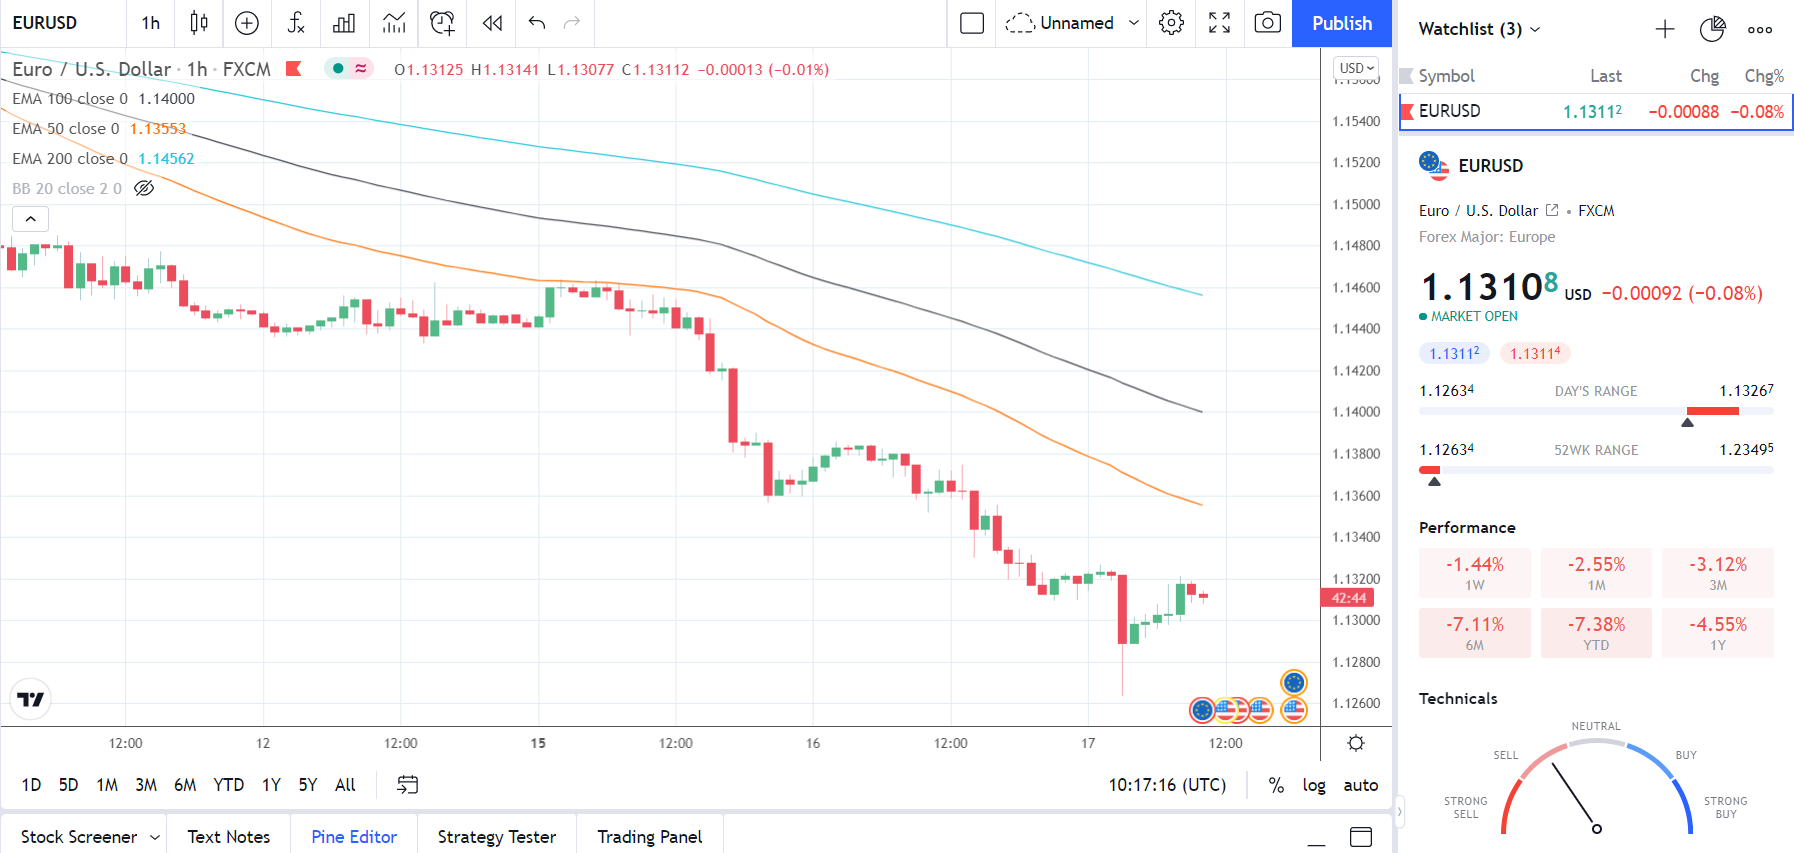
Ahead of today’s stats, the EUR had risen to a pre-stat and current day high $1.13267 before falling to a pre-stat and current day low $1.12634.
In response today’s Financial Stability Review and inflation figures, the EUR rose to a post-release high $1.13210 before easing back.
At the time of writing, the EUR was down by 0.08% to $1.13112.
Next Up
Housing sector data from the U.S that should have a muted impact on market risk sentiment.
On the monetary policy front, however, both ECB and FOMC member chatter will draw interest.
ECB member Schnabel is due to speak ahead of FOMC members Williams, Bowman, Mester, Daly, and Waller.
Late in the U.S session, ECB President Lagarde is also due to deliver a speech.
The markets will be looking for any shift in position on inflation…