


Economic Calendar:
Friday, 29th January
French Consumer Spending (MoM) (Dec)
French GDP (QoQ) (Q4) 1st Estimate
Spanish GDP (QoQ) (Q4) 1st Estimate
Spanish CPI (YoY) (Jan) Prelim
German GDP (QoQ) (Q4)
German Unemployment Change (Jan)
German Unemployment Rate (Jan)
The Majors
It was a relatively bullish day for the European majors on Thursday. The CAC40 rose by 0.93%, with the DAX30 and the EuroStoxx600 ending the day up by 0.33% and by 0.10% respectively.
U.S corporate earnings supported airline stocks in spite of lockdown measures and travel restrictions in parts of Europe.
With economic data from the Eurozone limited to inflation figures, U.S stats also provided support on the day.
The gains were minor, however, with the economic outlook looking bleak as lockdown measures continue to hit the Eurozone economy.
The Stats
It was a relatively quiet day on the economic calendar, prelim January inflation figures for Germany were in focus late in the session.
In January, consumer prices rose by 0.8%, following a 0.5% increase in December. Economists had forecast a 0.4% rise.
According to Destatis,
- Year-on-year, consumer prices rose by 1.0%, reversing a 0.3% decline from December.
- Prices for goods increased by 0.6%, with prices for services jumping by 1.5%.
- Energy prices fell by 2.3%, while food prices increased by 2.2%.
From the U.S
It was a busier day on the U.S economic calendar.
4th quarter GDP numbers were in focus along with the weekly jobless claim figures.
In the 4th quarter, the U.S economy expanded by 4%, following the 2nd quarter’s 33.4% recovery. Economists had forecast growth of 4% in the quarter.
Employment figures were skewed to the positive. In the week ending 22nd January, initial jobless claims came in at 847k. In the previous week, initial jobless claims had stood at 914k.
The Market Movers
For the DAX: It was a bullish day for the auto sector on Thursday. Daimler rallied by 3.44%, with Continental and Volkswagen rising by 1.58% and 1.01% respectively. BMW saw a more modest 0.04% gain on the day.
It was also a bullish day for the banks. Deutsche Bank rose by 1.90%, with Commerzbank rallying by 6.24%.w
From the CAC, it was a bullish day for the banks. BNP Paribas rise by 1.68%, with Credit Agricole and Soc Gen gaining 1.51% and 1.32% respectively.
It was also a bullish day for the French auto sector. Stellantis NV rose by 2.36%, with Renault rallying 3.45%.
Air France-KLM and Airbus SE ended the day with gains of 3.18% and 0.94% respectively.
On the VIX Index
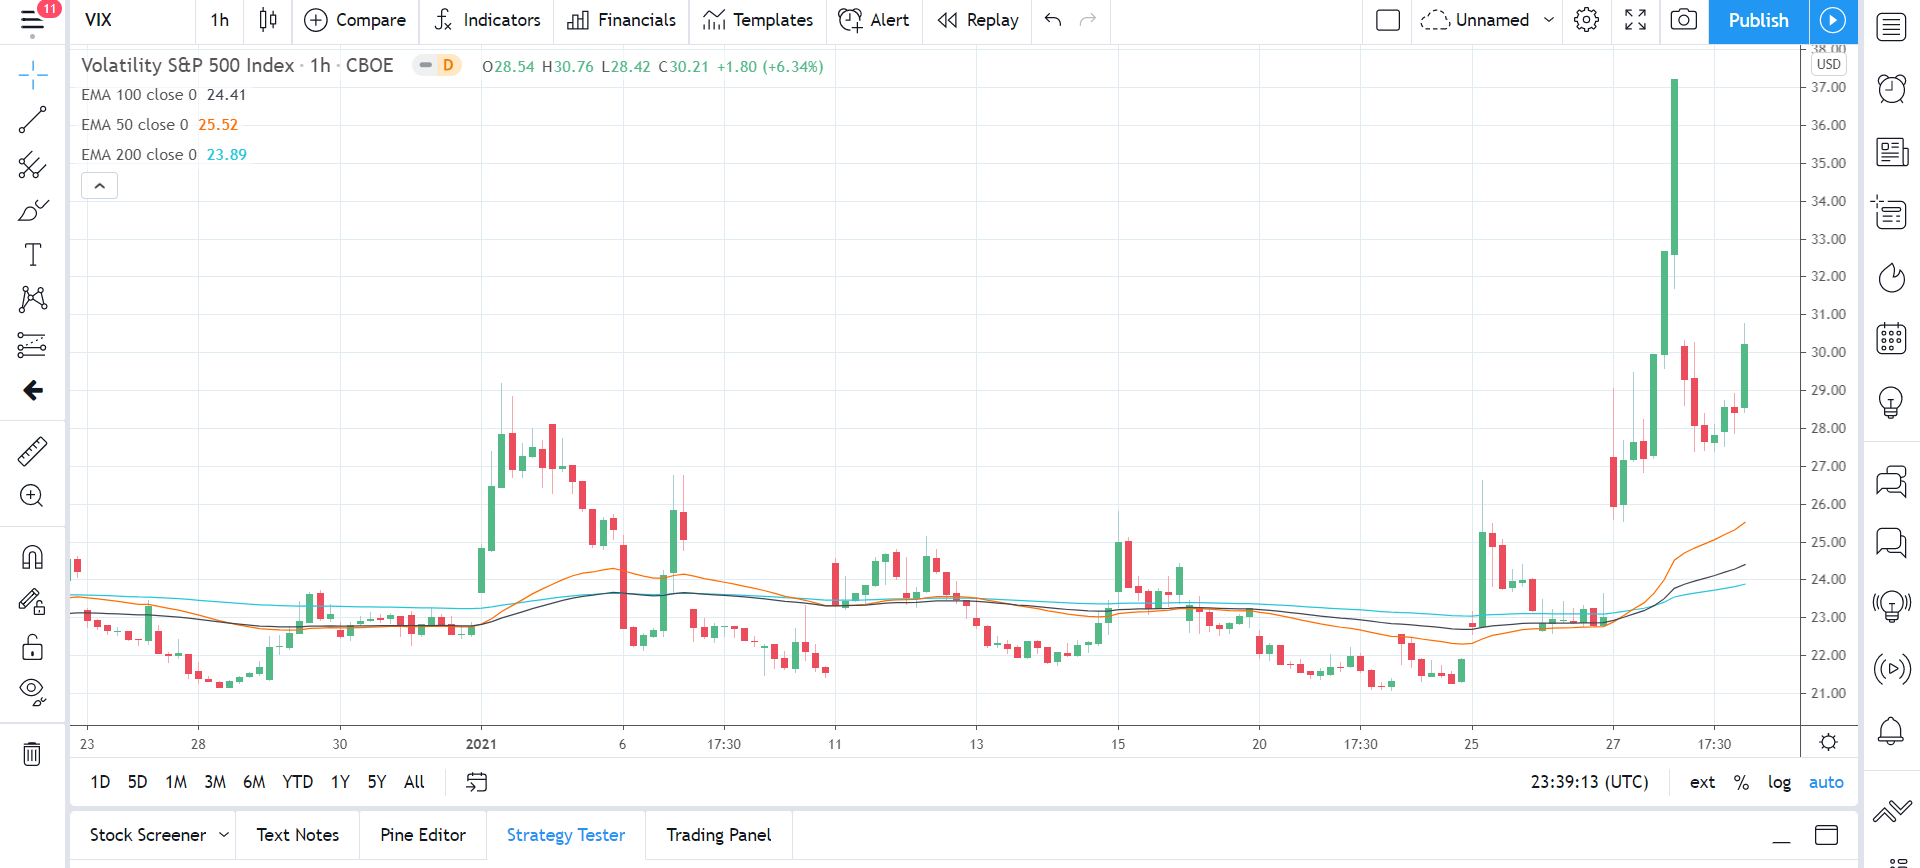
It was back into the red for the VIX on Thursday. Partially reversing a 61.64% surge from Wednesday, the VIX slid by 18.81% to end the day at 30.21.
The Dow and the S&P500 rose by 0.99% and by 0.98% respectively, with the NASDAQ gaining 0.50%.
The Day Ahead
It’s a busy day ahead on the European economic calendar. French and German 4th quarter GDP numbers will be in focus along with German unemployment figures for December.
French consumer spending and Spanish inflation and GDP figures are also due out. We would expect these stats to have a muted impact on the majors, however.
From the U.S, December personal spending and inflation figures will draw interest late in the session.
Away from the economic calendar, COVID-19 news and chatter from Capitol Hill will remain key drivers.
The Futures
In the futures markets, at the time of writing, the Dow Mini was down by 26 points.
For a look at all of today’s economic events, check out our economic calendar.