



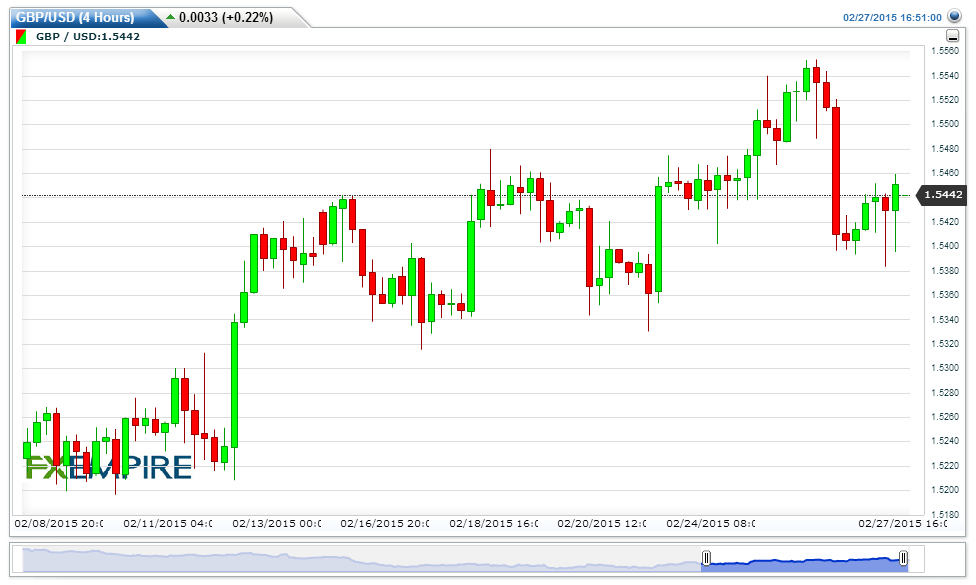
The GBP/USD closed the month higher than expected but off its high of 1.5595 just days ago. The pound closed at 1.5438 as the US dollar rally was hard to compete against. UK GDP growth looks well positioned to reaccelerate over the course of 2015 after decelerating in late 2014. Consumer spending will remain the main engine of growth as household real income gets a boost from lower inflation, coupled with solid job creation and rising wage inflation. Business investment should also be solid, though held back to some extent by cutbacks in oil and gas investment. Furthermore, UK export growth should benefit from the firming economic growth prospects in Europe, which should translate into stronger demand for UK products and services. In this context, it is not unreasonable to expect UK GDP growth to approach 3% y/y in 2015. CPI inflation has continued to surprise on the downside and looks set to bottom around zero, or possibly lower.
The Federal Reserve remains on a path to hike interest rates at its June 2015 meeting with the risks skewed to later. Fed Chair Yellen’s monetary policy report to Congress on February 24-25 pointed to the Fed dropping the term ‘patient’ from its March statement and replacing it with language reflecting so-called data dependency. Such a move would put the June meeting into play for a rate hike (failure to remove the word ‘patient’ at that meeting would cause us to push our rate hike call out further). The dilemma for the Fed is whether or not economic growth during H1 2015 will suffice to justify a rate hike: labor data are already strong enough, and the Fed has implied that it thinks that low inflation is a transitory phenomenon tied to low oil prices. Q1 GDP matters quite a bit.
FxEmpire provides in-depth analysis for each currency and commodity we review. Fundamental analysis is provided in three components. We provide a detailed monthly analysis and forecast at the beginning of each month. Then we provide more recent analysis and information in our weekly reports and we provide daily updates and outlooks.
Upcoming Economic Events that you should be monitoring:
|
Time |
Cur. |
Event
Actual
Forecast
Previous
Sunday, March 1, 2015
CNY
Manufacturing PMI (Feb)
49.7
49.8
Monday, March 2, 2015
CNY
HSBC Manufacturing PMI
50.1
EUR
German Manufacturing PMI
50.9
50.9
GBP
Manufacturing PMI (Feb)
53.4
53.0
EUR
CPI (YoY) (Feb)
-0.5%
-0.6%
USD
ISM Manufacturing PMI
53.1
53.5
Tuesday, March 3, 2015
AUD
Interest Rate Decision (Mar)
2.00%
2.25%
GBP
Construction PMI (Feb)
59.0
59.1
CAD
GDP (MoM) (Dec)
-0.2%
Wednesday, March 4, 2015
AUD
GDP (YoY) (Q4)
2.6%
2.7%
AUD
GDP (QoQ) (Q4)
0.7%
0.3%
GBP
Services PMI (Feb)
57.5
57.2
USD
ADP Nonfarm Employment
220K
213K
USD
ISM Non-Manufacturing
56.5
56.7
CAD
Interest Rate Decision
1.00%
0.75%
Thursday, March 5, 2015
AUD
Retail Sales (MoM) (Jan)
0.4%
0.2%
GBP
Interest Rate Decision (Mar)
0.50%
0.50%
EUR
Interest Rate Decision (Mar)
0.05%
CAD
Ivey PMI (Feb)
50.0
45.4
Friday, March 6, 2015
USD
Nonfarm Payrolls (Feb)
240K
257K
USD
Unemployment Rate (Feb)
5.6%
5.7%
Sunday, March 8, 2015
CNY
Trade Balance (Feb)
60.03B
Tuesday, March 10, 2015
CNY
CPI (YoY) (Feb)
0.8%
Wednesday, March 11, 2015
CNY
Industrial Production (YoY)
7.9%
GBP
Manufacturing Production
0.1%
Thursday, March 12, 2015
NZD
Interest Rate Decision
3.50%
3.50%
AUD
Employment Change (Feb)
-12.2K
USD
Core Retail Sales (MoM)
0.4%
-0.9%
USD
Retail Sales (MoM) (Feb)
0.4%
-0.8%
Friday, March 13, 2015
USD
PPI (MoM) (Feb)
0.1%
-0.8%
CAD
Employment Change (Feb)
35.4K
Tuesday, March 17, 2015
EUR
German ZEW Economic
53.0
EUR
CPI (YoY) (Feb)
Wednesday, March 18, 2015
GBP
Average Earnings Index
2.1%
GBP
Claimant Count Change
-38.6K
Thursday, March 19, 2015
NZD
GDP (QoQ) (Q4)
1.0%
Friday, March 20, 2015
CAD
Core Retail Sales (MoM)
-2.3%
Saturday, March 21, 2015
All Day
Japan – Spring Equinox Day


