Broad Indexes Hit Record Highs on Cooler Inflation Data
US equity markets surged to fresh all-time highs Friday morning as September’s Consumer Price Index came in below expectations, reinforcing trader conviction that the Federal Reserve will continue its rate-cutting cycle.
The Dow Jones Industrial Average climbed more than 1.0%, while the S&P 500 gained 0.92% and the Nasdaq Composite jumped 1.2%. All three major indexes reached new intraday records during the session and are tracking weekly gains exceeding 2%.
The delayed CPI reportshowed headline inflation rising 3% year-over-year, below the 3.1% forecast, with the monthly increase of 0.3% also coming in under the expected 0.4%. Core CPI registered 0.2% monthly and 3% annually, both lighter than the 0.3% and 3.1% estimates respectively.
CPI Report Clears Path for Continued Fed Easing
September’s inflation figures delivered precisely what traders needed to maintain confidence in further monetary policy loosening. The report represents the first major economic release since the government shutdown began, giving investors a long-awaited pulse check on the economy. Around 99% of bets remain on a quarter-point cut next week, while around 96% of traders expect another slash in December.
The ongoing government shutdown has created a data drought, with most economic releases including weekly and monthly jobs figures remaining postponed, giving the Fed little new information to challenge its current course.
Technology and Financials Lead Sector Performance
The Technology sector is dominating morning action, surging 1.24% to 5,768.66, benefiting from strong semiconductor momentum and AI-related optimism.
Financials are posting the second-strongest gain at 1.15%, reaching 884.04, while Utilities are advancing 1.17% to 463.96. Communication Services is climbing 0.99% to 426.35.
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecastsEnergy is bucking the trend, declining 0.51% to 678.19, while Materials is slipping 0.28% to 564.37.
Intel and Ford Lead Stock Movers on Earnings Beats
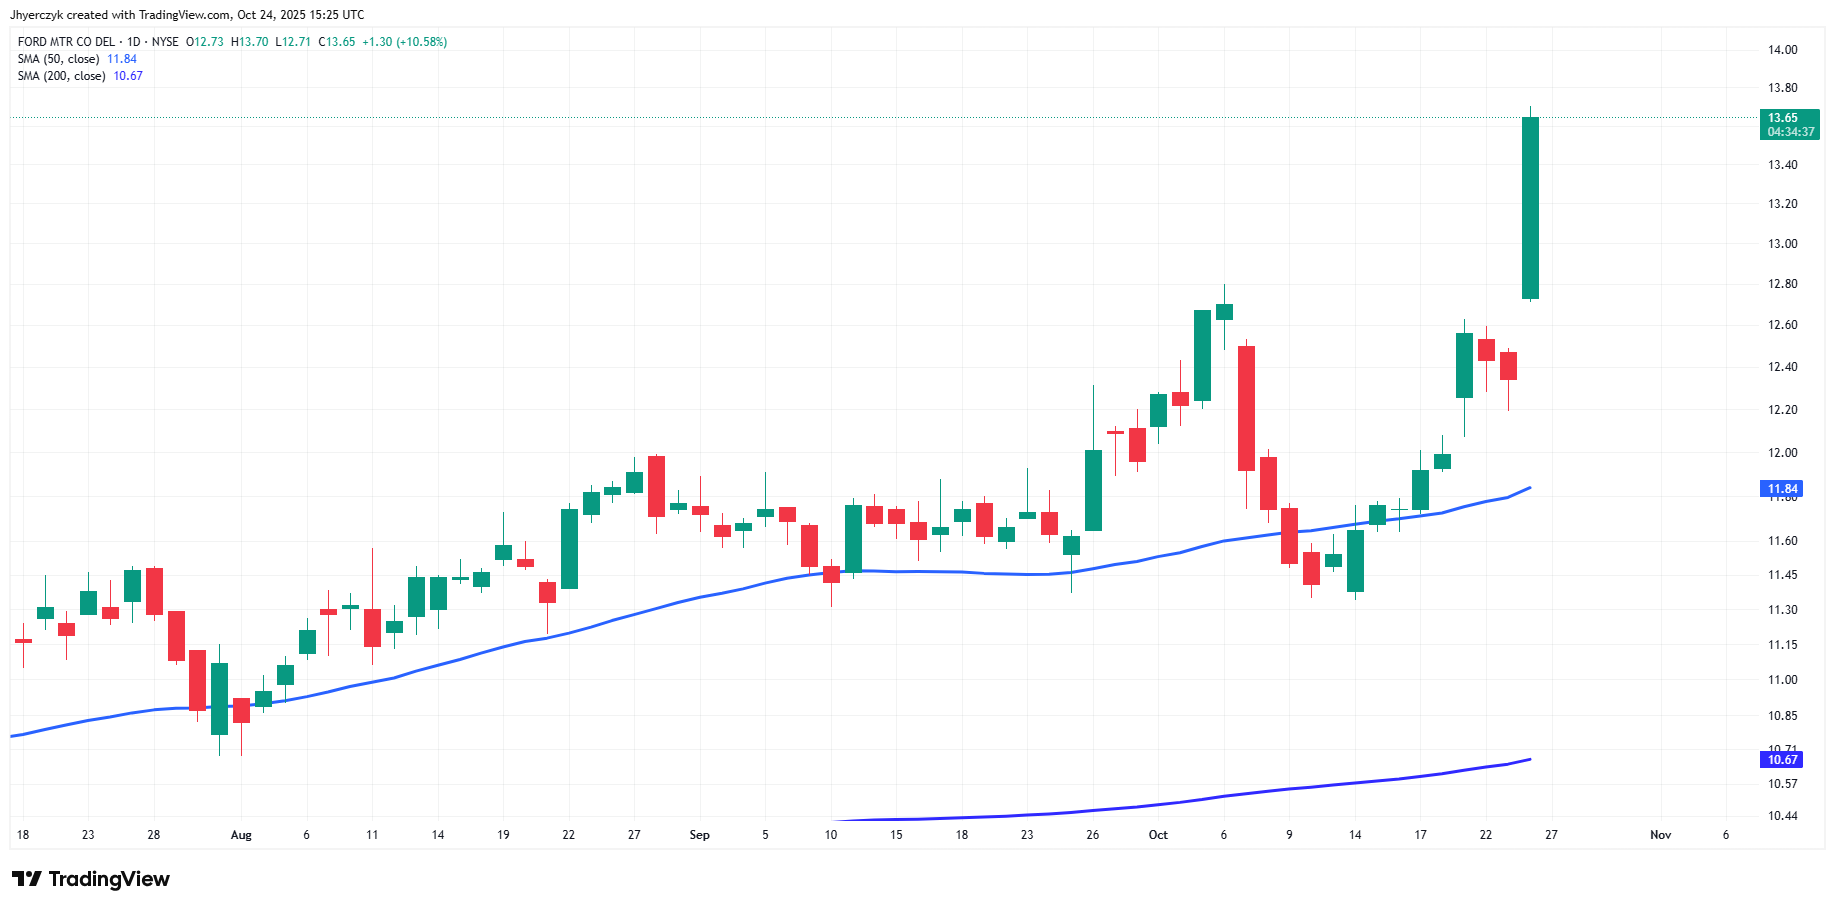
Ford Motor is delivering the session’s most impressive gain, soaring over 10% in early trading after third-quarter earnings exceeded expectations and the Wall Street Journal reported that key supplier Novelis will reopen its aluminum plant ahead of schedule following a fire.
The automaker projects a $1.5 billion to $2.0 billion adjusted EBIT headwind for 2025 from the plant closure, but expects to mitigate at least $1 billion in 2026, bringing the net impact between 2025 and 2026 to $1 billion or less.
Intel shares jumped nearly 6% after third-quarter revenue topped estimates.
Semiconductor stocks are showing broad strength with AMD gaining 6.992%, Micron advancing 4.789%, and IBM climbing 4.679%. Deckers Outdoor is plummeting 11.469% to 90.78.
Alphabet Advances on Major Anthropic Chip Agreement
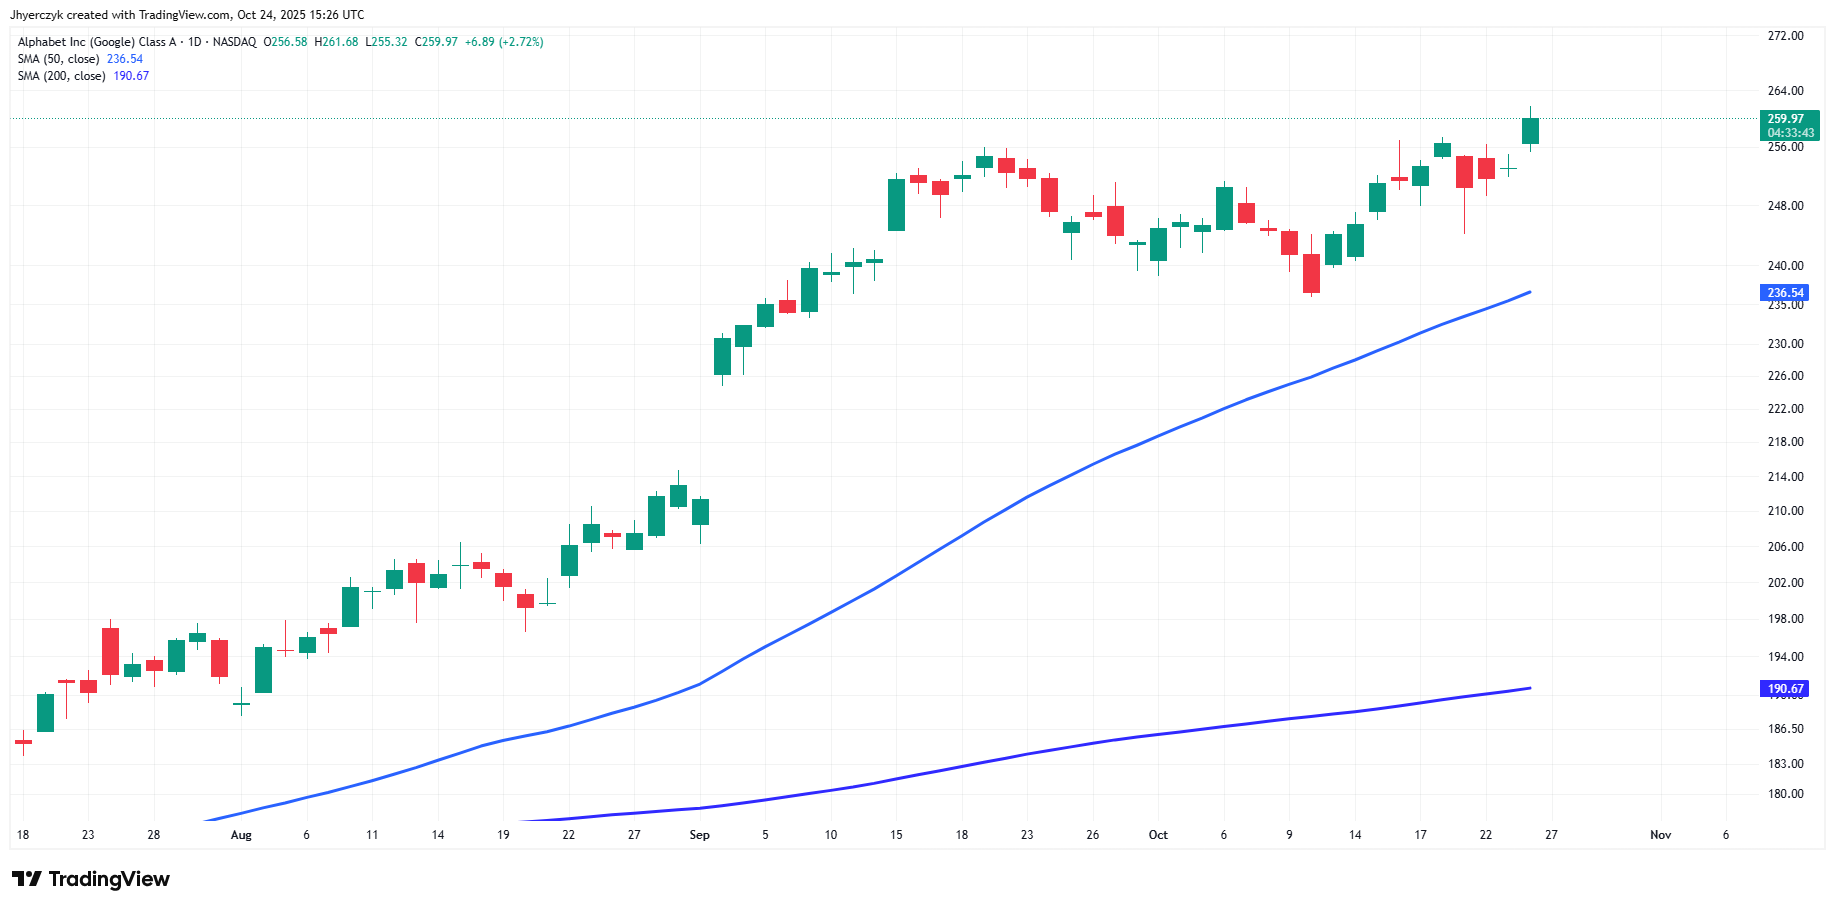
Alphabet shares are moving higher as Google announced a deal to supply Anthropic with up to one million custom TPU chips. DA Davidson analyst Gil Luria estimates the TPU business combined with Google’s DeepMind AI segment to be worth $900 billion and “arguably one of Alphabet’s most valuable businesses.”
Consumer Sentiment Weakens Despite Inflation Data
The University of Michigan consumer sentiment index posted a reading of 53.6, missing the 54.9 estimate and down 24% year-over-year. While one-year inflation expectations edged down to 4.6%, five-year outlook climbed to 3.9%, the highest since June.
Strong Earnings Momentum Supports Bullish Outlook
Third-quarter earnings season continues its exceptional performance with 87% of reporting companies beating earnings estimates and 82% topping revenue expectations. S&P 500 earnings are tracking 10.4% year-over-year growth.
With cooler inflation clearing the path for continued Fed easing, record index levels, and robust earnings momentum heading into next week’s busiest reporting period featuring five Magnificent 7 companies, the near-term outlook remains decisively bullish.
More Information in our Economic Calendar.