Copper
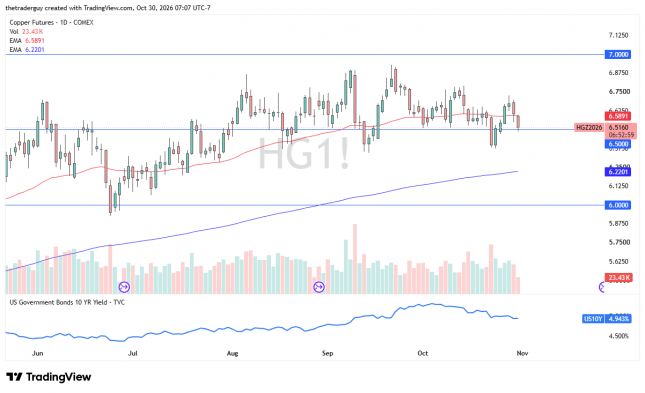
The copper market entered Friday with an uneven producer picture in the background. The market had settled at $6.60 during the previous session, but now finds itself under even more selling pressure as we are dancing around the $6.50 level.
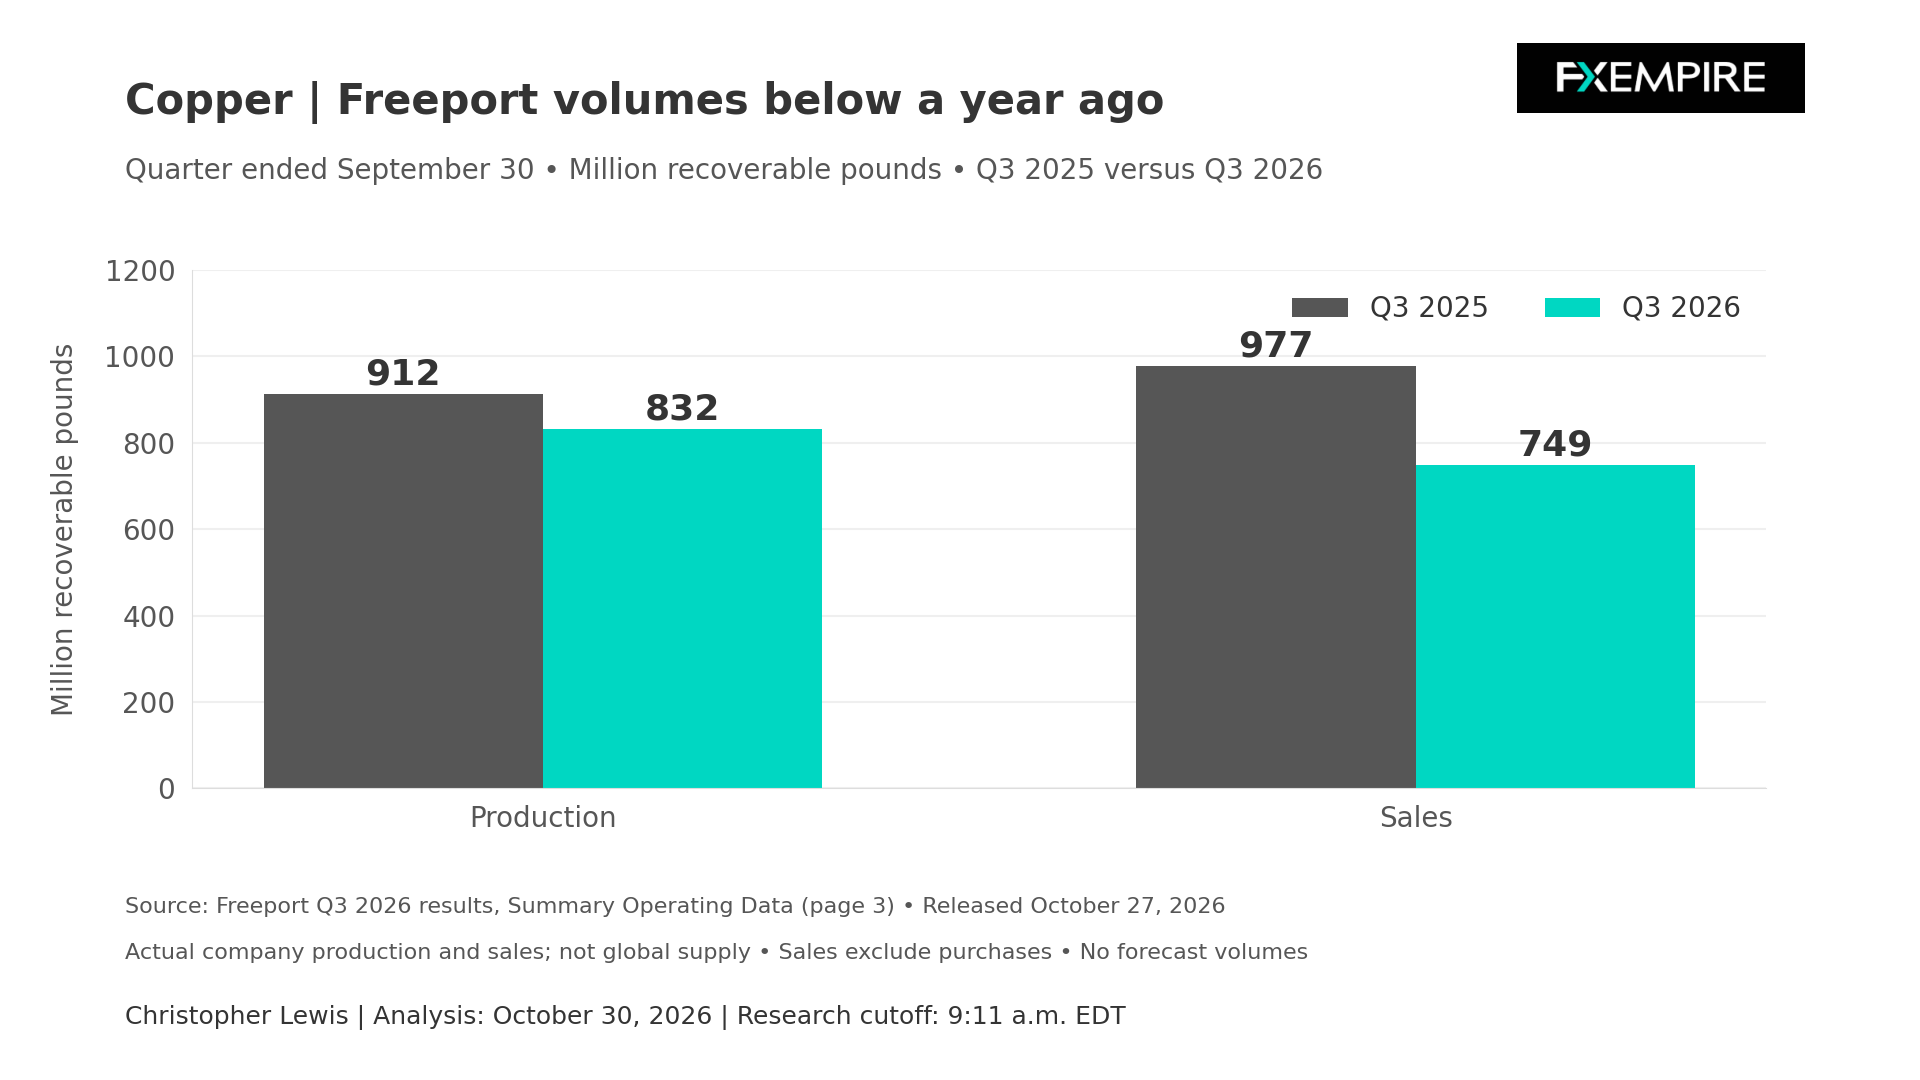
The October 27 Freeport report showed third-quarter copper production of 832 million pounds, compared with 912 million a year earlier. Sales, excluding purchases, were 749 million pounds versus 977 million. This describes one major producer’s quarterly operations, but the gap between production and sales makes delivery execution worth watching. More mined metal doesn’t necessarily mean the equivalent in deliveries, and I think that’s the question that we have right now.
The Employment Cost Index showed civilian compensation costs rising 0.8% in America this morning, so inflation is still a problem. Copper isn’t really a hedge against inflation when rates offer real yields, and that’s what’s dragging it down right now. Between here and $6.40, I’m looking for some type of bounce to buy again. I think we stay neutral, but more positive-leaning than anything else due to longer-term interest.
EUR/USD
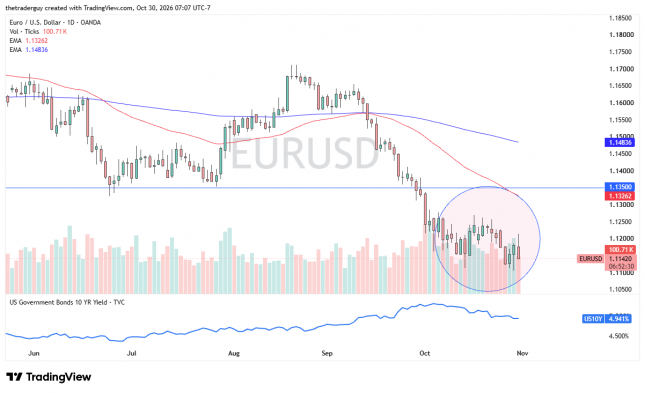
In the European market, the euro tried to rally a bit during the trading session. Today, third-quarter euro area GDP was released, with the flash estimate coming in at 0.4% quarter-on-quarter, down from 0.6% during the previous quarter. That being said, it’s also worth noting that the ECB held its deposit rate at 2.5% yesterday. That was not a huge surprise; it was expected.
Its statement did warn that higher energy prices posed upward inflation risk and downward growth risk—not a combination we want. So, with that being the case, this is a market that I think we should continue to fade rallies. We’ve already seen that today. If we can break below 1.11, I’ll be aiming for 1.10. Full disclosure: I’m already short of this market and have no interest in buying it.
USD/JPY
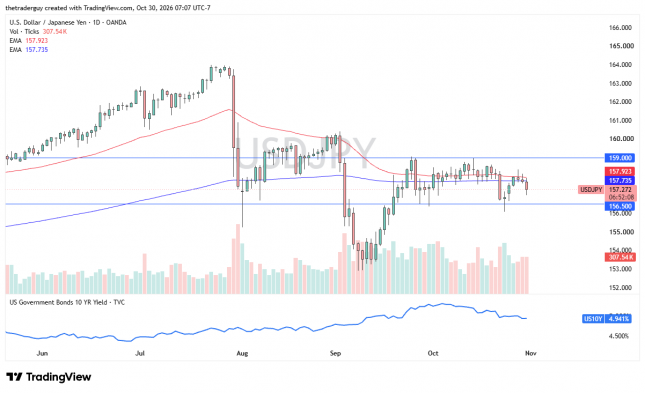
The dollar-yen has fallen during the day, and that’s not a huge surprise. The Bank of Japan retained its overnight call rate of 1.25% by an 8-to-1 vote. The dissenter actually wanted to raise rates. That’s a little bit interesting. The bank also approved a higher annual pace for ETF sales, with approximately ¥860 billion coming into the picture. Of course, the Federal Reserve decision was to hold.
So, we find ourselves just kind of hanging out in the same area. I like the idea of buying dips. I do think, ultimately, the interest rate differential plays out. The ¥156.50 level is our short-term floor, and the ¥159 level is our short-term ceiling. I plan on playing the range until told to do otherwise by the market itself.
Copper Price Forecast
Every new Copper analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Copper forecastsAUD/USD
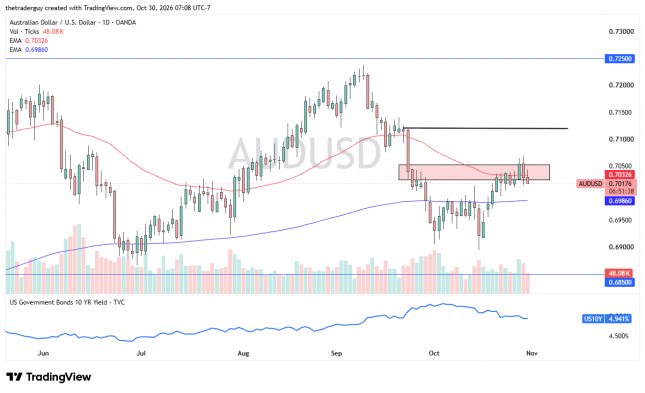
The Australian dollar tried to rally, but then it fell during the trading session, despite the fact that Australia has one of the higher cash rate targets. This is a market that will be looking at the next RBA meeting on November 3.
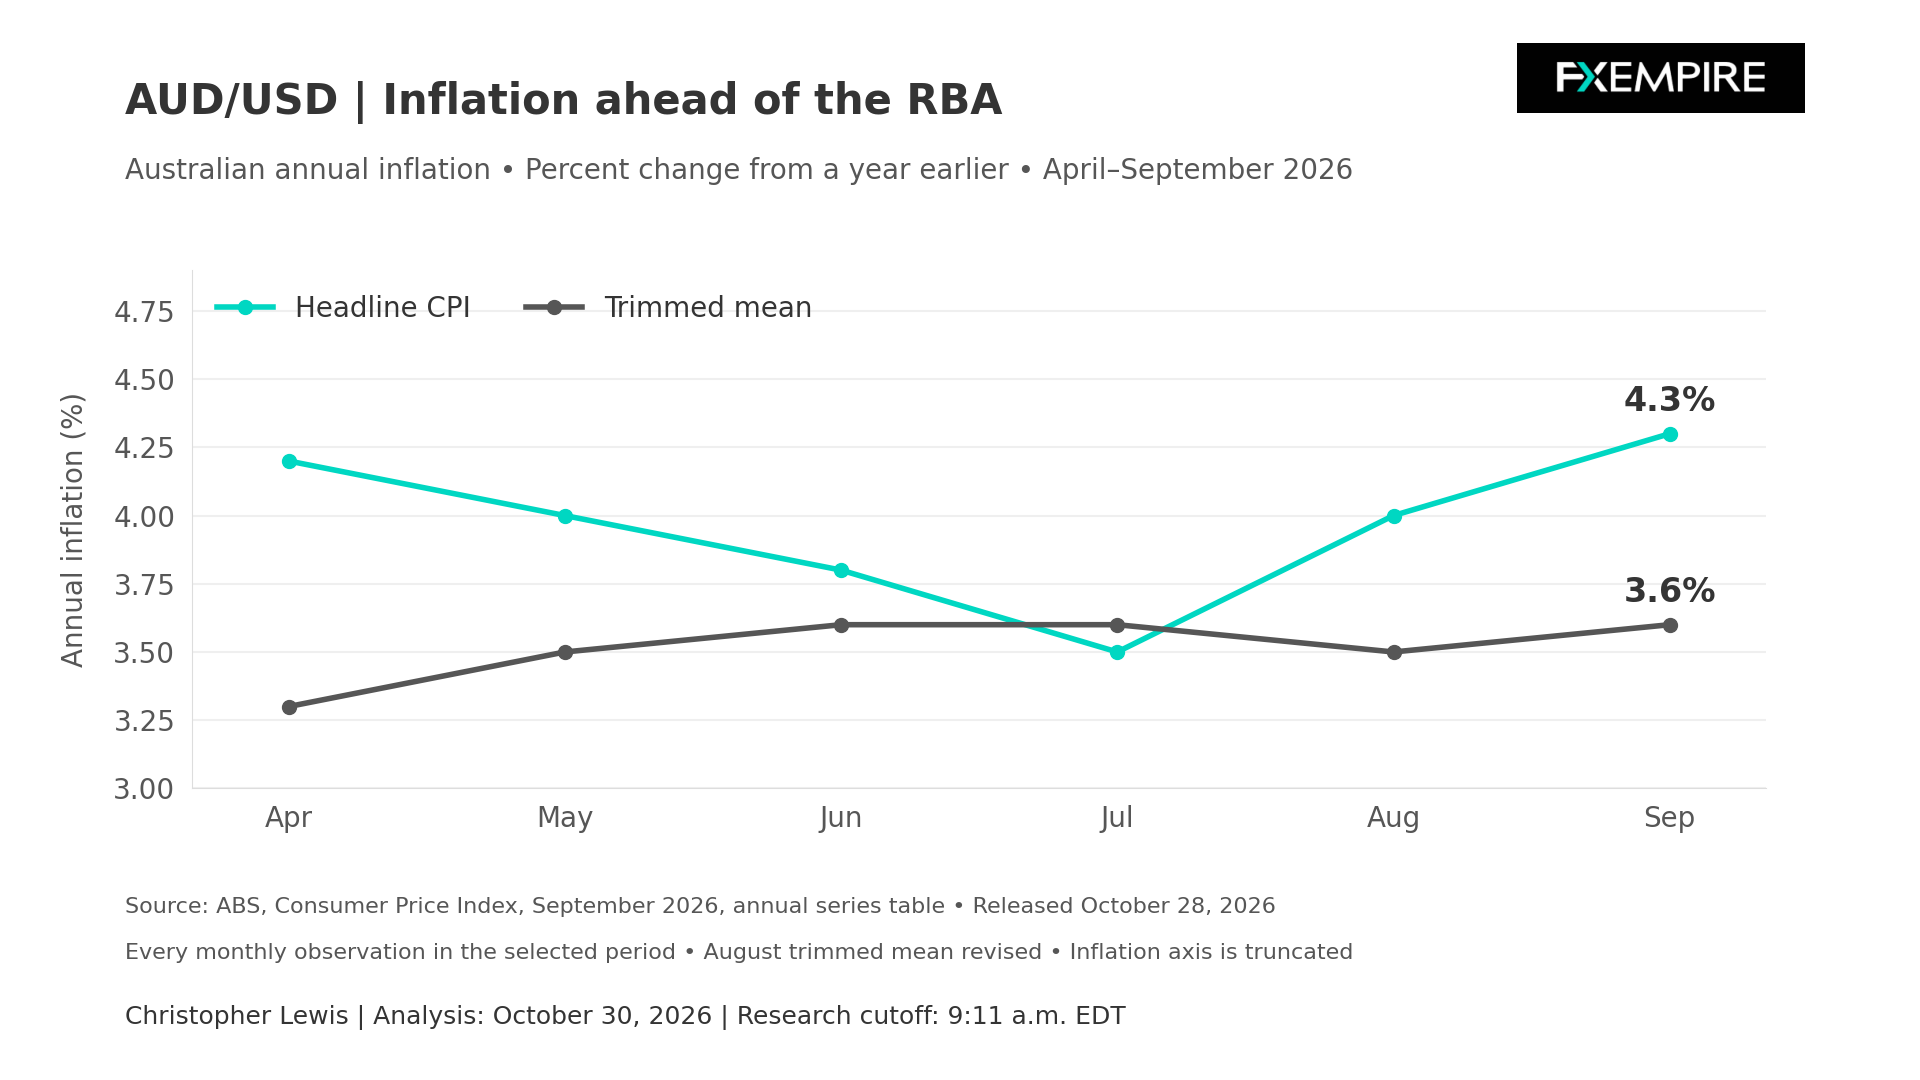
Its CPI report, released October 28, showed annual headline inflation of 4.3%, up from 4% in August. That’s not good. That being said, though, the market is probably going to be watching that statement very closely, and it’s probably difficult to own the Aussie between now and then because, even if they do raise rates, the question is: will energy be a factor?
Energy is starting to become something that a lot of these central banks are talking about. In the short term, if we were to break down below 0.70, I’d have a go at the downside for a small day trade, probably 50 pips or so. I think this has the likelihood to stay range-bound today, but it is worth noting that the last couple of candlesticks are trying to create some type of short-term range.