Stocks Mixed Midday as Tariff Uncertainty and Weak Jobs Data Weigh on Sentiment
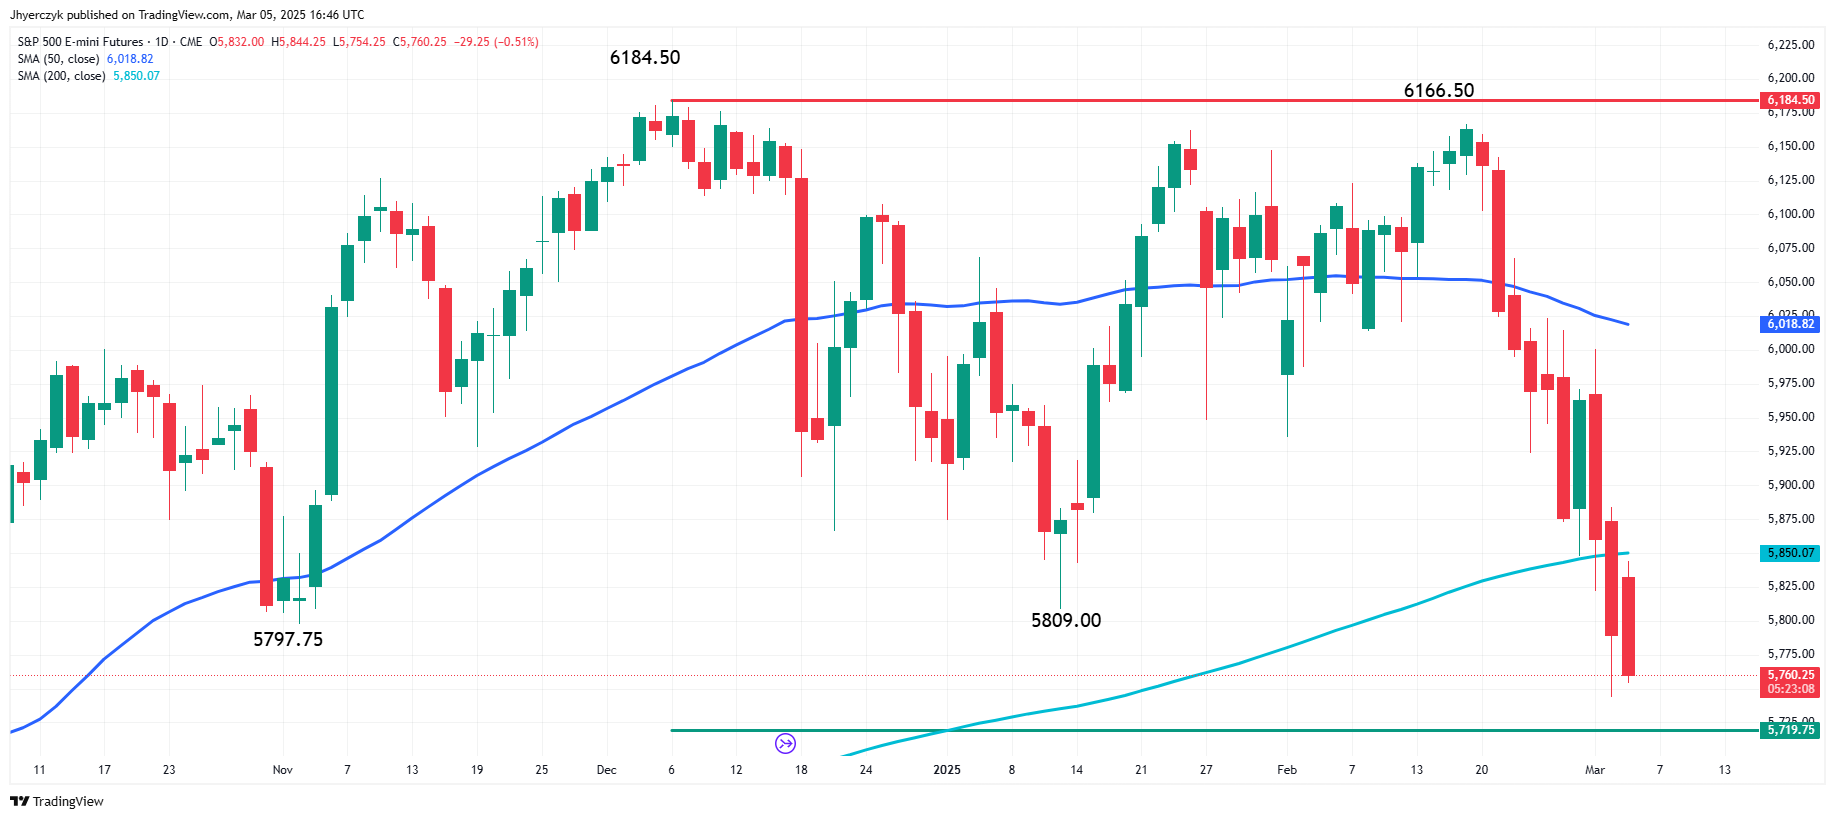
Stocks struggled for direction Wednesday as traders weighed conflicting economic data and ongoing tariff concerns. The S&P 500 and Nasdaq Composite hovered near the flatline, each slipping 0.1%, while the Dow Jones Industrial Average managed a modest 44-point gain after steep losses in the prior two sessions.
Are Tariff Developments Providing Any Clarity?
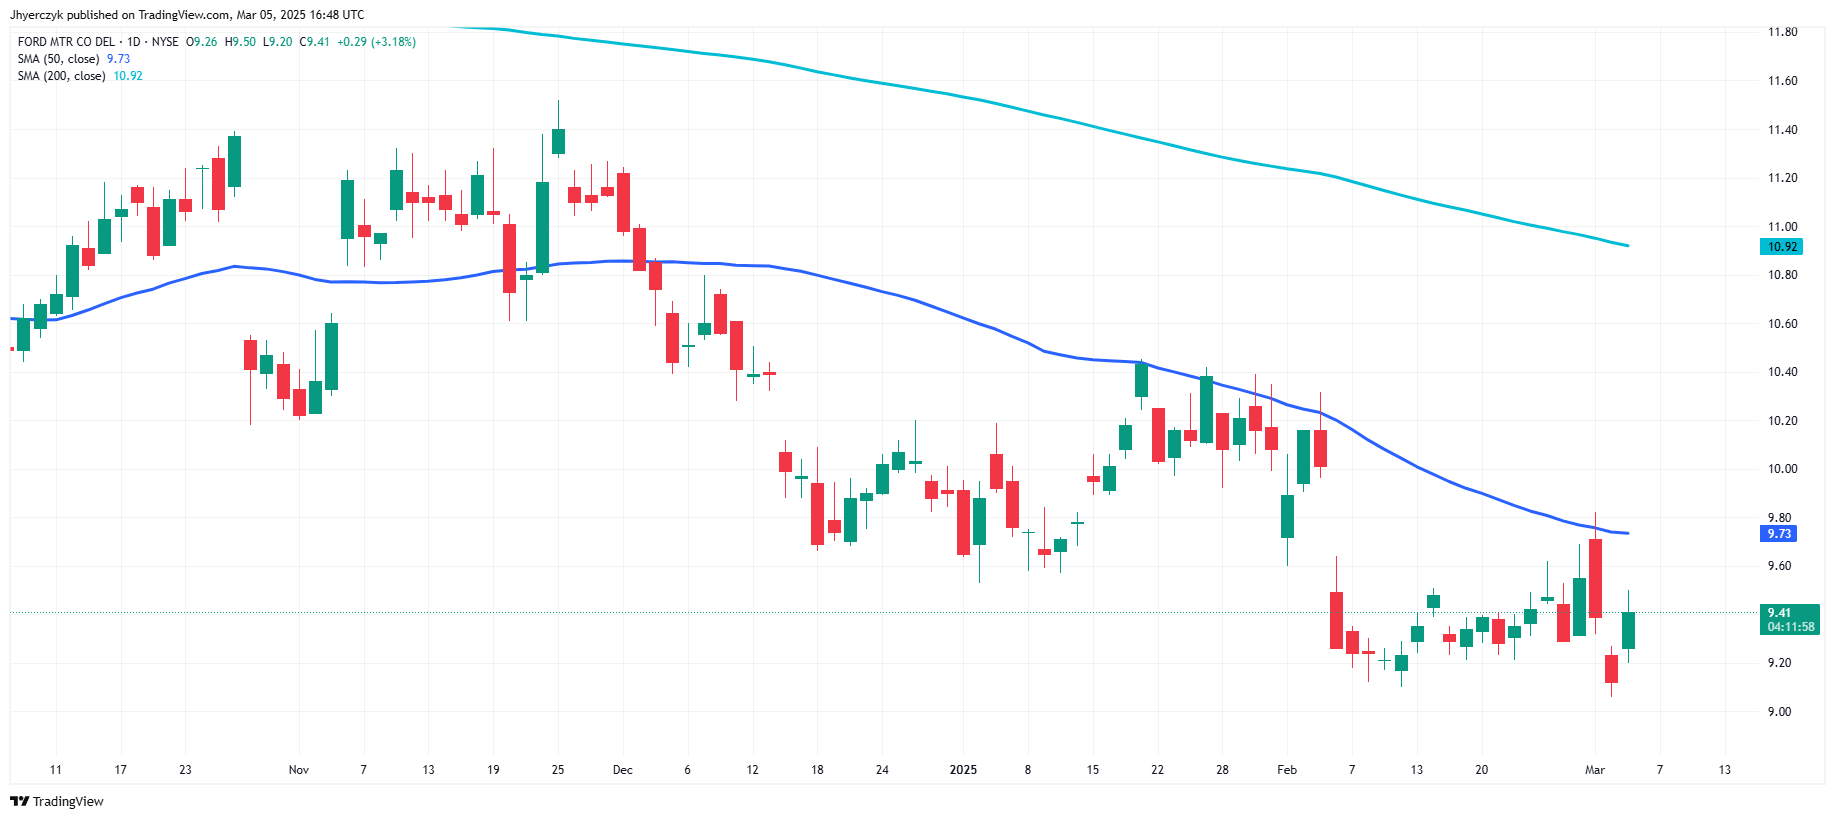
Investors parsed new comments from Commerce Secretary Howard Lutnick, who signaled that President Donald Trump was considering sector-specific tariff relief. While the remarks briefly lifted sentiment, uncertainty remained high. Auto stocks rebounded, with General Motors up more than 4% and Ford gaining over 3%, recovering from earlier tariff-related pressure. Canada Goose also rose nearly 2%.
Despite some relief in specific sectors, broader concerns about trade disruptions persisted. Trump dismissed concerns over his tariff policies in a Tuesday night address, but the risk of retaliatory measures from key trading partners continued to cast a shadow over markets.
What Does the Latest Economic Data Suggest?
A stronger-than-expected ISM services report helped ease slowdown fears, with the index rising to 53.5, beating forecasts of 52.9. New orders and employment showed strength, but inflation concerns surfaced as the prices index surged above 60 for the first time in nearly a year.
However, private payroll data from ADP was far weaker than expected, showing just 77,000 job additions in February—well below the 148,000 estimate. The report marked the slowest job growth since July, reinforcing concerns about economic momentum.
S&P 500 Price Forecast
Every new S&P 500 analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all S&P 500 forecastsWhich Sectors Are Leading at Midday?
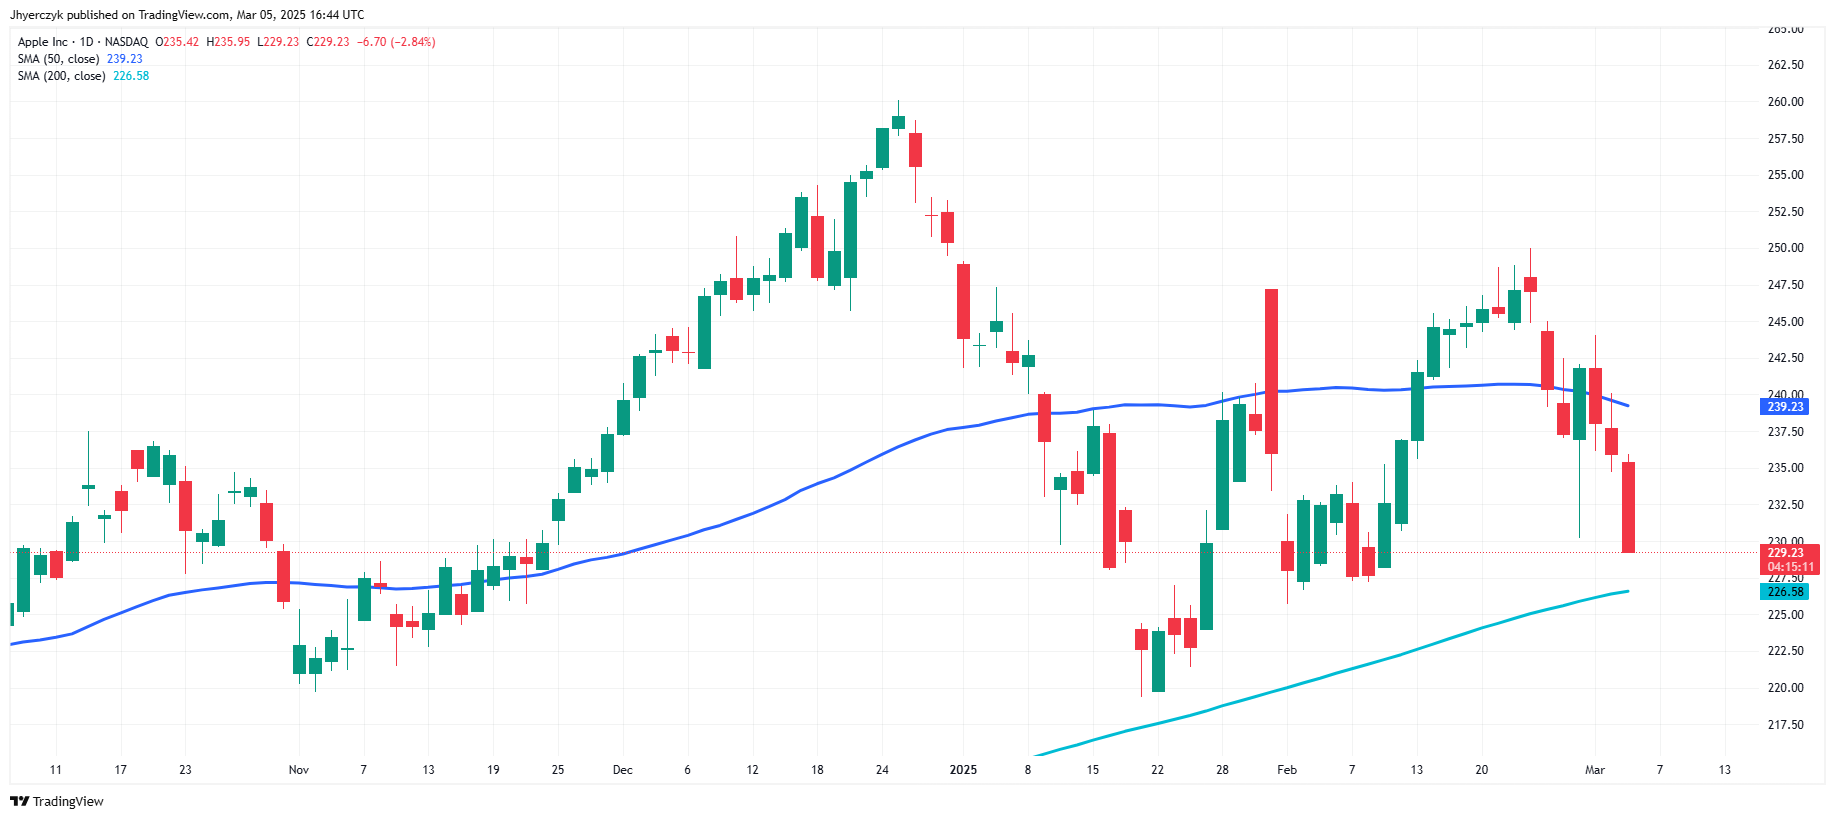
Energy was the biggest laggard, down 3.08% as oil prices declined. Financials and technology stocks also struggled, with Apple slipping nearly 2% and IBM falling 2.19%. Consumer staples and industrials saw modest gains, with Procter & Gamble up 0.85% and Caterpillar rising 1.64%. Microsoft and Amazon edged higher, up 0.59% and 0.47%, respectively.
What Could Drive Markets Into the Close?
Traders will be watching for any additional tariff-related headlines that could shift sentiment in the afternoon session. Sector rotation remains in focus, with defensive stocks holding gains while energy and tech struggle.
If selling pressure picks up, the S&P 500 could test key support levels, while any signs of progress on trade relief could help stabilize markets. Volume may pick up late in the session as investors position ahead of upcoming economic data and further trade developments.
More Information in our Economic Calendar.