Hot CPI Puts the Long End Back in Control
The stock market had a simple problem Wednesday. Inflation came in hot and the long end went right back to work. The S&P 500 is down, the Nasdaq is taking the bigger hit and the Dow is holding together only because healthcare buyers are keeping it from joining the tech-led break.
This is not a bad Bank of America day or another routine pullback in chips. Bond sellers already had the upper hand before the number came out. CPI gave them a fresh reason to press and they pressed. The selling started in bonds and worked its way into equities before stock traders had time to sort out what it meant for the rest of the session.
At 16:39 GMT, the S&P 500 Index is down 1.01%, the Nasdaq Composite is down 1.53% and the Dow Jones Industrial Average is down 43.46 points, or 0.26%.
Daily S&P 500 Index (SPX) Technical Analysis
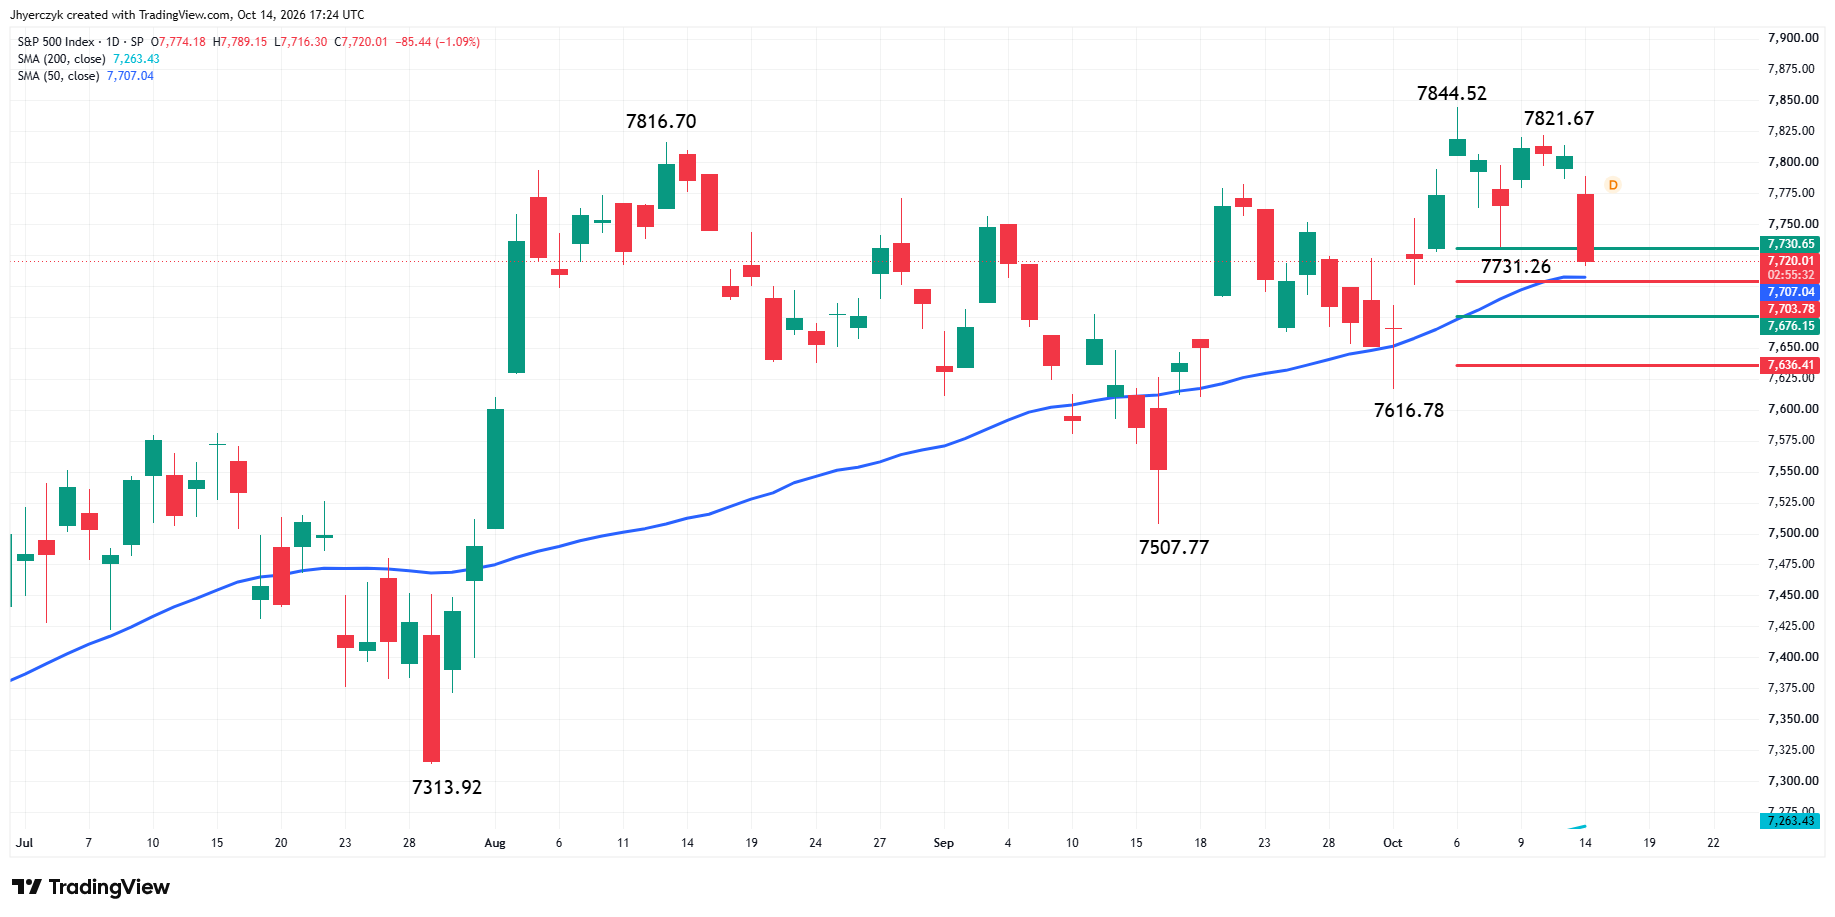
The S&P 500 Index is sharply lower shortly before the mid-session. The main trend is up, but the secondary lower top at 7821.67 suggests it may be weakening. A trade through 7731.26 will change the main trend to down. A trade through 7821.67 will take out the secondary lower top. A move through 7844.52 will signal a resumption of the uptrend.
The short-term range is 7616.78 to 7844.52. Its retracement zone at 7730.65 to 7703.78 is the first important downside target area. The intermediate range is 7507.77 to 7844.52. Its retracement zone at 7676.15 to 7636.41 is a second retracement area to watch.
The current sell-off has also brought the S&P 500 Index to within striking distance of the 50-day moving average at 7707.55. This 50-day moving average is both support and a major trend indicator. If the main trend turns down on the daily swing chart then taking out the 50-day moving average could trigger a steep break into the intermediate retracement zone.
The near-term outlook will be determined by how traders react to the main bottom at 7731.26 and the 50-day moving average at 7707.55.
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecastsCPI Gave the Long End Its Reason
Headline CPI at 0.6% matched the estimate and the market looked right past it. Annual ran to 3.7% from 3.4%, a tick above the forecast. That was not the number that moved anything.
Core was. Monthly core printed 0.3% versus the 0.2% the street wanted. Annual core hit 2.6%. Both beat in the wrong direction and the bond market moved before anything else on the screen did. Treasury futures sold off immediately. Equity futures followed.
The 10-year Treasury yield jumped more than 7 basis points to 5.293%. The 30-year yield rose more than 4 basis points to 5.609%. Both had reached new 24-year highs last week. The front end has been calm. The long end was already climbing before CPI came out and now it has more cover to keep going. The move in yields was immediate. Bond traders did not wait for equity to catch up.
Nothing in this number locks in another hike. December is harder to dismiss. The market had been trying to push it off the table for weeks. CPI put it back on.
The Nasdaq Is Carrying the Rate Damage
The Nasdaq had been making new highs while the Dow lagged and the long end refused to settle down. That was always a narrow trade. Growth stocks kept getting bought. The rest of the market was not confirming the move.
Wednesday’s CPI report ended that. Chip stocks are lower. AMD is down 3%. Intel and Sandisk are each off about 2%. Micron is also lower after a weak prior session. The SOX is down more than 2% and it was already lagging the Nasdaq before today. CPI took the one thing the chip trade needed off the table.
The Dow is holding up. UnitedHealth and Amgen are doing the work. Take those two out and the Dow is red. That is not broad strength. That is defensive money.
The S&P 500 is in the middle. Growth weight is pulling it toward the Nasdaq. Defensive names are holding the other side. Neither group is winning. Healthcare is the only sector in the green and it is not enough to carry the index. Everything tied to the rate outlook is selling. Everything hiding from it is getting small bids.
Earnings Are Not Getting a Free Pass
The earnings bar is higher now than it was a week ago. Bank results have been solid and the stocks are not acting like it.
Bank of America is lower after reporting third-quarter results that included the impact of a $1.2 billion federal penalty. The company earned 91 cents per share. Without the charge, that number climbs to $1.08. The market walked past the adjustment and sold the stock on the headline. A clean quarter would have moved the stock. This was not a clean quarter.
Morgan Stanley beat on earnings and revenue. Investment-banking revenue missed. The stock sat there. Not down. Not up. Flat on a beat. If a Morgan Stanley beat does not move the stock, nothing else on the earnings calendar is going to push back against the bond market.
BlackRock is the exception. Shares gained after better-than-expected earnings, with assets under management climbing to $15.49 trillion from $13.46 trillion a year earlier. Albemarle firmed on an upgrade. GameStop picked up after Ryan Cohen disclosed a share purchase. Individual stories. Not enough to move the index with the 10-year pressing higher.
Oil Is Back in the Inflation Argument
WTI crude is near $95 a barrel Wednesday. Russian diesel did not push prices lower and tanker risk around Hormuz is keeping an energy premium in the barrel.
Gasoline is already expensive at $4.34 a gallon. Crude staying bid is the last thing stock buyers needed after a hot CPI number. The product side is tight. The geopolitical premium is not coming out. If energy does not back off, the next inflation print is not getting any friendlier.
The whole week was supposed to be about earnings taking over from the rate story. CPI did not cooperate. Oil is not cooperating. Wednesday did not kill the bull case. It made it harder to trade.
What to Watch
CPI reset the conversation. The long end is running, oil is not backing off, and earnings are not big enough to push back against both. The market came into Wednesday looking for a reason to buy the dip in tech. It got the opposite. Until yields settle, every rally in equities is working against the bond market.
Today’s selling weakened my bullish bias. The 7731.26 area is the line, with the 50-day moving average sitting just below it. Buyers lose that zone and the rate trade takes the market lower. Nothing on the earnings calendar is big enough to take the conversation back.
More Information in our Economic Calendar.