


Earnings Kick Off Before the Bell
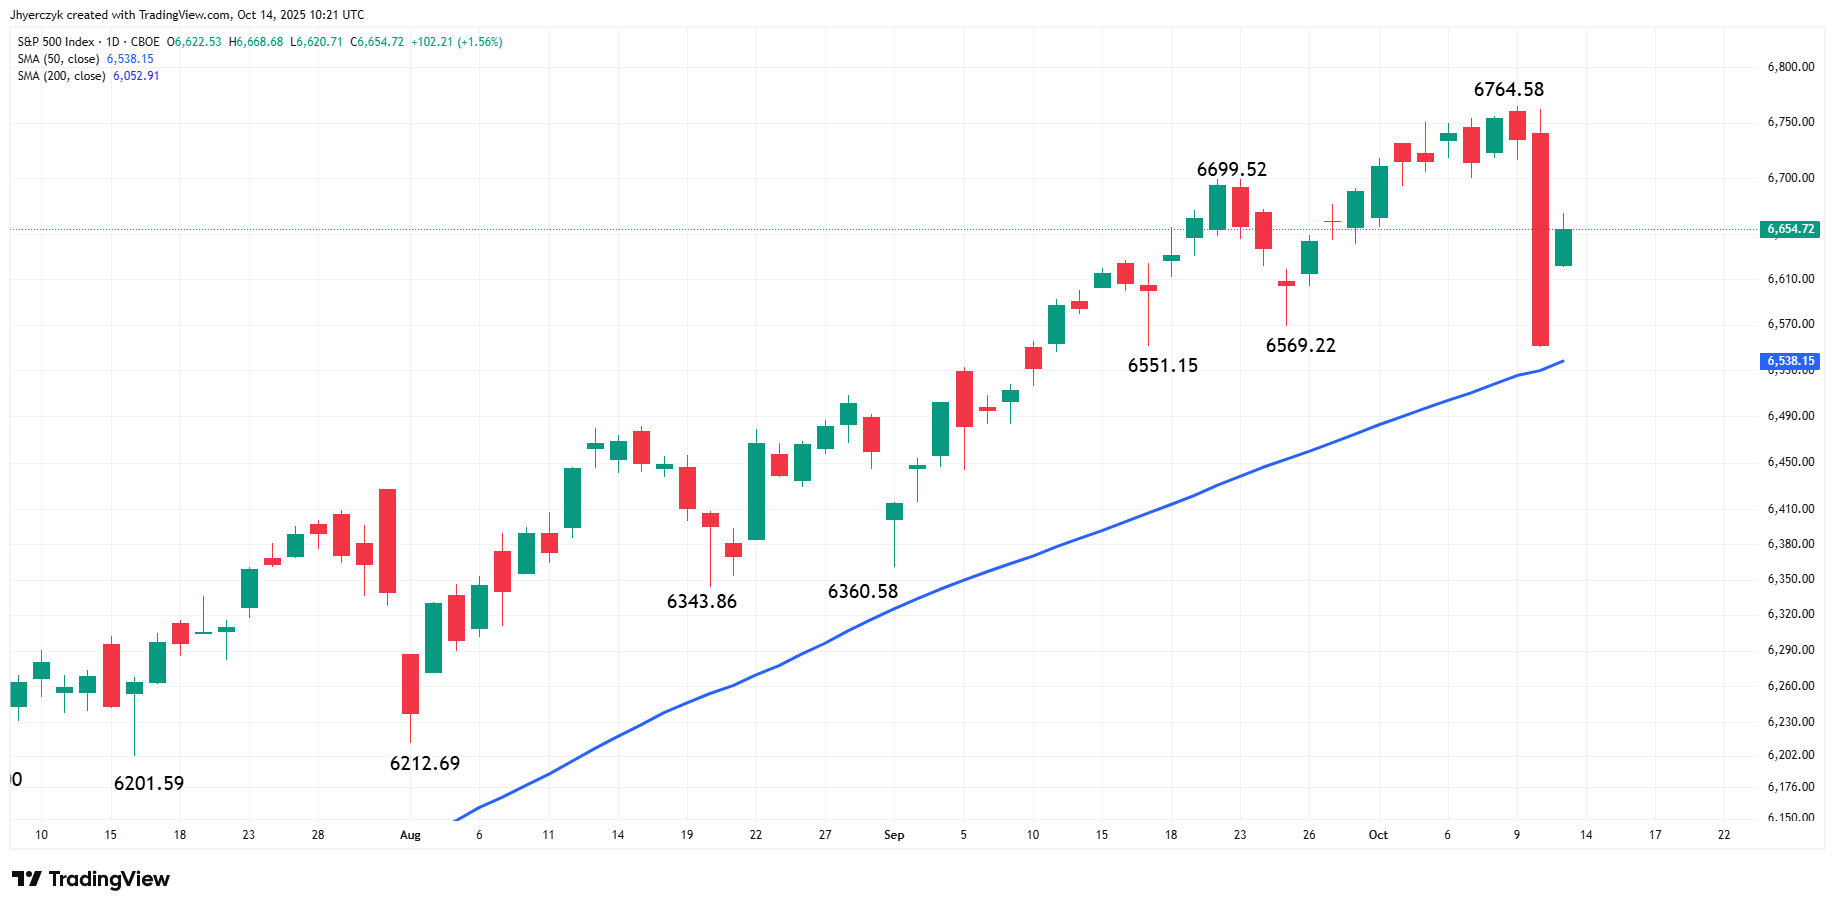
Tuesday, October 14, 2025, delivers a packed schedule that could steer U.S. markets for weeks.
At 11:00 GMT, JPMorgan Chase, Citigroup, and Wells Fargo release third-quarter results, followed by Goldman Sachs and BlackRock at 12:30 GMT. With the government shutdown freezing most economic data, earnings carry outsized influence on sentiment and positioning ahead of Powell’s remarks later in the day.
Analysts expect JPMorgan (JPM) to post $4.85 EPS on $45.5 billion revenue (+11% YoY), extending its run of eight EPS beats in the last nine quarters.
Goldman Sachs (GS) is forecast to rebound sharply — EPS up 30% to $10.99 —J thanks to revived M&A activity, stronger trading revenue, and a pickup in deal fees.
Citigroup (C) should post 15% earnings growth as cost cuts and balance-sheet cleanup continue.
Wells Fargo (WFC), however, presents an anomaly: analysts see revenue nearly 50% lower YoY despite modest EPS growth — a divergence likely tied to one-time adjustments or divestitures not yet detailed in consensus data.
FactSet projects S&P 500 earnings growth of 8% YoY, the ninth straight quarter of expansion. Historically, realized results exceed consensus by around six points, implying potential growth near 14%. That backdrop underscores why expectations — and valuations — are stretched.
Powell’s Last Word Before the FOMC
At 15:20 GMT, Federal Reserve Chair Jerome Powell delivers his final scheduled remarks before the 29–30 October FOMC meeting at the NABE conference in Philadelphia.
Markets price 97% odds of an October rate cut and 89% for December, but any hint of “higher for longer” could challenge that view. Strong consumer credit and loan growth in bank reports would give the Fed cover to stay patient, while signs of stress could accelerate easing expectations.
Trade Front Turns Hostile Again
On Friday, President Trump announced new 100% tariffs atop existing 30% rates on Chinese imports, effective 1 November, citing Beijing’s curbs on rare-earth exports crucial for AI and defence. China retaliated with $50-per-ton port fees on U.S. ships, plus 10% tariffs on timber and 25% on furniture starting today.
Sentiment, Levels, and Options Positioning
The AAII bullish reading (45.9%) marks a fourth week above average, leaving markets vulnerable to disappointment. The VIX near 16 remains calm, but a move above 18 — its historical median — would signal renewed risk hedging.
Base vs. Risk Scenarios
Based on current market positioning and consensus expectations for Q3 results, traders generally see:
- Base Case (≈60% probability) – Banks deliver 3–5% earnings beats and Powell strikes a balanced tone. Markets hold steady as investors wait for follow-through from later bank and tech reports.
- Bull Case (≈20% probability) – Earnings exceed expectations by more than 8% and Powell sounds dovish, reinforcing soft-landing optimism and extending the rally.
- Bear Case (≈20% probability) – Bank results disappoint while Powell leans hawkish or trade tensions escalate, prompting risk reduction and profit-taking.
What to Watch
- JPM EPS > $4.87 → confirms consumer strength, supports financials. Below $4.80 → credit quality concerns.
- Powell tone → dovish = rally extension; firm = profit-taking.
- Semiconductors → sensitive to tariff headlines, watch for swings.
Outlook
Tuesday’s convergence of earnings, Fed guidance, and trade escalation creates a high-stakes inflection point. The bullish case requires both solid bank results and a measured Powell — a high bar given stretched optimism.
The most probable path: initial strength on earnings, fading into the close if Powell leans cautious ahead of the FOMC. With nine straight quarters of earnings growth and valuations elevated, traders may prefer taking profits on strength rather than chasing highs.
More Information in our Economic Calendar.


