Market Overview
U.S. equities closed higher last week. The Dow Jones Industrial Average finished at 51,828.62, up 0.28% for the week. The Nasdaq Composite closed at 27,068.72, up 2.06%, while the S&P 500 settled at 7,743.41, up 1.21%.
Inflation, growth and Federal Reserve policy remain the primary macro themes. Core PCE inflation is running at 3.3%, above the Fed’s 2% target. The Fed raised interest rates by 25 basis points at its September meeting and signaled at least one additional increase.
Consumer spending, AI investment and corporate profits continue to support growth. Progress Software’s report will focus on its Domo acquisition and AI-related business prospects, while Nike enters earnings season after its removal from the S&P 100.
Core PCE data, employment data and a heavy Federal Reserve speaking schedule are the week’s main catalysts. Earnings from Vail Resorts, CarMax, Progress Software, Accenture and Nike will also draw attention.
Key Economic Releases & Notable Earnings
Monday, September 28
Earnings Before the Open
No reports scheduled
Economic Releases
No releases scheduled
Earnings After the Close
Vail Resorts (MTN), est. -$5.30 per share
Tuesday, September 29
Earnings Before the Open
CarMax (KMX), est. $0.72 per share
Economic Releases
13:00 GMT, HPI m/m, forecast 0.1% (prior 0.0%)
13:00 GMT, S&P/CS Composite-20 HPI y/y, forecast 2.2% (prior 2.1%)
14:00 GMT, CB Consumer Confidence, forecast 90.1 (prior 89.4)
14:00 GMT, JOLTS Job Openings, forecast 7.23M (prior 7.27M)
20:30 GMT, API Weekly Statistical Bulletin
Earnings After the Close
AAR (AIR), est. $1.31 per share
Concentrix (CNXC), est. 2.71
FedEx Freight (FDXF), est. 1.39
Wednesday, September 30
Earnings Before the Open
Cal-Maine Foods (CALM), est. -$0.71 per share
Conagra Brands (CAG), est. 0.28
FactSet Research Systems (FDS), est. 4.35
Jabil (JBL), est. 4.06
Economic Releases
12:15 GMT, ADP Non-Farm Employment Change, forecast 70K (prior 38K)
12:30 GMT, Core PCE Price Index m/m, forecast 0.3% (prior 0.2%)
12:30 GMT, Final GDP q/q, forecast 1.5% (prior 1.5%)
12:30 GMT, Final GDP Price Index q/q, forecast 6.4% (prior 6.4%)
12:30 GMT, Goods Trade Balance, forecast -113.8B (prior -118.9B)
12:30 GMT, Personal Income m/m, forecast 0.5% (prior 0.4%)
12:30 GMT, Personal Spending m/m, forecast 1.0% (prior 0.2%)
12:30 GMT, Prelim Wholesale Inventories m/m, forecast 1.1% (prior 1.3%)
13:45 GMT, Chicago PMI, forecast 51.3 (prior 47.1)
14:30 GMT, Crude Oil Inventories, prior 3.0M
Earnings After the Close
Progress Software (PRGS), est. $1.52 per share
Progress Software reports fiscal third-quarter results after the close. Analysts expect $1.52 per share, up from $1.50 a year ago, despite a 0.9% revenue decline to $247.59 million. Investors will monitor management’s comments on the $400 million Domo acquisition and its role across application development, developer tools, IT infrastructure, DevOps management and connectivity.
Thursday, October 1
Earnings Before the Open
Accenture (ACN), est. $3.18 per share
Acuity (AYI), est. 5.66
McCormick (MKC), est. 0.76
Economic Releases
09:30 GMT, Challenger Job Cuts y/y, prior -38.5%
12:30 GMT, Unemployment Claims, forecast 199K (prior 197K)
13:45 GMT, Final Manufacturing PMI, forecast 57.0 (prior 57.0)
14:00 GMT, ISM Manufacturing PMI, forecast 55.0 (prior 54.6)
14:00 GMT, Construction Spending m/m, forecast 0.1% (prior -0.5%)
14:00 GMT, ISM Manufacturing Prices, forecast 72.0 (prior 71.1)
All Day, Omdia Total Vehicle Sales, forecast 16.5M (prior 16.8M)
14:30 GMT, Natural Gas Storage, prior 53B
Earnings After the Close
Nike (NKE), est. 44 cents per share
Nike reports fiscal 2027 first-quarter results after the close. Wall Street expects earnings per share to decline 10.2% year over year to 44 cents and revenue to decline 3.3%. Nike was removed from the S&P 100 effective September 21 and was the smallest-weighted Dow component and the worst-performing component this year through September 24.
Friday, October 2
Earnings Before the Open
No reports scheduled
Economic Releases
12:30 GMT, Average Hourly Earnings m/m, forecast 0.3% (prior 0.3%)
12:30 GMT, Non-Farm Employment Change, forecast 98K (prior 162K)
12:30 GMT, Unemployment Rate, forecast 4.1% (prior 4.1%)
14:00 GMT, Factory Orders m/m, forecast -0.1% (prior 0.9%)
Earnings After the Close
No reports scheduled
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecastsCentral Bank Activity
Monday, September 28
12:15 GMT, Bowman (FOMC Member)
17:25 GMT, Cook (FOMC Member)
17:30 GMT, Barkin (FOMC Member)
Tuesday, September 29
15:00 GMT, Bowman (FOMC Member)
16:40 GMT, Barr (FOMC Member)
17:00 GMT, Goolsbee (FOMC Member)
17:30 GMT, Musalem (FOMC Member)
18:00 GMT, Williams (FOMC Member)
19:00 GMT, Waller (FOMC Member)
Wednesday, September 30
17:30 GMT, Barkin (FOMC Member)
19:25 GMT, Cook (FOMC Member)
21:10 GMT, Goolsbee (FOMC Member)
22:00 GMT, Kashkari (FOMC Member)
Thursday, October 1
13:05 GMT, Barkin (FOMC Member)
Time not supplied, Collins (FOMC Member)
Time not supplied, Schmid (FOMC Member)
14:00 GMT, Waller (FOMC Member)
17:30 GMT, Jefferson (FOMC Member)
19:00 GMT, Bowman (FOMC Member)
19:30 GMT, Cook (FOMC Member)
22:45 GMT, Logan (FOMC Member)
Friday, October 2
Time not supplied, Logan (FOMC Member)
Traders will watch the speakers after the September rate increase and before Core PCE and payrolls data. CME FedWatch showed markets pricing in two additional increases this year, at the October 27-28 meeting and again in December.
Technical Outlook
Weekly Dow Jones Industrial Average Index
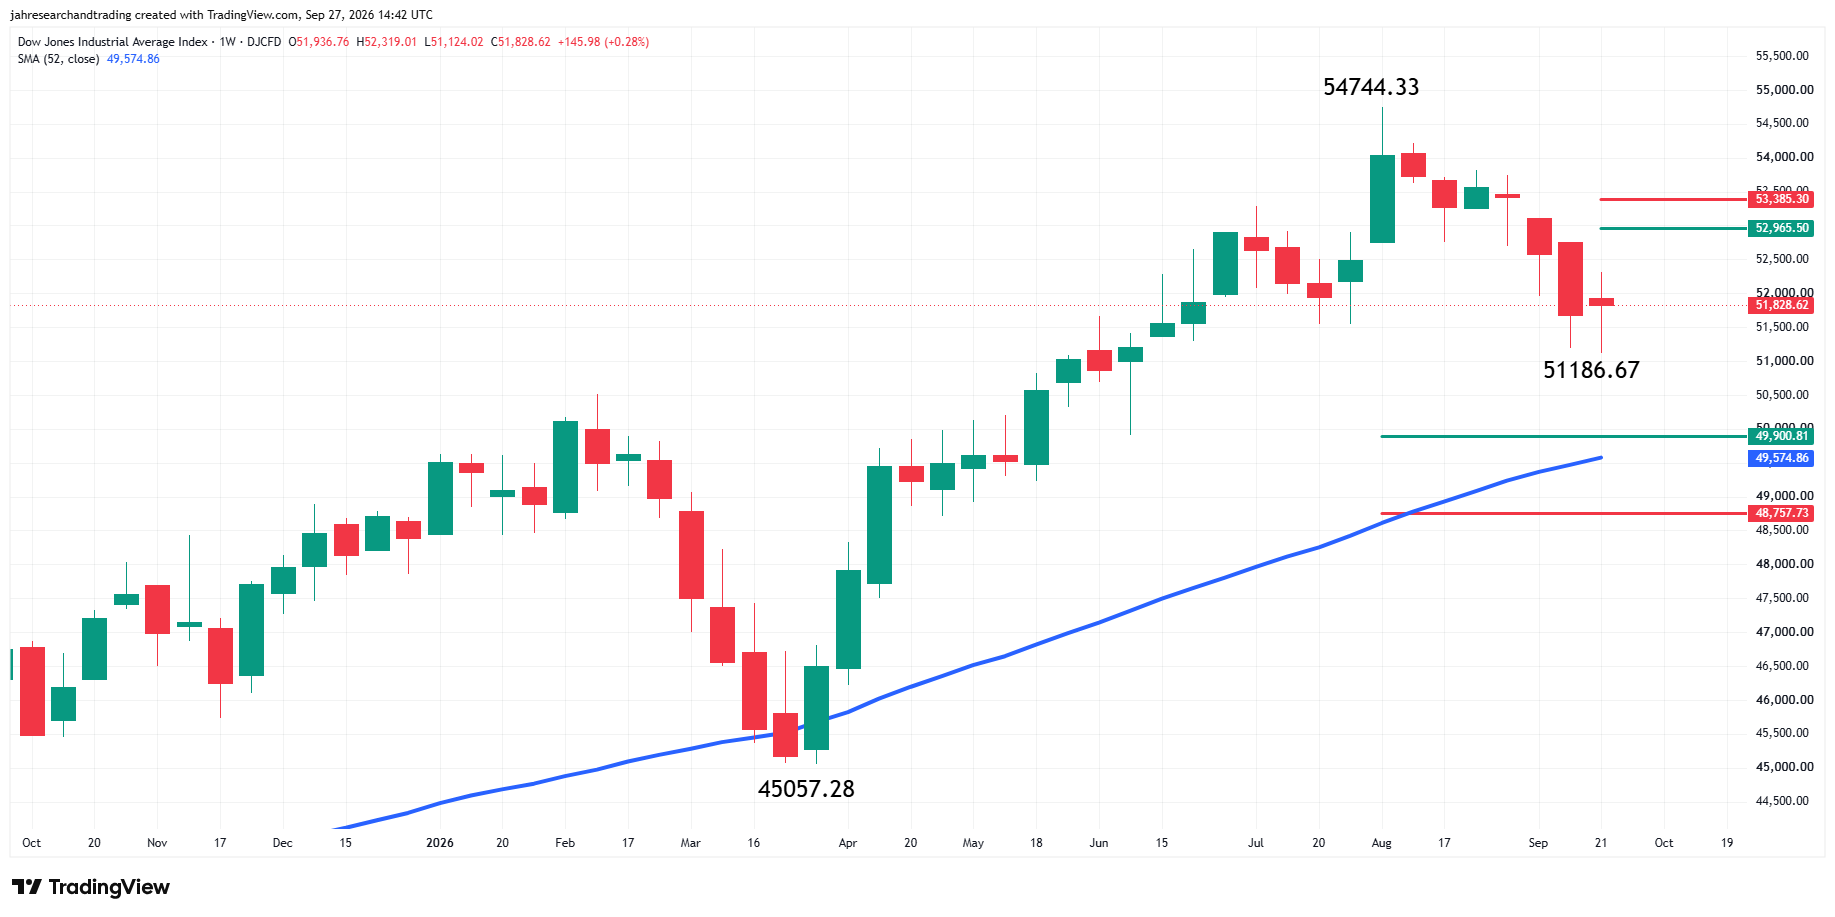
Dow Jones: 51,828.62 (+0.28%), Support at 51,186.67, 49,900.81, the 52-week SMA at 49,574.86, 48,757.73 and 45,057.28, Resistance at 52,965.50, 53,385.30 and 54,744.33.
Weekly Nasdaq Composite Index
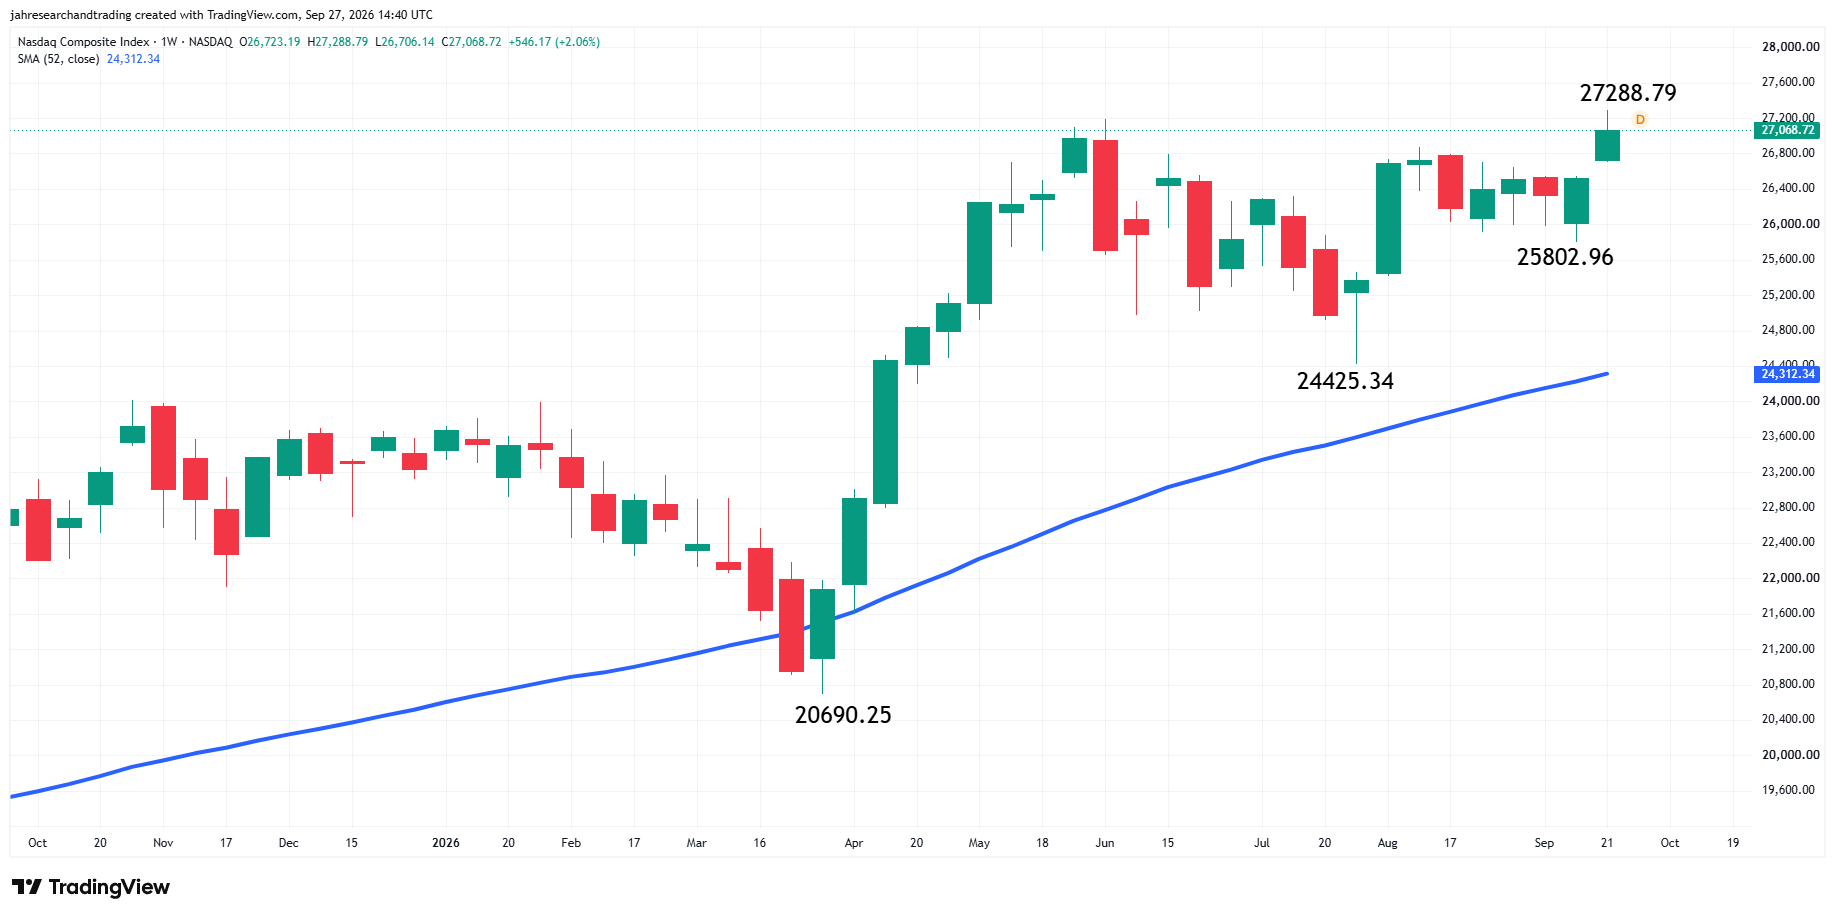
Nasdaq: 27,068.72 (+2.06%), Support at 25,802.96, 24,425.34, the 52-week SMA at 24,312.34 and 20,690.25, Resistance at 27,288.79.
Weekly S&P 500 Index
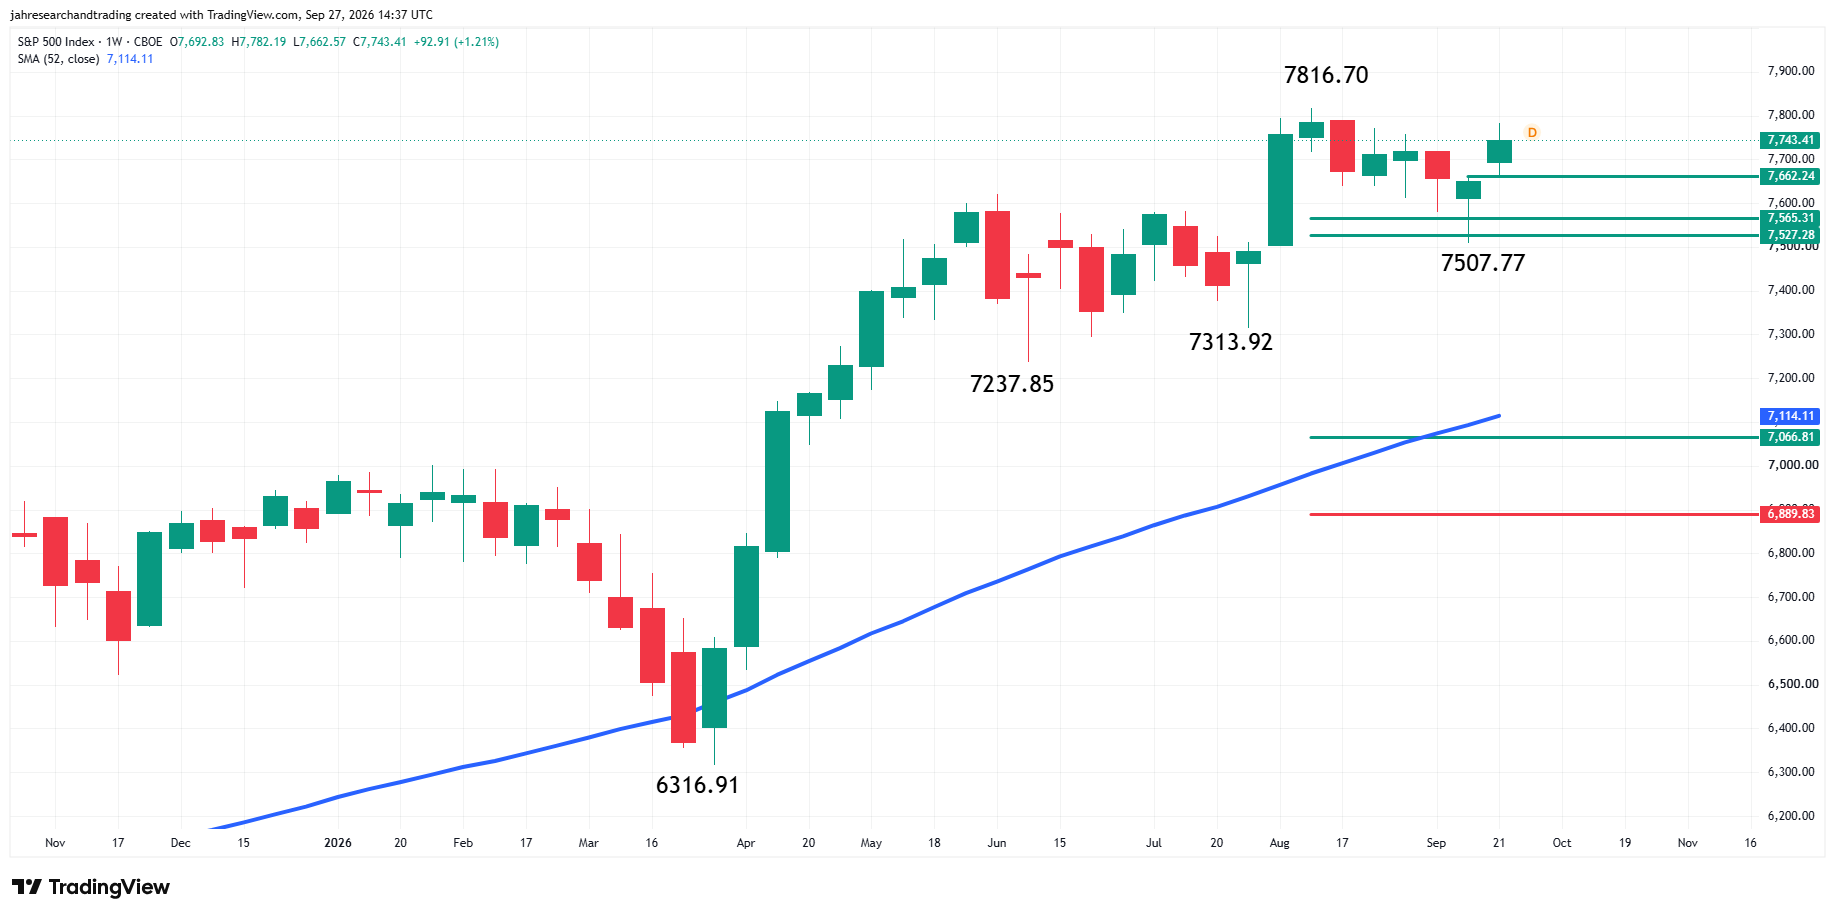
S&P 500: 7,743.41 (+1.21%), Support at 7,662.24, 7,565.31, 7,527.28, 7,507.77, 7,313.92, 7,237.85, the 52-week SMA at 7,114.11, 7,066.81, 6,889.83 and 6,316.91, Resistance at 7,816.70.
All major indices remain above rising 52-week SMAs, confirming an intact long-term uptrend.
Weekly Outlook
Core PCE, GDP, consumer spending, employment, manufacturing, housing and factory-order reports fill the economic calendar. The week also includes earnings from Vail Resorts, CarMax, Progress Software, Accenture and Nike, along with 22 scheduled Federal Reserve appearances.
Traders will monitor the inflation and employment reports alongside the Fed speakers for signals on additional rate increases. Holding the listed weekly support levels would maintain the current long-term uptrend, while a break below them would put the major indices under pressure.
More Information in our Economic Calendar.