


Market Overview
The Dow Jones Industrial Average closed at 52,215.16, up 0.41% for the week. The Nasdaq Composite closed at 25,955.34, down 0.71%. The S&P 500 Index finished at 7,623.68, down 0.47%.
Federal Reserve policy remains a major issue. The Fed raised rates in September for the first time since 2023 to address above-target inflation. FedWatch showed an 88% probability of unchanged rates at Wednesday’s meeting, while futures pointed to roughly an 80% probability of a December hike.
Technology shares came under pressure after reports from Meta and Lam Research disappointed investors. Third-quarter S&P 500 earnings are on pace to rise more than 32% from a year ago, while hyperscaler capital spending is expected to total around $800 billion this year.
The Fed decision, Core PCE, GDP, employment data and earnings from Alphabet, Microsoft, Amazon, Intel, Sandisk, Caterpillar, Eli Lilly, Exxon and Chevron are the week’s main catalysts.
Key Economic Releases & Notable Earnings
Monday, October 26
Earnings Before the Open
AstraZeneca (AZN), est. EPS $2.59 per share
Verizon (VZ), est. EPS 1.27
Economic Releases
No releases scheduled
Earnings After the Close
Cadence Design (CDNS), est. EPS 2.05
Nucor (NUE), est. EPS 5.84
Welltower (WELL), est. EPS 1.64
Tuesday, October 27
Earnings Before the Open
Boeing (BA), est. EPS -0.25
Coca-Cola (KO), est. EPS 0.88
PayPal (PYPL), est. EPS 1.31
UPS (UPS), est. EPS 1.62
Economic Releases
12:15 GMT, ADP Weekly Employment Change, prior 18.5K
12:30 GMT, Core Durable Goods Orders m/m, forecast 0.6% (prior 0.2%)
12:30 GMT, Durable Goods Orders m/m, forecast 1.8% (prior -0.1%)
13:00 GMT, HPI m/m, forecast 0.1% (prior 0.3%)
13:00 GMT, S&P/CS Composite-20 HPI y/y, forecast 2.7% (prior 2.5%)
14:00 GMT, CB Consumer Confidence, forecast 80.5 (prior 81.9)
14:00 GMT, New Home Sales, forecast 649K (prior 684K)
14:00 GMT, Richmond Manufacturing Index, forecast 1 (prior -2)
20:30 GMT, API Weekly Statistical Bulletin
Earnings After the Close
Visa (V), est. EPS 3.44
NXP Semi (NXPI), est. EPS 4.12
Robinhood Markets (HOOD), est. EPS 0.56
Wednesday, October 28
Earnings Before the Open
GE Vernova (GEV), est. EPS 3.99
Automatic Data (ADP), est. EPS 2.77
Vertiv (VRT), est. EPS 1.82
Economic Releases
12:30 GMT, Goods Trade Balance, forecast -130.8B (prior -132.1B)
12:30 GMT, Prelim Wholesale Inventories m/m, forecast 0.4% (prior 0.5%)
14:30 GMT, Crude Oil Inventories, forecast -0.3M (prior -3.1M)
Earnings After the Close
Alphabet (GOOGL), est. EPS $3.00 per share
Analysts expect revenue of $127.9 billion, up 24.9% from a year earlier. Search, YouTube and Cloud growth will be in focus.
Microsoft (MSFT), est. EPS 4.71
ServiceNow (NOW), est. EPS 1.02
Thursday, October 29
Earnings Before the Open
Caterpillar (CAT), est. EPS $7.03 per share
Analysts expect revenue of $20.7 billion, up 17.6% from a year earlier. Bernstein expects a beat on a healthy backlog but sees a downshift in bookings momentum.
Eli Lilly (LLY), est. EPS 5.70
Mastercard (MA), est. EPS 5.17
Economic Releases
12:30 GMT, Advance GDP q/q, forecast 3.2% (prior 2.2%)
12:30 GMT, Core PCE Price Index m/m, forecast 0.3% (prior 0.2%)
12:30 GMT, Advance GDP Price Index q/q, forecast 3.5% (prior 6.1%)
12:30 GMT, Unemployment Claims, forecast 198K (prior 194K)
12:30 GMT, Personal Income m/m, forecast 0.3% (prior 0.2%)
12:30 GMT, Personal Spending m/m, forecast 0.6% (prior 0.9%)
14:30 GMT, Natural Gas Storage, forecast 77B
Earnings After the Close
Amazon (AMZN), est. EPS $1.96 per share
Wall Street expects revenue of $202.2 billion, up 12.2% from a year earlier. Investors are focused on profitability, capital expenditure and returns from AI investment.
Intel (INTC), est. EPS 0.40
Sandisk (SNDK), est. EPS 46.20
Friday, October 30
Earnings Before the Open
Chevron (CVX), est. EPS 4.86
Exxon Mobil (XOM), est. EPS 4.10
Economic Releases
12:30 GMT, Employment Cost Index q/q, forecast 0.8% (prior 0.9%)
13:45 GMT, Chicago PMI, forecast 54.8 (prior 58.8)
Earnings After the Close
No reports scheduled
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecastsCentral Bank Activity
Wednesday, October 28
Federal Funds Rate, 18:00 GMT
FOMC Statement, 18:00 GMT
FOMC Press Conference, 18:30 GMT
Friday, October 30
FOMC Member Daly Speaks, 16:00 GMT
FOMC Member Musalem Speaks, 16:30 GMT
Traders will monitor the Fed decision and Chair Kevin Warsh’s press conference for clues about the expected December rate path.
Technical Outlook
Weekly Dow Jones Industrial Average Index
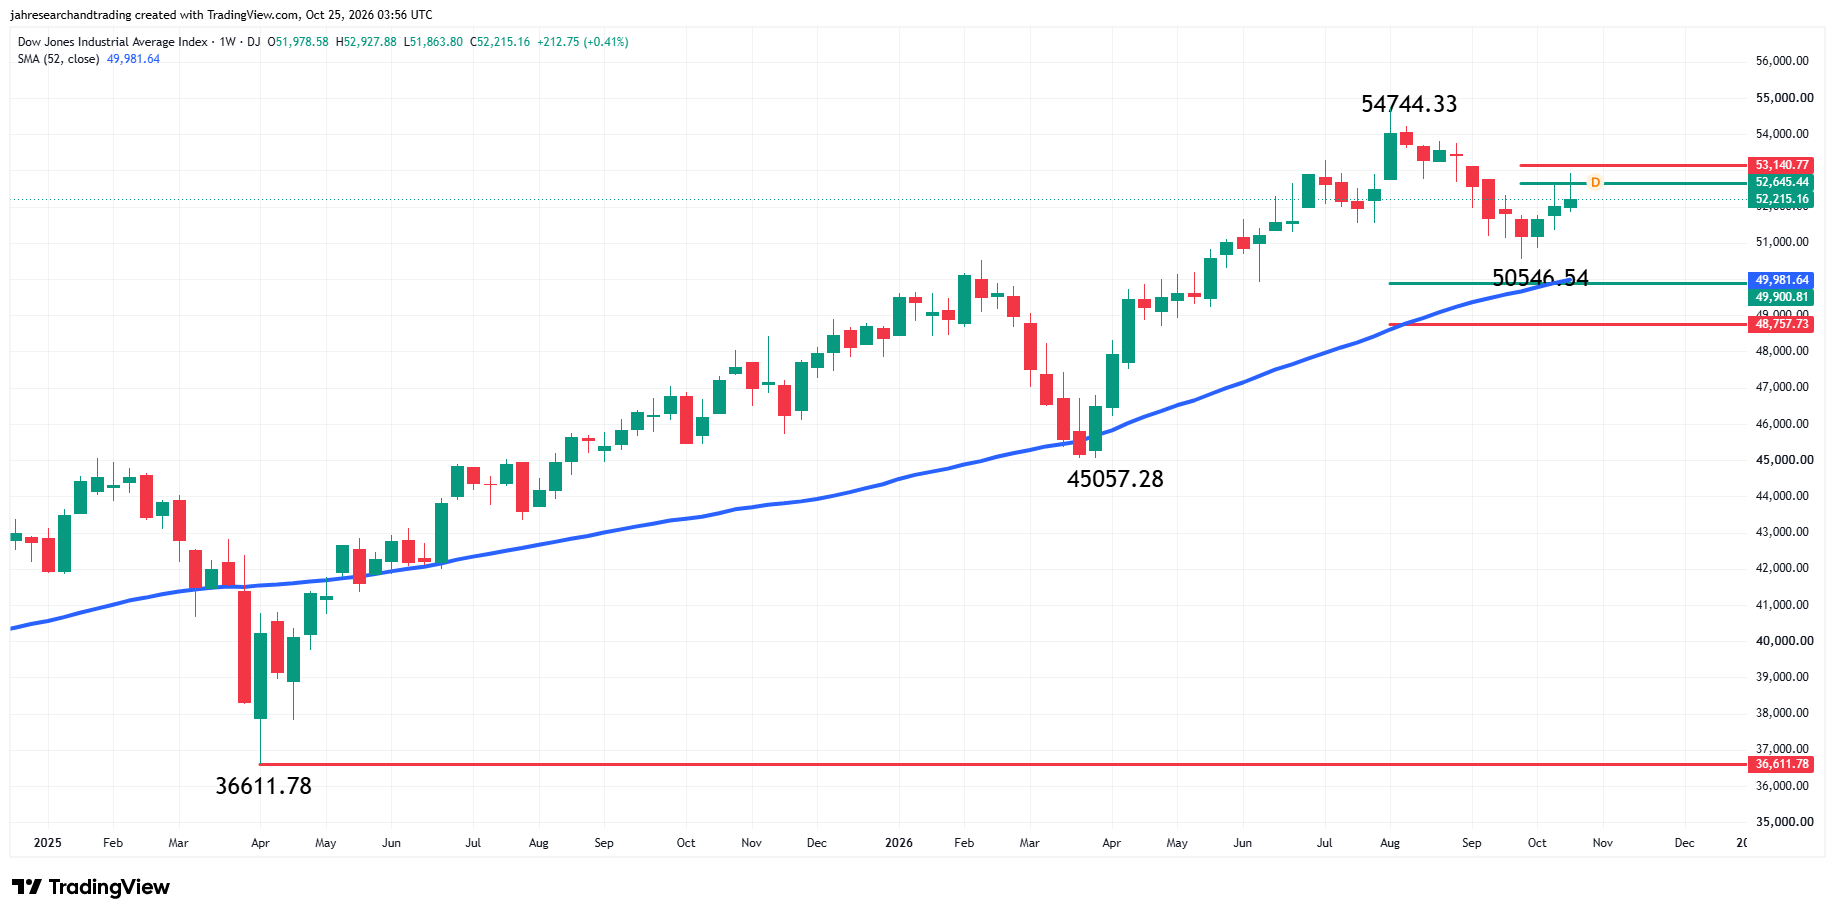
Dow Jones: 52,215.16 (+0.41%), Support at 50,546.54, 52-week SMA 49,981.64, 49,900.81, 48,757.73, 45,057.28 and 36,611.78; Resistance at 52,645.44, 53,140.77 and 54,744.33.
Weekly Nasdaq Composite Index
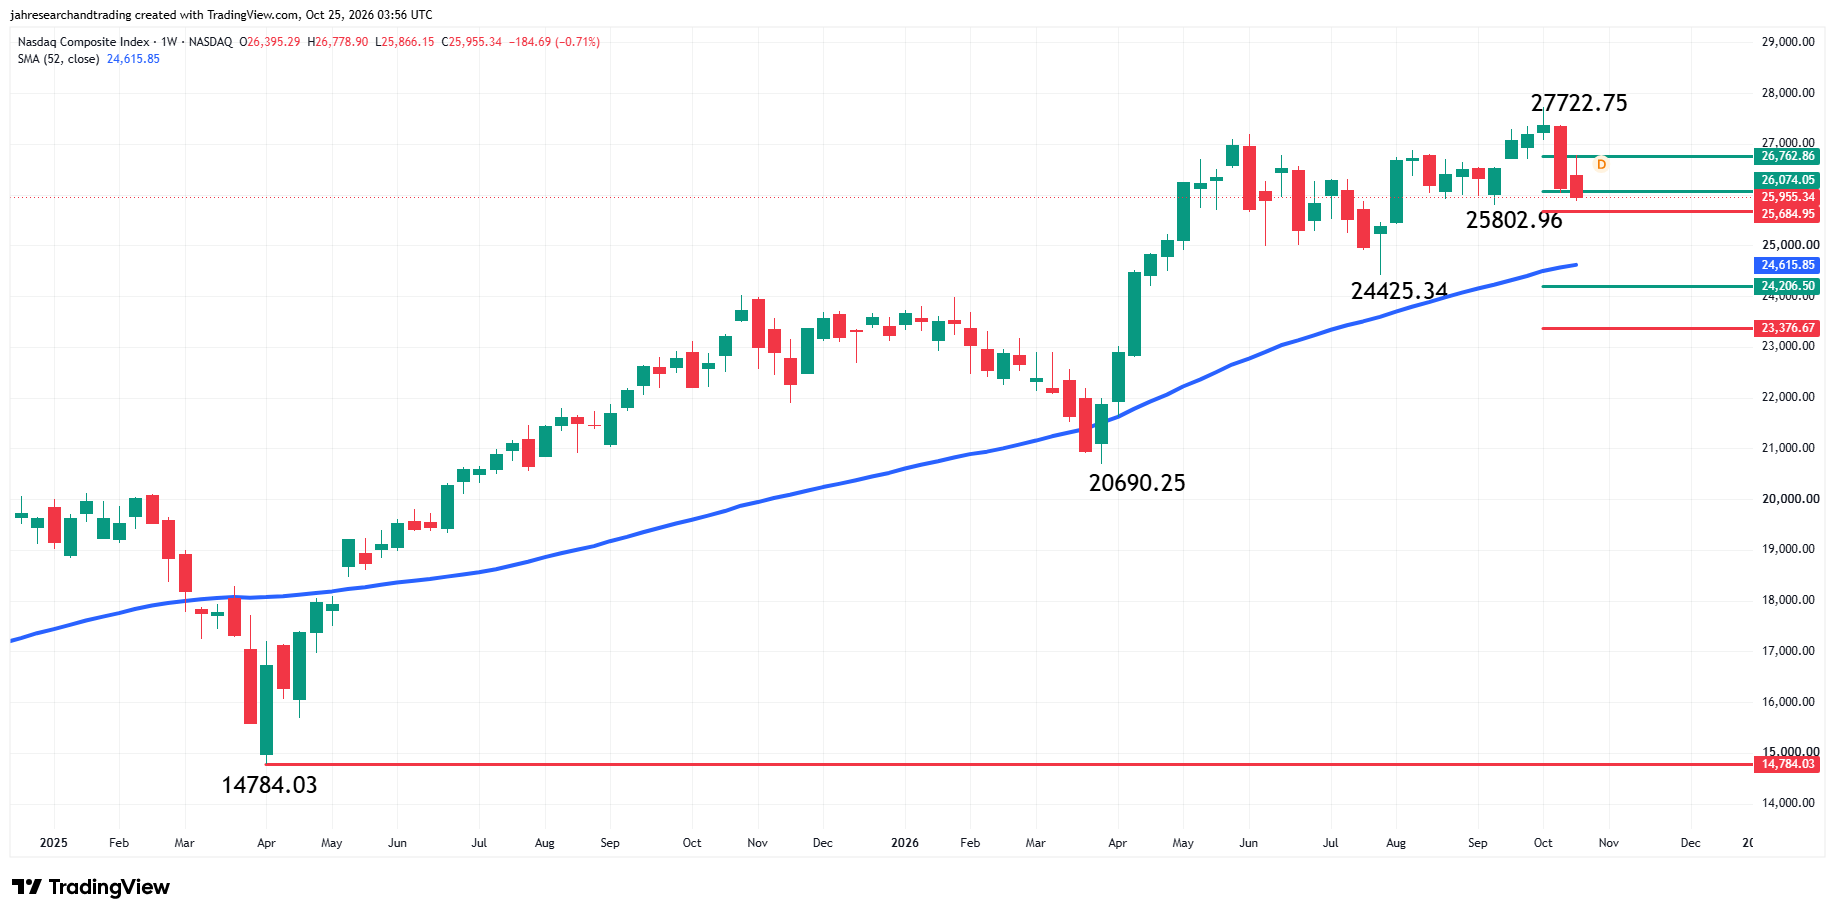
Nasdaq: 25,955.34 (-0.71%), Support at 25,894.95, 25,802.96, 52-week SMA 24,615.85, 24,425.34, 24,206.50, 23,376.67, 20,690.25 and 14,784.03; Resistance at 26,074.05, 26,762.86 and 27,722.75.
Weekly S&P 500 Index
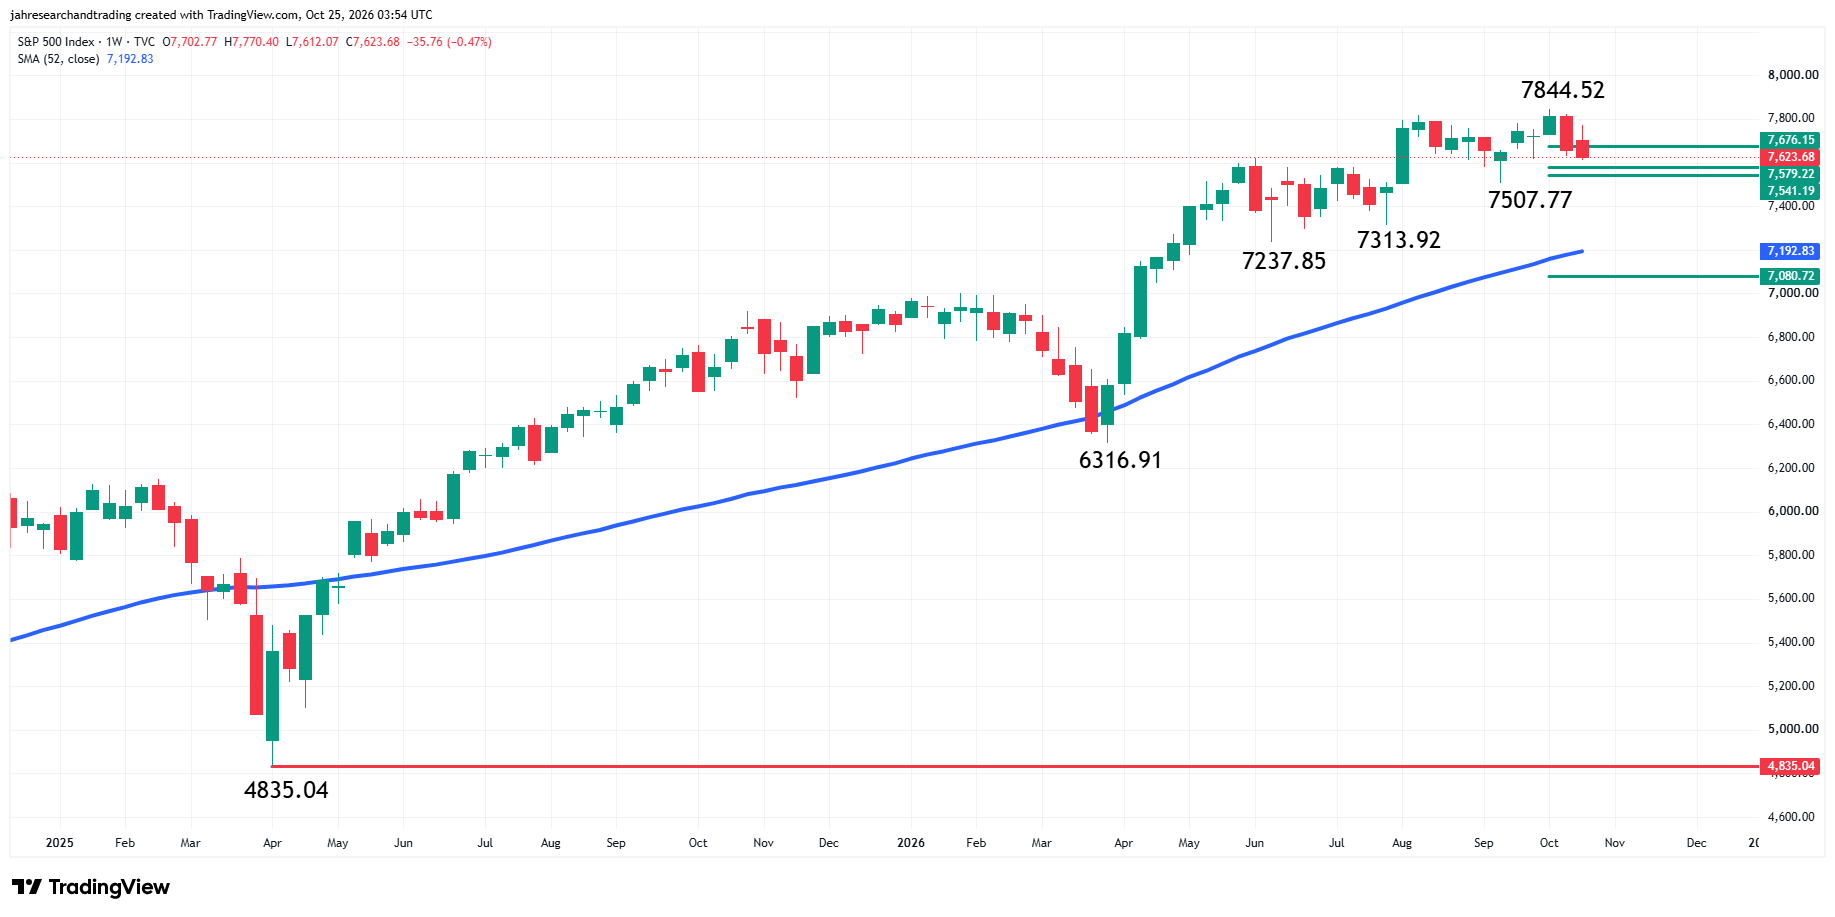
S&P 500: 7,623.68 (-0.47%), Support at 7,592.22, 7,541.19, 7,507.77, 7,313.92, 7,237.85, 52-week SMA 7,192.83, 7,080.72, 6,316.91 and 4,835.04; Resistance at 7,844.52.
All major indices remain above rising 52-week SMAs, confirming an intact long-term uptrend.
Outlook
The Fed decision, Core PCE, GDP, employment data and earnings from Alphabet, Microsoft, Amazon, Intel, Sandisk, Caterpillar, Eli Lilly, Exxon and Chevron are the main catalysts.
Traders will monitor whether earnings and company guidance support confidence in AI spending. Holding above the listed support areas would support the long-term uptrend, while weak earnings, higher inflation readings or Fed comments on December could place those levels under pressure.
More Information in our Economic Calendar.