Market Overview
U.S. stocks gave back ground last week as the AI trade came under pressure. The Dow Jones Industrial Average closed at 52,002.41, down 0.67%. The Nasdaq Composite settled at 26,140.03, down 4.48%, and the S&P 500 closed at 7,659.44, down 1.95%.
The AI trade is the immediate problem. Semiconductor and tech hardware shares were hit, while CoreWeave’s roughly $50 billion debt put financing for the AI build-out back in front of traders. Higher Treasury yields and the prospect of another Federal Reserve rate increase remain part of the pressure on technology.
Earnings are the major event this week. S&P 500 companies are expected to post third-quarter earnings growth of more than 30%, according to LSEG IBES. Meta Platforms, Lam Research, Texas Instruments, Tesla, Netflix, GE Aerospace and Procter & Gamble are all due to report.
The earnings calls will decide whether buyers come back to the AI trade or keep pressing the recent break. Weekly jobless claims arrive Thursday, followed Friday by Flash Manufacturing PMI, Flash Services PMI and revised University of Michigan consumer sentiment. The Federal Reserve is in its blackout period.
Key Economic Releases & Notable Earnings
Monday, October 19
Earnings Before the Open
Cleveland-Cliffs (CLF), $0.22 per share.
Fifth Third Bancorp (FITB), $0.83 per share.
Economic Releases
14:00 GMT, NAHB Housing Market Index, forecast 31 (prior 32).
Earnings After the Close
BOK Financial (BOKF), $2.52 per share.
Steel Dynamics (STLD), $5.48 per share.
W.R. Berkley (WRB), $1.15 per share.
Tuesday, October 20
Earnings Before the Open
GE Aerospace (GE), $2.00 per share.
General Motors (GM), $3.69 per share.
Halliburton (HAL), $0.58 per share.
Northrop Grumman (NOC), $7.18 per share.
RTX (RTX), $1.78 per share.
Economic Releases
12:15 GMT, ADP Weekly Employment Change, prior 24.8K.
12:30 GMT, Building Permits, forecast 1.39M (prior 1.40M).
12:30 GMT, Housing Starts, forecast 1.30M (prior 1.28M).
14:00 GMT, Pending Home Sales m/m, forecast -0.4% (prior 0.3%).
20:30 GMT, API Weekly Statistical Bulletin.
Earnings After the Close
Netflix (NFLX), $0.82 per share.
Netflix is expected to report year-over-year earnings growth of 39% on revenue growth of 11.9% to $12.9 billion. The company’s content strategy is the issue after management replaced its chief content officer and announced layoffs affecting about 1,000 employees.
Wednesday, October 21
Earnings Before the Open
Abbott Laboratories (ABT), $1.42 per share.
AT&T (T), $0.60 per share.
CME Group (CME), $2.98 per share.
NextEra Energy (NEE), $1.18 per share.
Economic Releases
14:30 GMT, Crude Oil Inventories, prior -8.6M.
Earnings After the Close
Meta Platforms (META), $5.94 per share.
Tesla (TSLA), $0.45 per share.
IBM (IBM), $2.86 per share.
Lam Research (LRCX), $2.18 per share.
Texas Instruments (TXN), $2.42 per share.
Meta is expected to report year-over-year earnings-per-share growth of 465.7% on 23.6% revenue growth to $63.35 billion. Traders will be listening for capex plans and whether Muse AI is producing enough growth to support the spending.
Tesla reported 486,532 third-quarter vehicle deliveries, above estimates of 461,000 to 462,000. Analysts expect earnings per share to fall 10.0% from a year earlier on revenue of $28.11 billion.
Thursday, October 22
Earnings Before the Open
Honeywell (HON), $2.17 per share.
Procter & Gamble (PG), $1.88 per share.
Union Pacific (UNP), $3.47 per share.
Valero Energy (VLO), $20.90 per share.
Economic Releases
12:30 GMT, Unemployment Claims, forecast 200K (prior 199K).
14:00 GMT, CB Leading Index m/m, forecast -0.2% (prior -0.1%).
14:30 GMT, Natural Gas Storage, prior 67B.
Earnings After the Close
Western Digital (WDC), $4.08 per share.
Friday, October 23
Earnings Before the Open
American Express (AXP), $4.58 per share.
SLB (SLB), $0.62 per share.
Economic Releases
13:45 GMT, Flash Manufacturing PMI, forecast 55.5 (prior 55.9).
13:45 GMT, Flash Services PMI, forecast 58.0 (prior 58.8).
14:00 GMT, Revised UoM Consumer Sentiment, forecast 46.3 (prior 46.3).
14:00 GMT, Revised UoM Inflation Expectations, prior 4.7%.
Earnings After the Close
No reports scheduled.
Technical Outlook
Weekly Dow Jones Industrial Average Index
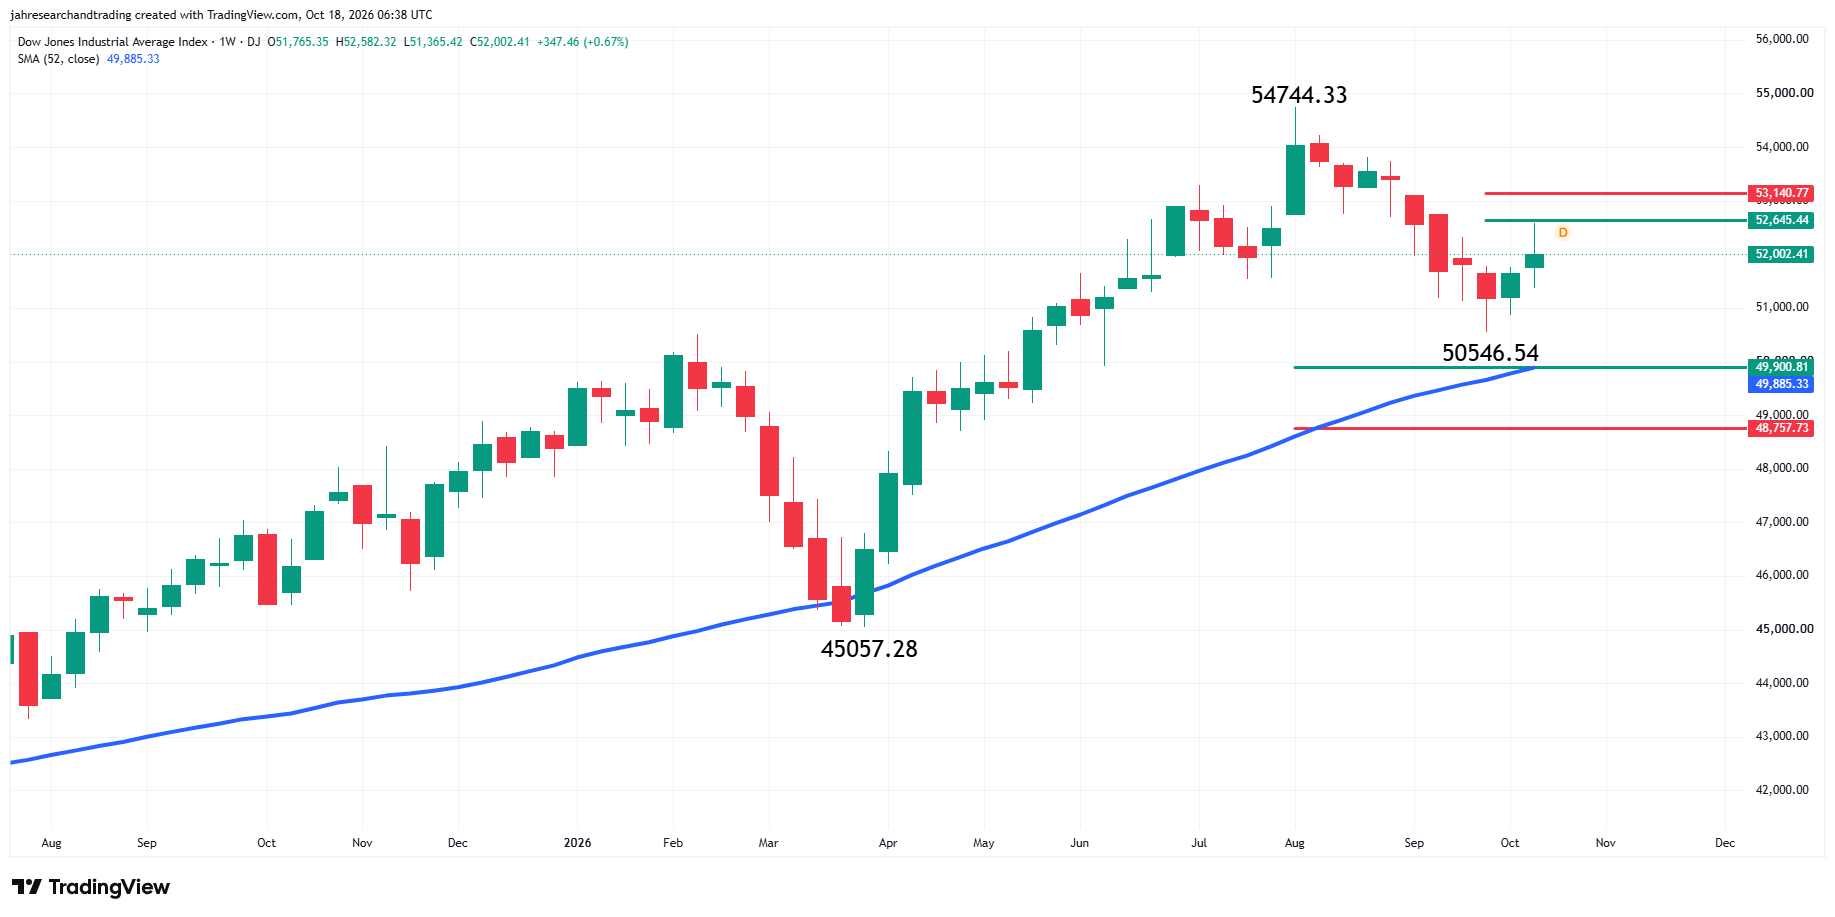
Dow Jones: 52,002.41 (-0.67%), Support at 50,546.54, 49,900.81, the 52-week SMA at 49,885.33, 48,757.73 and 45,057.28, Resistance at 52,645.44 and 53,140.77.
Weekly Nasdaq Composite Index
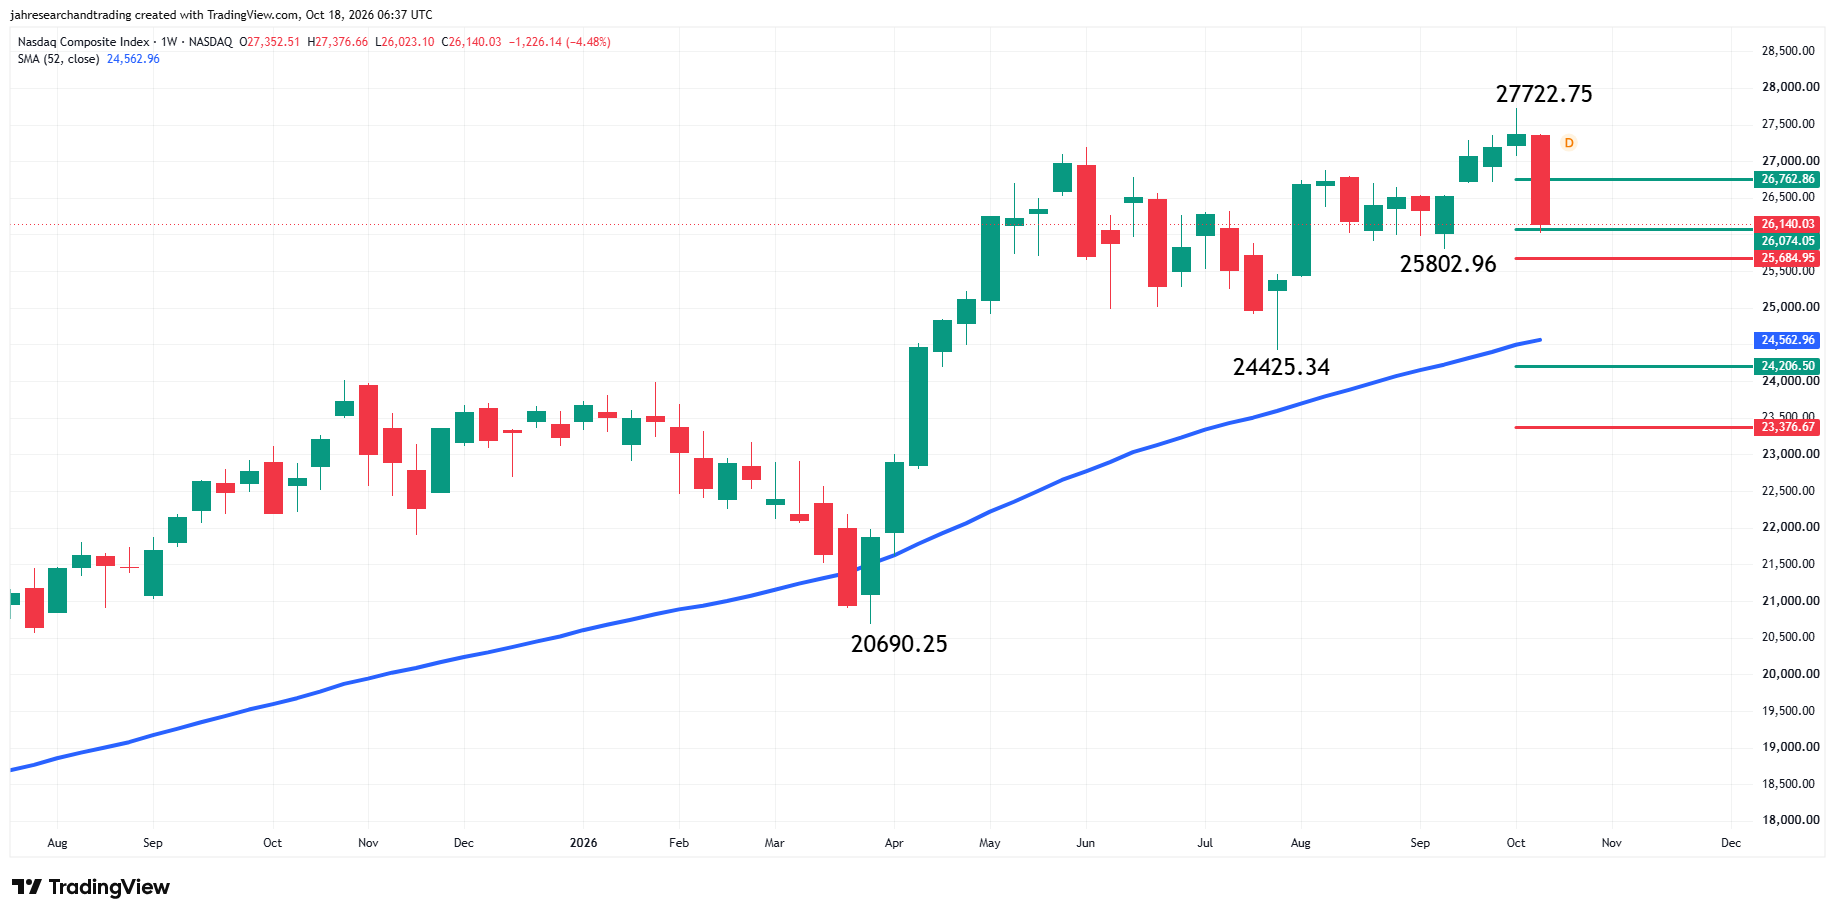
Nasdaq: 26,140.03 (-4.48%), Support at 26,074.05, 25802.96, 25,684.95, the 52-week SMA at 24,562.96, 24,425.34, 24,206.50 and 23,376.67, Resistance at 26,726.86 and 27,722.75.
Weekly S&P 500 Index
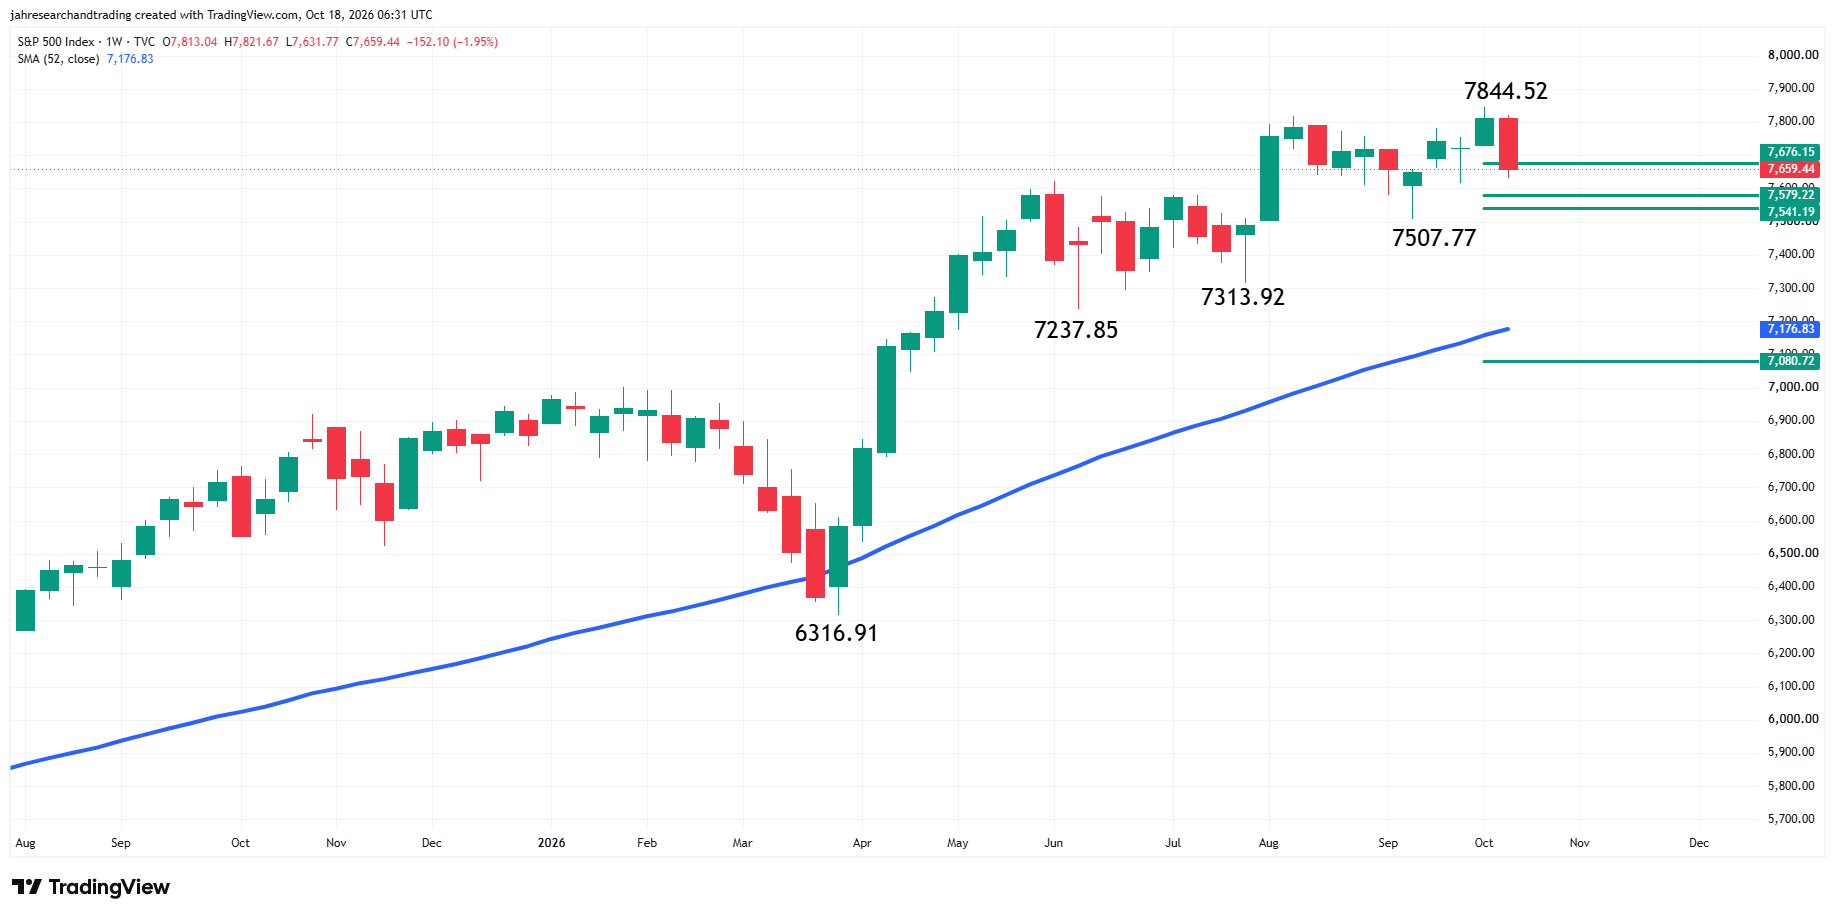
S&P 500: 7,659.44 (-1.95%), Support at 7,579.22, 7,541.19, 7,507.77, 7,313.92, 7,237.85, the 52-week SMA at 7,176.83 and 7,080.72, Resistance at 7,676.15 and 7,844.52.
All major indices remain above rising 52-week SMAs, confirming an intact long-term uptrend.
Outlook
The earnings calendar puts the AI trade under a microscope. Meta, Lam Research, Texas Instruments, Tesla and IBM will give traders an update on spending, demand and the cost of building AI capacity. Netflix, GE Aerospace, Procter & Gamble, American Express and SLB add consumer, industrial and energy reads to the week.
The Nasdaq starts the week closest to support after last week’s sharp break. Strong results and capex plans that show a return on AI spending could bring buyers back to technology. Weak guidance or more concern over debt financing would keep pressure on the Nasdaq’s 26,074.05 and 25,684.95 support levels, with the S&P 500 and Dow support areas also in play.