China Manufacturing Sector Contraction Sends Q3 Red Flags
China’s manufacturing sector continues to face scrutiny amid concerns that US tariffs could further hit demand for Chinese goods.
On Sunday, August 31, China’s NBS Manufacturing and Services PMI were closely watched as traders considered economic momentum through the third quarter.
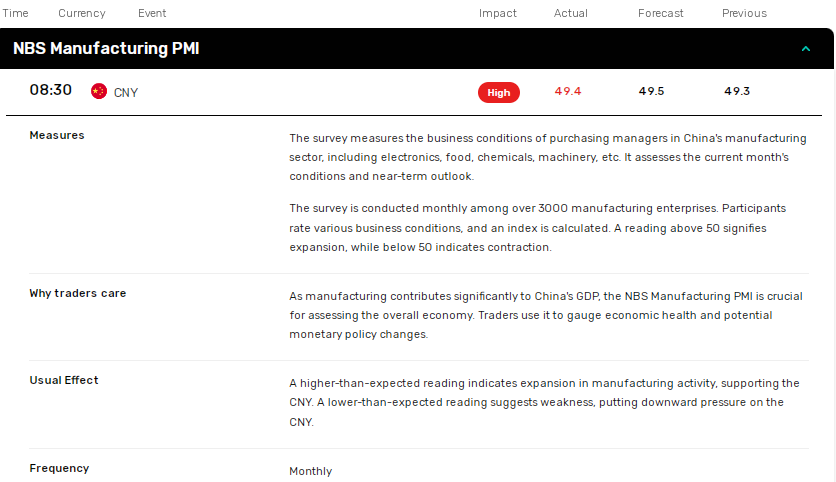
China’s National Bureau of Statistics (NBS) Manufacturing PMI rose slightly from 49.3 in July to 49.4 in August, but remained below 50, marking the fifth consecutive month of contraction. Meanwhile, the NBS Non-Manufacturing PMI edged up from 50.1 in July to 50.3 in August, indicating a modest expansion across the services sector.
Manufacturing Recovery and Industry Trends
CN Wire highlighted key trends in August’s PMI data:
- New Export Order Index edged up 0.1 percentage points to 47.2%, still well below the neutral 50 level.
- New order Index rose 0.1 percentage points to 49.5%.
- Employment Index fell 0.1 percentage points to 47.9%.
- Key raw material prices increased by 2.2 percentage points to 53.3, the highest since October 2024, potentially pressuring profit margins and the labor market.
Demand and Production Crucial Amid Waning Consumer Consumption
August’s manufacturing PMI could pressure Beijing to roll out fresh stimulus to counter the effects of US tariffs on external demand. While services sector activity picked up modestly, the upswing may not be enough to deliver Beijing’s 5% GDP growth target.
Chinese retail sales rose 3.7% year-on-year in July, down from a 4.8% increase in June. Meanwhile, the unemployment rate increased from 5% to 5.2% in July, as youth unemployment soared from 14.5% to 17.8%. A record number of graduates tipped the scales, spotlighting Beijing’s efforts to incentivize firms to implement graduate training schemes and hire fresh graduates.
From Factory Floors to Household Budgets
Weakening external demand and intensifying domestic competition impact selling prices, forcing firms to lower costs. Lower costs lead to lower wages, affecting disposable incomes and household spending.
AUD/USD Price Forecast
Every new AUD/USD analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all AUD/USD forecastsNatixis Asia Pacific Chief Economist Alicia Garcia Herrero recently commented:
“It is China’s manufacturing workers who suffer while exports – and the economy – keep growing despite the U.S. tariffs. It’s the people who are hammered by this model of huge competition, lower prices, thus you need to lower costs, thus you need to lower wages.”
Garcia Herrero added:
“It’s a spiral. The model is crazy. I’m sorry, but if you need to export at a loss, do not export. Statistics will not reveal Chinese workers as the main losers in the trade war because they will not become unemployed, but they will get unpaid leave of absence or work fewer hours.”
The manufacturing sector’s woes and modest growth across the services sector pose a challenge to Beijing’s shift toward a consumption-driven economy.
While the National Bureau of Statistics numbers offer insights, the Caixin PMI data typically has a greater impact on the markets. The Caixin PMIs will be out next week.
Key PMI Survey Differences
The NBS PMI primarily tracks large state-owned enterprises across China, while the Caixin PMI focuses on small- to mid-sized firms, particularly in coastal regions. As a result, the Caixin PMI often provides a more comprehensive picture of private sector performance.
Several Key Developments Could Dictate Market Sentiment:
It could be another crucial week for global markets. Traders should consider the following events and data for near-term AUD/USD and Hang Seng Index trends:
- US-China trade talks:
China’s chief trade negotiator Li Chenggang reportedly met with US officials last week to discuss trade. According to CN Wire, he met with representatives from the US Department of Commerce, the Office of the US Trade Representative, and the Treasury Department to discuss terms from previous agreements.
- China’s Economic Data Releases:
The Caixin Manufacturing PMI (September 1) and Caixin Services PMI (September 3) will influence sentiment. Weaker numbers would likely weigh on sentiment, though traders may lift expectations of further policy support from Beijing. On the other hand, upbeat data could boost demand for risk assets.
Market Trends and Outlook
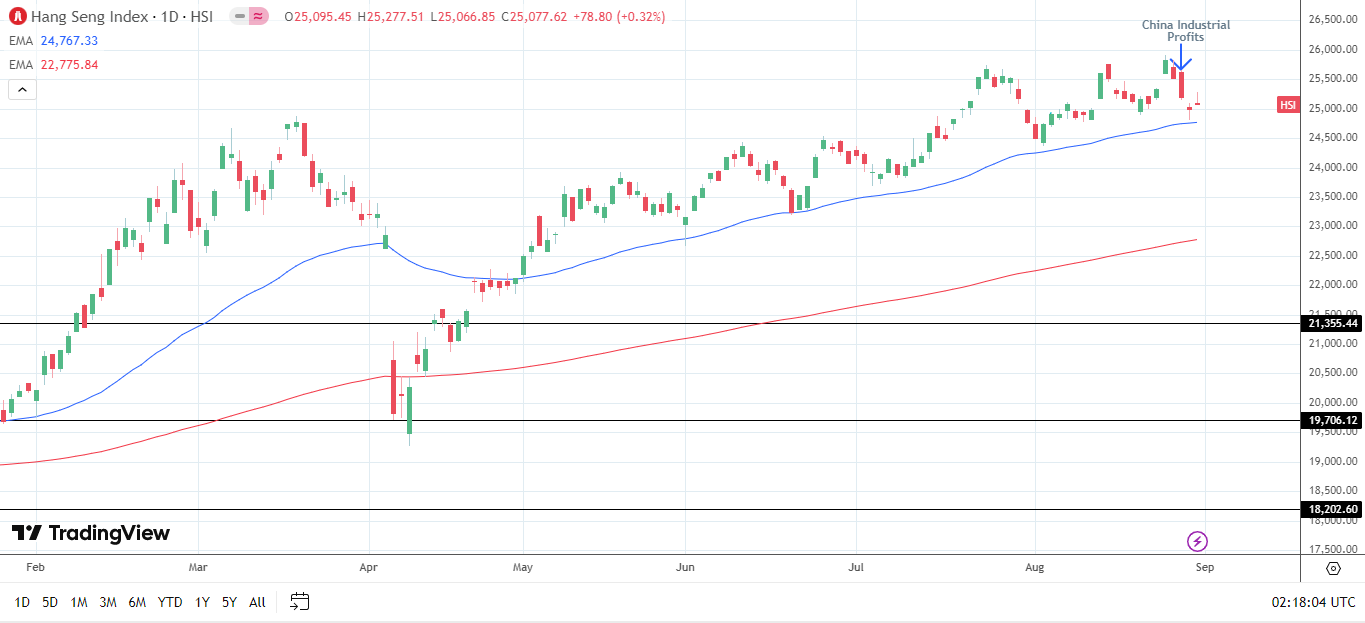
Mainland China’s CSI 300 and the Shanghai Composite Index gained 2.71% and 0.84%, respectively, in the week ending August 29, on hopes for a trade deal and fresh stimulus measures. However, the Hang Seng Index bucked the trend, falling 1.03%. Weakening Chinese industrial profits and shifts in sentiment toward Fed policy affected demand for Hong Kong-listed stocks.