


Mexico Targets Chinese Goods With Tariffs, Raising Trade War Stakes
China’s economy faces a pivotal test this quarter as tariff developments challenge the growth outlook. Recent economic indicators have raised concerns about Beijing achieving its 5% GDP growth target for 2025.
The US and China extended the trade war truce in August, leaving Chinese goods exposed to US tariffs averaging 55%. In contrast, Beijing maintained the 10% levy on US shipments bound for China.
Avoiding a sweeping 145% US tariff on shipments to the US was critical. However, the US administration’s proxy trade war via third-country tariffs continues to gain momentum. Reports of Mexico’s plans to raise tariffs on Chinese goods signal another roadblock, challenging efforts to bypass US tariffs.
Mexico has become a crucial hub for Chinese automakers targeting the US. BYD, Chery, and MG Motors have reportedly invested over $700 million in local plants. New tariffs on shipments to Mexico, coupled with existing US tariffs on Mexican exports, could dent demand for Chinese autos and parts.
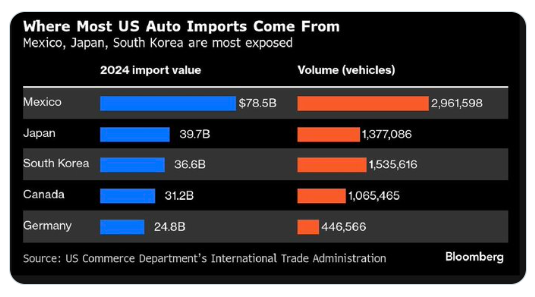
For context, Mexico accounted for the largest share of US auto imports, underscoring Mexico’s importance for auto manufacturers.
Did the US Government Push Mexico to Target Chinese Shipments?
In July, the US administration targeted another of China’s key trade routes, Southeast Asia. A 40% US levy on transshipments from Vietnam and a 19% tariff on Indonesian goods could affect Chinese exports. Chinese exports surged 7.2% year-on-year in July, up from 5.8% in June, with Southeast Asia driving growth. But August data will show whether fresh tariffs start to bite.
CN Wire commented on July’s trade data, stating:
“This export resilience persists despite high U.S. tariffs, indicating strong global demand continues to support China’s economy. […]. However, whether this momentum will last remains uncertain, as front-loading effects may fade.”
Mexico’s tariff news follows reports of the US administration planning to impose rules of origin for indirect shipments.
Natixis Asia Pacific Chief Economist Alicia Garcia Herrero commented on China’s outlook for terms of trade, stating:
“Rerouting will be much harder in the second half. So that’s going to hit Chinese exports indirectly. So, that’s why the second half is tougher and the government has been preparing.”
The latest trade developments came as the US and China prepare for the next round of trade talks. China’s chief trade negotiator Li Chenggang plans to return to Washington to discuss trade terms. The outcome of trade talks could be crucial given China’s reliance on ‘third countries’ and tariffs targeting Chinese shipments.
Hong Kong Hang Seng Price Forecast
Every new Hong Kong Hang Seng analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Hong Kong Hang Seng forecastsMainland Stock Markets Resume Move Toward Record Highs
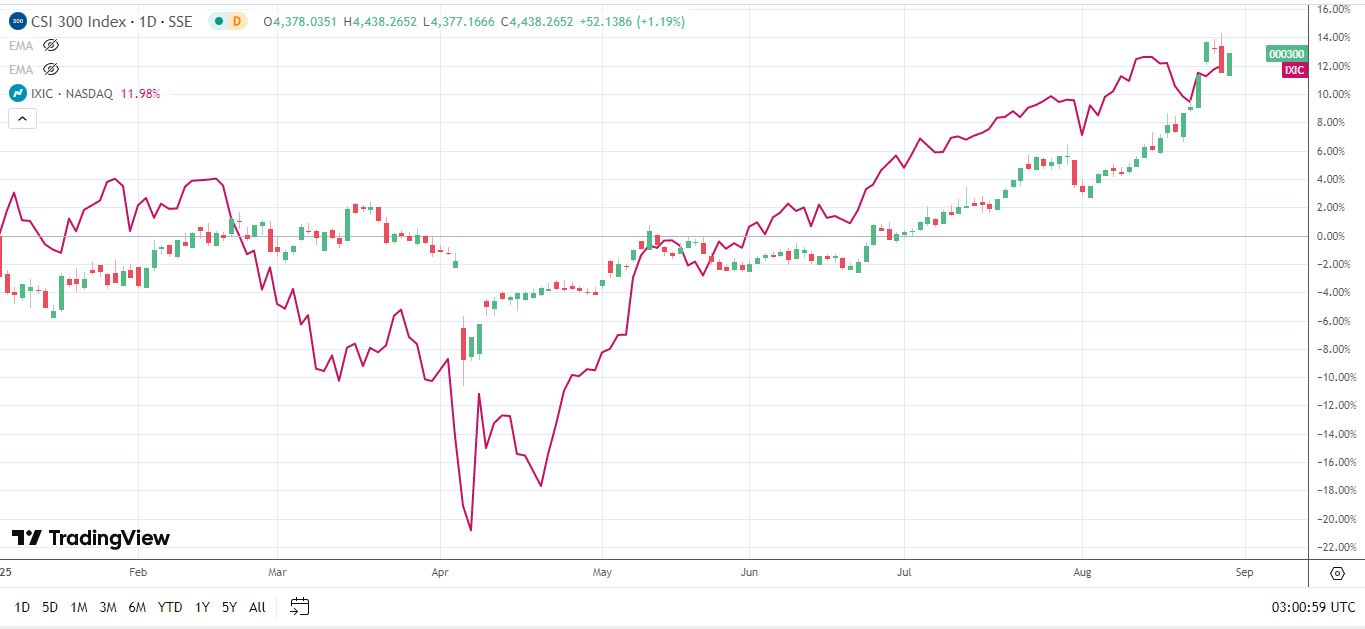
On Wednesday, August 27, Mainland China’s CSI 300 and the Shanghai Composite Index pulled back 1.49% and 1.76%, respectively, after briefly reaching new year-to-date highs.
Despite the retreat, optimism over Beijing’s 5% GDP growth target, supported by policy measures, continues to bolster demand for Mainland-listed stocks. The CSI 300 and the Shanghai Composite were up 1.19% and 0.58%, respectively, during the August 28 morning session.
Both indexes continue to outperform the Nasdaq Composite Index but trail the Hang Seng Index year-to-date. CSI 300 gained 9.4% in August and 12.7% YTD. Shanghai Composite rose 8.5% in August and 14.1% YTD. The Hang Seng leads, up 24.8% YTD, well ahead of the Nasdaq’s 11.8%
Trade developments and Beijing’s next stimulus measures remain crucial to market momentum. An escalation in US-China trade tensions and delays in fresh stimulus could unravel the bullish sentiment.
The Road Ahead: Trade Talks and Stimulus
The next moves in US-China trade talks and Beijing’s stimulus drive will set the tone for markets in the coming weeks.
However, crucial economic indicators will also affect market trends. August’s NBS private sector PMIs on Sunday, August 31 and September 1 will draw interest. The PMIs will reveal whether tariffs added more pressure on China’s manufacturing sector midway through Q3. Weak numbers could raise expectations of fresh stimulus from Beijing.
Track our real-time updates on China trade policy and equity market trends, and consult our economic calendar.