International markets opened Monday with competing pressures. This included falling oil, offering some initial relief from energy costs, while French political unrest intensified concerns about sovereign borrowing. Equity futures in the United States recovered, but European assets faced a more difficult session. It suggests that investors are distinguishing between a modest improvement in the global inflation backdrop and risk concentrated in individual economies, including France.
Oil Remains Central to That Balance
Brent futures have recovered quite a bit but remain within the previous range. West Texas Intermediate was down slightly at the open as well, but has since bounced. The Brent market finished Friday’s session at the highest level since May 19. Monday’s decline represents more or less a retreat from elevated prices rather than evidence that energy pressures are disappearing.
Russian Sanctions
Russian sanctions policy has added some uncertainty, as President Donald Trump signed an order waiving some sanctions and tariffs relating to Russian exports. Asian market reports also noted his subsequent statement that a final decision had not been made. This qualification will matter, as the prospect of more available Russian crude cannot be treated as a settled increase in physical deliveries.
Meanwhile, Iranians are reporting that a tanker struck a mine in the Strait of Hormuz on Sunday. This remains a shaky report, though, rather than one that has been independently established. The economic implication is conditional but significant. Persistent shipping disruptions could affect and offset relief from Russian supply and keep transport insurance and fuel costs elevated.
Treasuries Continue to Move
Treasuries show how quickly the morning’s interpretation could change. The 2-year yield reversed an earlier decline pretty quickly as New York came online, and the 10-year yield similarly reversed its earlier decline.
Brent Oil Price Forecast
Every new Brent Oil analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Brent Oil forecastsFrance Continues to See Problems
France faced a more distinct repricing, though. The French 10-year yield was at 4.866%, up 7.8 basis points, while Germany’s 10-year yield rose 1 basis point to 3.42%. The French premium has now reached 145 basis points, a two-week high. The concern is the interaction between domestic unrest and the government’s ability to deliver budget consolidation.
The bond sell-off has been linked to demonstrations and uncertainty around deficit reduction in market terms. Higher sovereign borrowing costs will complicate fiscal repair, while doubts about that repair can remain a constant fuel for the larger premiums that investors will demand.
Euro Relatively Stable, Though
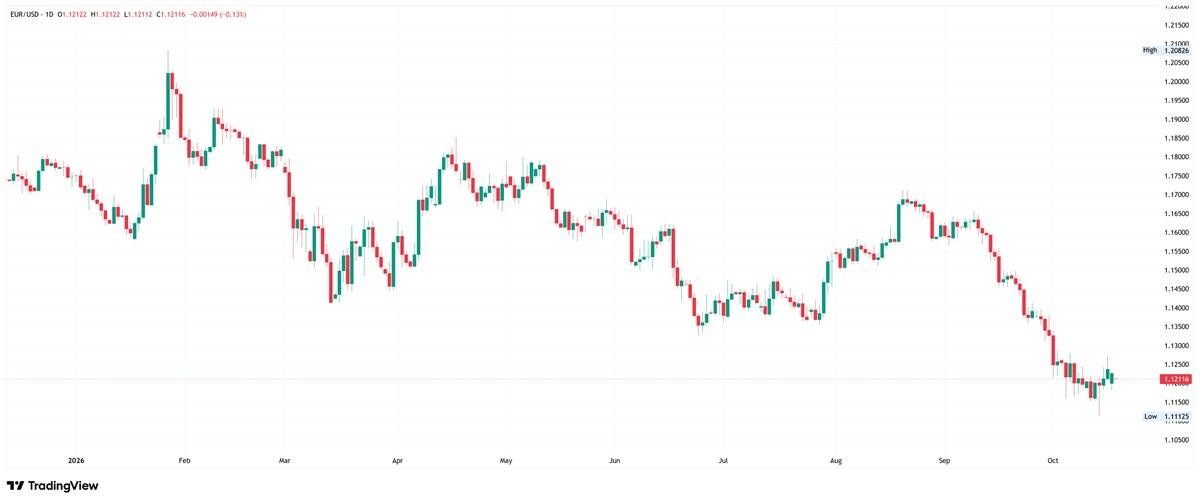
Currency trading has reflected Europe’s difficulties, with the euro drifting a little lower, although it is probably worth noting that trading is somewhat subdued. A softer oil market did not transform into uniform dollar weakness this time. Relative political risk and the direction of interest-rate differentials remain important alongside global risk appetite.
China, a Mixed Picture
China supplied a firmer growth headline. The National Bureau of Statistics reported third-quarter GDP growth of 4.5% year-over-year, accelerating from 4.3% in the second quarter. Output increased 1.2% quarter-over-quarter. However, it is worth noting that September retail sales grew only 1.1% annually, compared with industrial production growth of 5.5%. This combination suggests resilience in production without an equally strong recovery in domestic spending.
For international markets, this distinction will matter. Stronger Chinese output does not automatically imply a broad acceleration in household or construction-related demand.
U.S. technology faced another immediate test, with Nasdaq futures rising while S&P 500 futures were up as well. Financing costs and evidence of returns on AI spending remain central questions for the market. Beyond earnings and energy headlines, the Federal Reserve’s next scheduled meeting is October 27 and 28, with its decision due October 28 at 2 p.m. EDT.