UK Core Inflation Slows in September, Lifting BoE Rate Cut Bets
UK core inflation unexpectedly cooled in September, boosting bets on a near-term Bank of England rate cut. The downside surprise follows easing wage pressures, offering clearer guidance on the BoE’s policy outlook ahead of key economic data later this month.
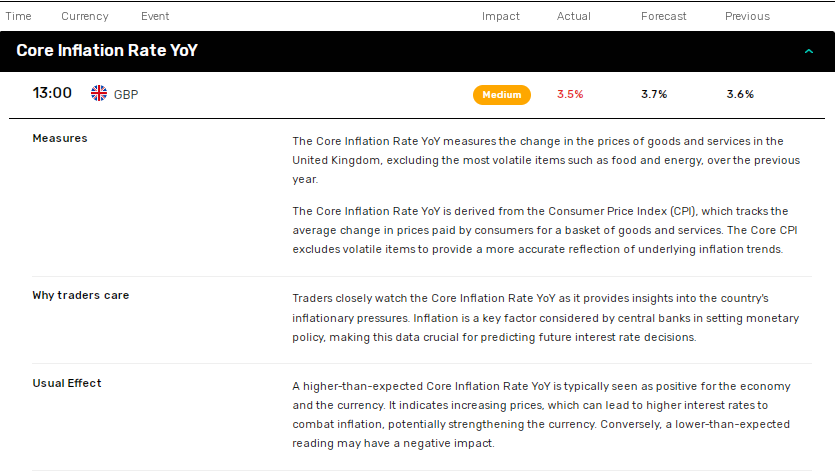
The UK’s annual inflation rate (headline) remained steady at 3.8% in September, while core inflation fell to 3.5% (August: 3.6%). Consumer prices were flat month-on-month in September after increasing 0.3% in August. Economists had expected a pickup in inflationary pressures.
Key Data from the Office for National Statistics included:
- The Consumer Prices Index, including owner-occupier housing costs (CPIH), increased 4.1% in the 12 months to September, unchanged from August.
- The largest upward contribution came from transport, offsetting a downward contribution from recreation and culture, and food and non-alcoholic beverages.
- The Core CPIH (excluding energy, food, alcohol, and tobacco) rose by 3.9% in the 12 months to September, down from 4.0% in August.
- The CPI services annual rate was unchanged at 4.7% in September.
UK Economic Indicators Send Mixed Signals
The inflation report followed August’s UK GDP and labor market data. The UK economy rebounded in August, expanding 0.1% after contracting 0.1% in July, contributing to a higher quarterly print (0.3% vs. 0.2%).
However, the labor market report suggested a potential pullback in consumer spending. Private sector pay slowed from 4.7% year-on-year in July to 4.4% in August. Meanwhile, the unemployment rate rose from 4.7% in July to 4.8% in August.
Rising unemployment may slow wage growth further and curb consumer spending. Weaker spending may dampen demand-driven inflation, supporting a more dovish BoE policy stance.
September’s inflation data suggests the BoE could consider cutting rates in December.
Before the inflation report, Economists had already flagged BoE monetary policy uncertainty. ING Economics commented on the labor market data, forecasting a February rate cut, stating:
“A November rate cut now looks unlikely. But December is in play, given that this meeting falls after the budget. And assuming we see further falls in wage growth, coupled with a bit of undershooting on the Bank’s services inflation forecasts, then a Christmas rate cut is possible. However, we think February is more likely, giving the Bank an extra month’s worth of data to look at before acting.”
Furthermore, ING is projecting a more dovish BoE rate path, with three cuts in 2026. Today’s inflation figures raise the likelihood of a cut in December.
GBP/USD Price Forecast
Every new GBP/USD analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all GBP/USD forecastsGBP/USD Volatility Post-Inflation Data
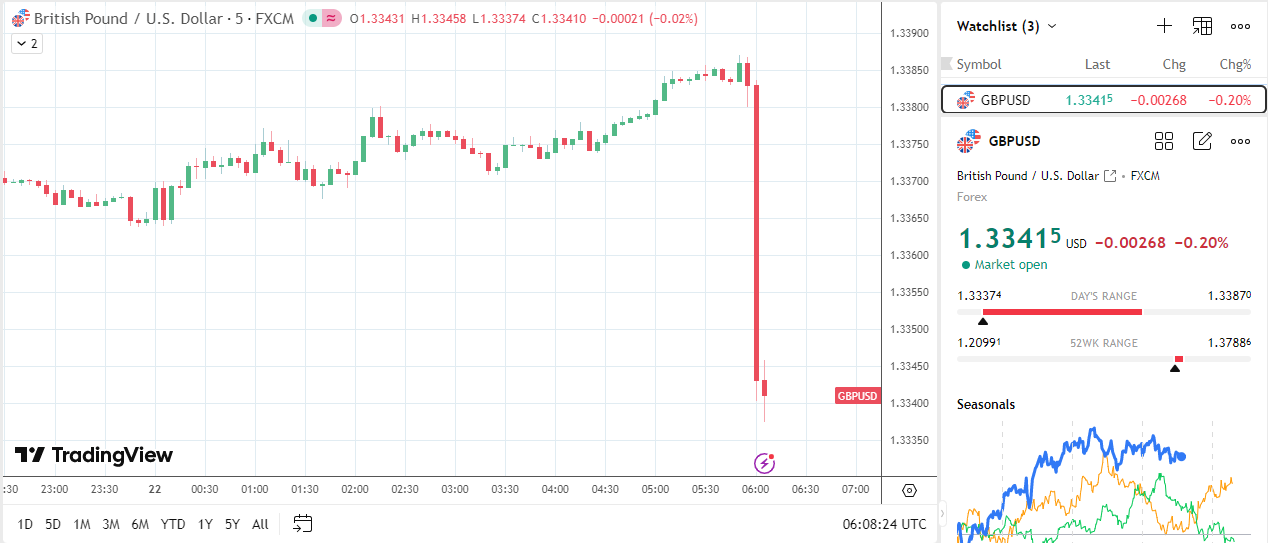
Ahead of the inflation report, the GBP/USD briefly dropped to a low of $1.33580 before climbing to a high of $1.33848. Following the report, the pair tumbled from $1.33836 to $1.33374.
On Wednesday, October 22, the GBP/USD was down 0.20% to $1.33415, reflecting increased market bets on a December BoE rate cut.
Looking Ahead
The next round of PMI and retail data could set the tone for the BoE’s next policy move.
Given that the services sector accounts for over 70% of the UK GDP, and private consumption more than 60% of GDP, a sharp drop in the Services PMI and retail sales may raise the chances of a December rate cut.
On the other hand, a pickup in services sector activity and resilient retail sales may push the first BoE rate cut into 2026.
Stay updated here with real-time insights into BoE policy, GBP forecasts, global macro trends, and other central bank developments.