Dollar Dips Within Key Range as Traders Focus on Politics, Yields, and China Data
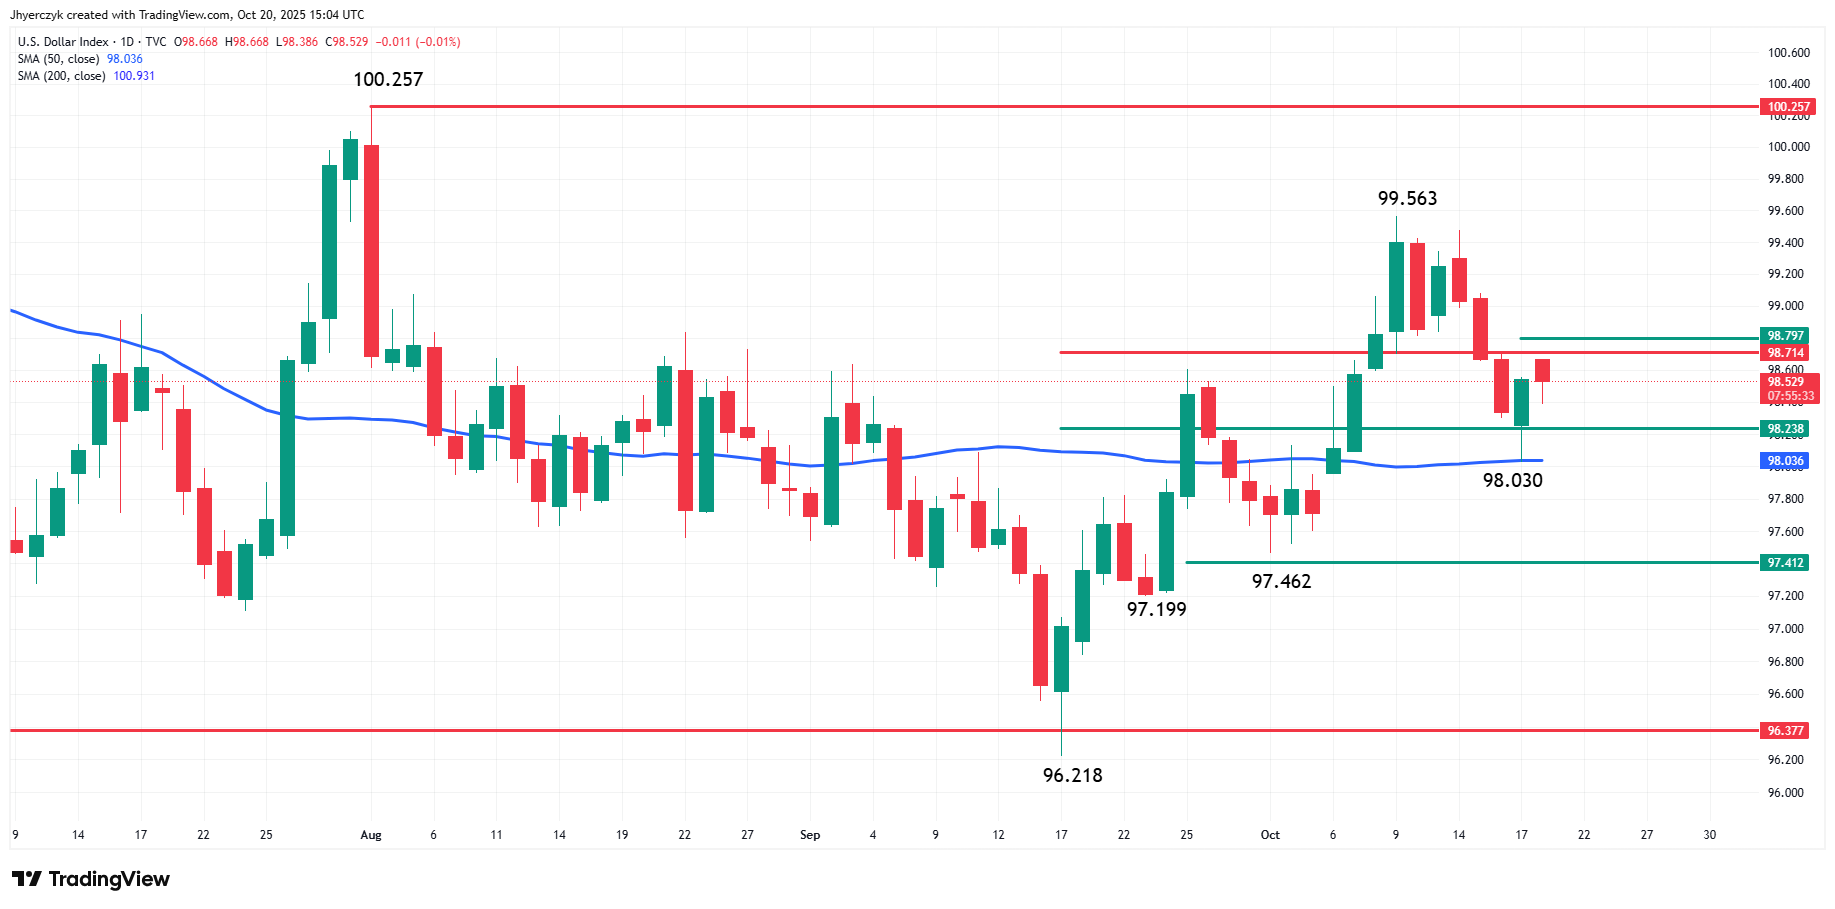
The U.S. Dollar Index (DXY) edged lower on Monday, testing a critical technical band between 98.238 and 98.714. Price action remained confined within this retracement zone, as traders weighed political developments in Japan and Europe, alongside signs of stability in U.S.-China trade relations and a cautious bond market.
At 15:03 GMT, DXY is trading 98.520, down 0.020 or -0.02%.
The dollar rose against the yen but slipped against the euro, reflecting diverging regional political and fiscal expectations. In Japan, the prospect of hardline conservative Sanae Takaichi becoming the country’s first female prime minister triggered renewed expectations of fiscal expansion, pressuring the yen.
The USD/JPY climbed 0.1% to 150.75, after touching 151.20 earlier. BOJ board member Hajime Takata’s push for rate hikes did provide temporary support, but overall sentiment remained tilted against the yen amid Nikkei’s 3% rally.
Euro Edges Up on French Political Breather
The euro gained modestly to $1.1664 following signs of reduced political tension in France. However, investor sentiment remained fragile, with budget negotiations still unresolved.
While President Macron’s government froze its pension reform, traders remain cautious as fiscal constraints tighten ahead of Q4 budgetary discussions. ING’s Francesco Pesole noted that further deterioration in U.S. credit sentiment could push the euro higher, with the $1.180 mark being eyed by some strategists.
EUR/USD Price Forecast
Every new EUR/USD analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all EUR/USD forecastsBond Market Flat as Shutdown Concerns Linger
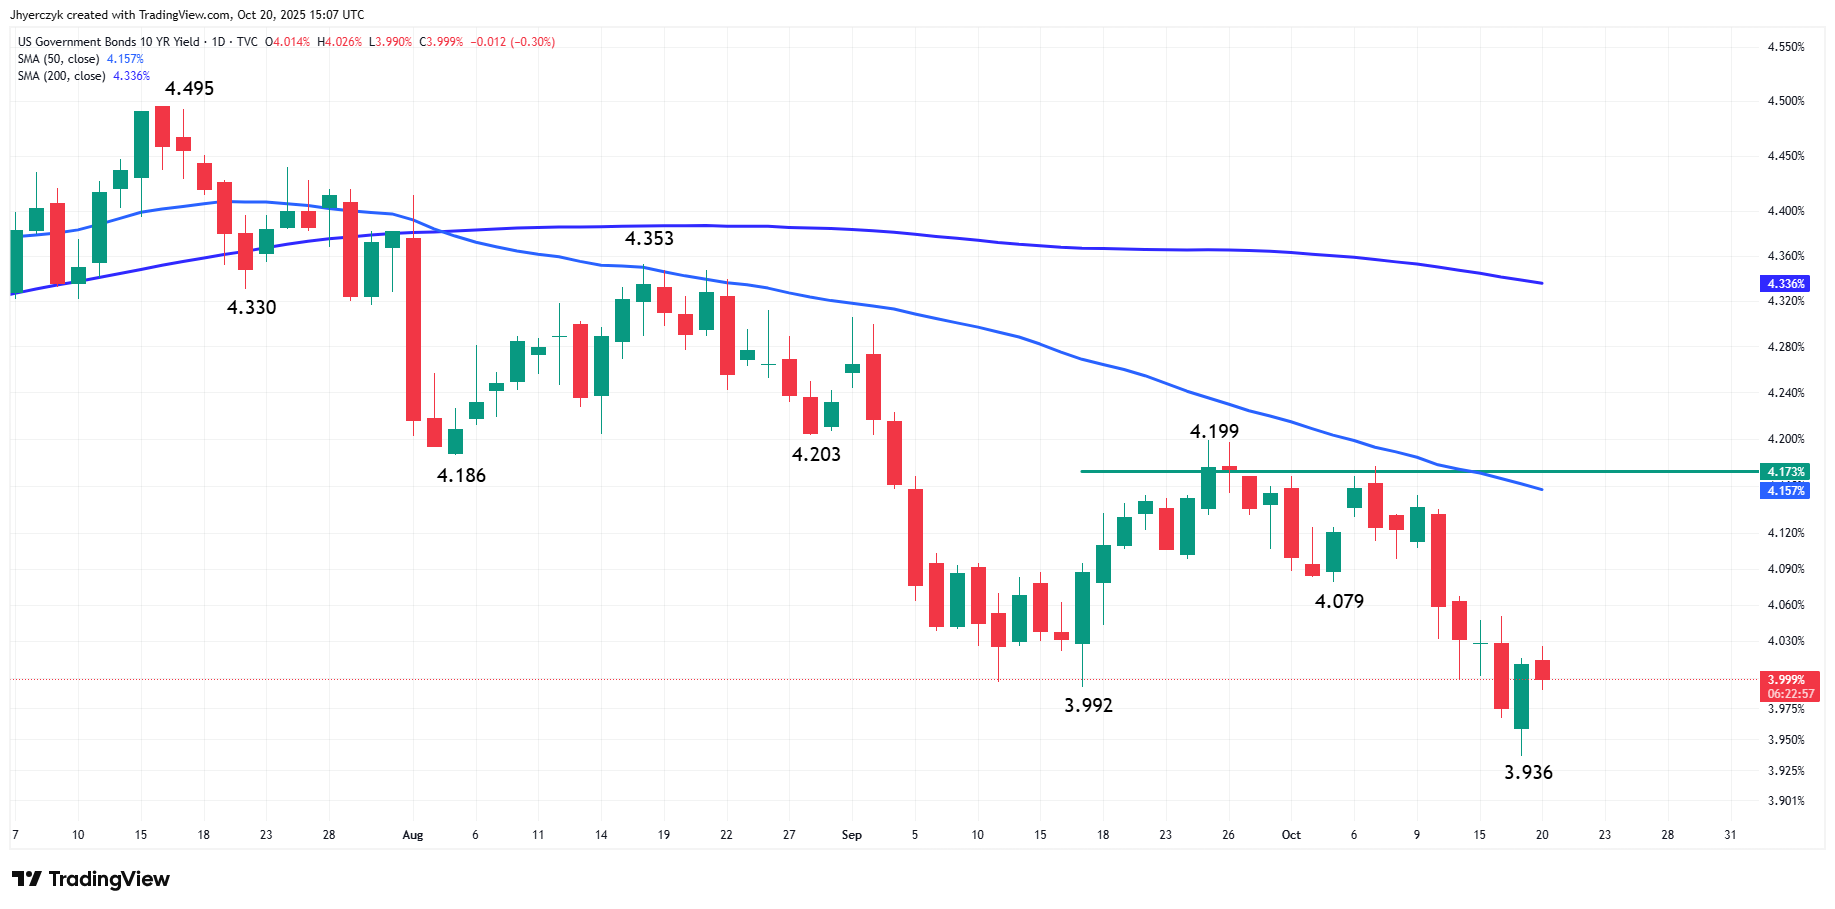
U.S. Treasury yields were mostly unchanged, with the 10-year yield slipping below 4% to 3.995%. The market remains sensitive to the ongoing government shutdown, now in its fourth week, which has delayed the release of key data.
Investors await the postponed September CPI report on Friday, which will provide critical input ahead of next week’s FOMC meeting. While the shutdown has yet to trigger significant repricing in rates, economists warn of possible short-term drag on GDP.
China Growth Data Supports Risk Sentiment
Risk sentiment was marginally supported by stronger-than-expected Q3 economic data out of China. The economy expanded 1.1% quarter-on-quarter and 6.5% in industrial output, helping to lift the Australian dollar 0.3% to $0.6504. Market participants interpreted the data as a sign of resilience to U.S. tariffs. Comments from U.S. and Chinese officials suggested de-escalation in tariff threats, further calming investor nerves.
DXY Outlook: Cautious Bearish Bias Prevails
With the DXY struggling to hold above the 98.714 level, trader behavior suggests resistance remains firm. Failure to reclaim this threshold keeps the focus on the 50% retracement at 98.238.
Continued lack of upward momentum, combined with political crosscurrents and lower yields, implies a short-term bearish bias for the U.S. dollar—unless upcoming CPI data or FOMC guidance changes the broader market narrative.
More Information in our Economic Calendar.