Weekly Analysis and Recommendations:
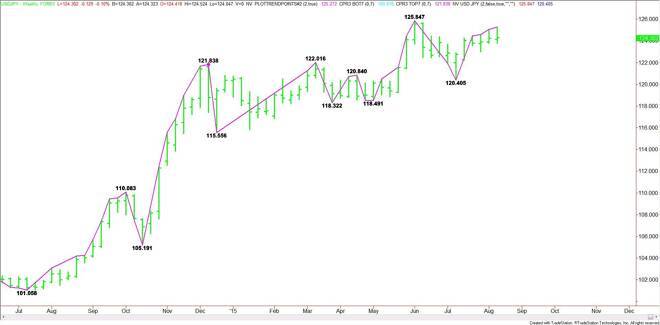
The USD/JPY posted a number of volatile swings last week before closing lower. The volatile moves were triggered when the People’s Bank of China shocked the financial markets by devaluing the Yuan three consecutive sessions. The Greenback surged to a two-month high against the Yen on the central bank’s moves before China intervened to drive the U.S. Dollar lower.
Also influencing the price action were the volatile swings in U.S. equity markets. Traders also reacted to the possibility the Fed will refrain from an interest rate hike in September. According to traders, there is a 50 percent probability the Fed will raise its benchmark rate in September, and 73 percent odds of a move by year-end.
Barring any more surprise moves by the People’s Bank of China, the focus this week will be on Japan’s 2Q GDP report due out on Monday. The report is expected to show economic growth fell 0.5% last quarter, down from the first quarter’s 1.0% reading. The Preliminary GDP Price Index is expected to show a reading of 2.2%, down from the previous 3.4% reading.
Economic data on Wednesday and Thursday are expected to produce the most volatility. Early Wednesday, the U.S. will release its latest consumer inflation data. This report is important because along with labor data, consumer inflation is a key factor in the Fed’s decision to raise rates. The report is expected to show the CPI held steady at 0.2%.This number may not be impressive enough to convince the Fed to raise rates, however. Last week, Federal Reserve Vice Chairman Stanley Fischer suggested a September rate hike is not a done deal because of low inflation.
Also on Wednesday, the Fed will release its latest minutes. The minutes could reveal more insight as to the odds of a September rate hike. Some traders are already convinced that the Fed has taken an early rate hike off the table because of the actions by China last week.
On Thursday, the Bank of Japan monetary policy statement will be followed by a press conference. On August 7, the BoJ kept its accommodative monetary policy, aiming toward 2% inflation without additional monetary easing. Economists, however, believe the 2% target may be changed, depending on the future outlook of oil prices. Because of last week’s Chinese yuan devaluation, this meeting will be watched more closely by investors.
All data aside, the biggest influence on the USD/JPY over the near-term is likely to be the U.S. equity markets. Stock market weakness is likely to drive down the U.S. Dollar while stock market strength is likely to pressure the Japanese Yen. This is because of the carry trade.

Date Time Curr Event Forecast Previous
|
Sun Aug 16 |
7:50pm ET |
JPY |
Prelim GDP q/q |
-0.5% |
1.0% |
||||
|
JPY |
Prelim GDP Price Index y/y |
2.2%
3.4%
Mon Aug 17
8:30am ET
USD
Empire State Manufacturing Index
5.0
3.9
10:00am ET
USD
NAHB Housing Market Index
62
60
4:00pm ET
USD
TIC Long-Term Purchases
93.0B
Tue Aug 18
8:30am ET
USD
Building Permits
1.21M
1.34M
USD
Housing Starts
1.20M
1.17M
7:50pm ET
JPY
Trade Balance
-0.16T
-0.25T
Wed Aug 19
12:30am ET
JPY
All Industries Activity m/m
0.4%
-0.5%
8:30am ET
USD
CPI m/m
0.2%
0.3%
USD
Core CPI m/m
0.2%
0.2%
10:30am ET
USD
Crude Oil Inventories
-1.7M
2:00pm ET
USD
FOMC Meeting Minutes
Tentative
JPY
Monetary Policy Statement
Thu Aug 20
Tentative
JPY
BOJ Press Conference
2:45am ET
USD
FOMC Member Williams Speaks
8:30am ET
USD
Unemployment Claims
272K
274K
10:00am ET
USD
Philly Fed Manufacturing Index
7.2
5.7
USD
Existing Home Sales
5.45M
5.49M
USD
CB Leading Index m/m
0.2%
0.6%
10:30am ET
USD
Natural Gas Storage
65B
9:35pm ET
JPY
Flash Manufacturing PMI
51.2
Fri Aug 21
9:45am ET
USD
Flash Manufacturing PMI
53.5
53.8