China’s Caixin Services PMI Slumps Amid Economic Headwinds
Service sector activity slows despite easing US-China trade tensions. On Thursday, July 3, China’s private sector faced increased scrutiny after mixed economic data sent mixed signals earlier in the week.
The Caixin Services PMI fell from 51.1 in May to 50.6 in June, crucially holding above the neutral 50 level. Key takeaways from the June survey included:
- Weaker global conditions slowed new business growth.
- New export orders declined for a second month, the fastest since December 2022.
- Rising costs and weaker orders prompted job cuts.
- Average input costs increased, but the rate of input cost inflation eased to a three-month low.
- Service providers cut output prices to stay competitive, eroding profit margins. Selling prices fell at the quickest pace since April 2022.
- Despite the economic headwinds, optimism rose for the second month but trended below the long-run average.
Meanwhile, the Caixin Composite PMI rose from 49.6 in May to 51.3 in June, moving above the 50 neutral level. A pickup in manufacturing sector activity offset waning service sector activity. However, there were common themes across the private sector, including softer overseas demand and deteriorating labor market conditions.
June’s trends may pressure Beijing to introduce fresh measures to counter weakening overseas demand by targeting domestic consumption. However, employment trends could challenge efforts to drive private consumption without measures to boost job creation.
Expert Views on China’s Private Sector: Is More Stimulus on the Horizon?
Dr. Wang Zhe, Senior Economist at Caixin Insight Group, remarked on the June survey, stating:
“Recently, major macroeconomic indicators have shown divergence, with consumption in certain sectors increasing beyond expectations, while the momentum of growth in investment and industrial production has weakened. Market participants’ expectations remain weak. While some of the existing stimulus policies may have front-loaded short-term consumption, unleashing consumption potential in the long term still relies on stabilizing employment, reinforcing confidence, and increasing incomes.”
Natixis Asia Pacific Chief Economist Alicia Garcia Herrero recently remarked on corporate profit margin trends, stating:
“Cost of over-competition- but also US tariffs, clearly hurting Chinese companies. Corporate profits fell 9.1% in May. Unsustainable without additional subsidies.”
Notably, firms across the private sector absorbed rising costs due to the competitive landscape, suggesting continued corporate profit woes. Failure to introduce further subsidies may place extra pressure on the labor market. Manufacturers and service providers may need to lower staffing levels to manage fixed costs and limit the impact of competition on profit growth.
East Asia Econ remarked on China’s manufacturing sector PMI numbers from earlier in the week, stating:
“The Caixin PMI rose above 50 in June, but only to 50.4. Comments remained cautious. “Firms were generally cautious with hiring on the back of cost control”. A ‘fourth monthly reduction in average input costs’ was shared with clients, resulting in another decline in average selling prices measures.”
The Caixin Manufacturing PMI rose from 48.3 in May to 50.4 in June despite falling new export orders, pricing issues and job losses.
Hong Kong Hang Seng Price Forecast
Every new Hong Kong Hang Seng analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Hong Kong Hang Seng forecastsHang Seng Index Drops as Markets Eye Beijing for Stimulus
Investors reacted to the weaker-than-expected Caixin Services PMI and concerns about waning overseas demand, the labor market, and corporate profits.
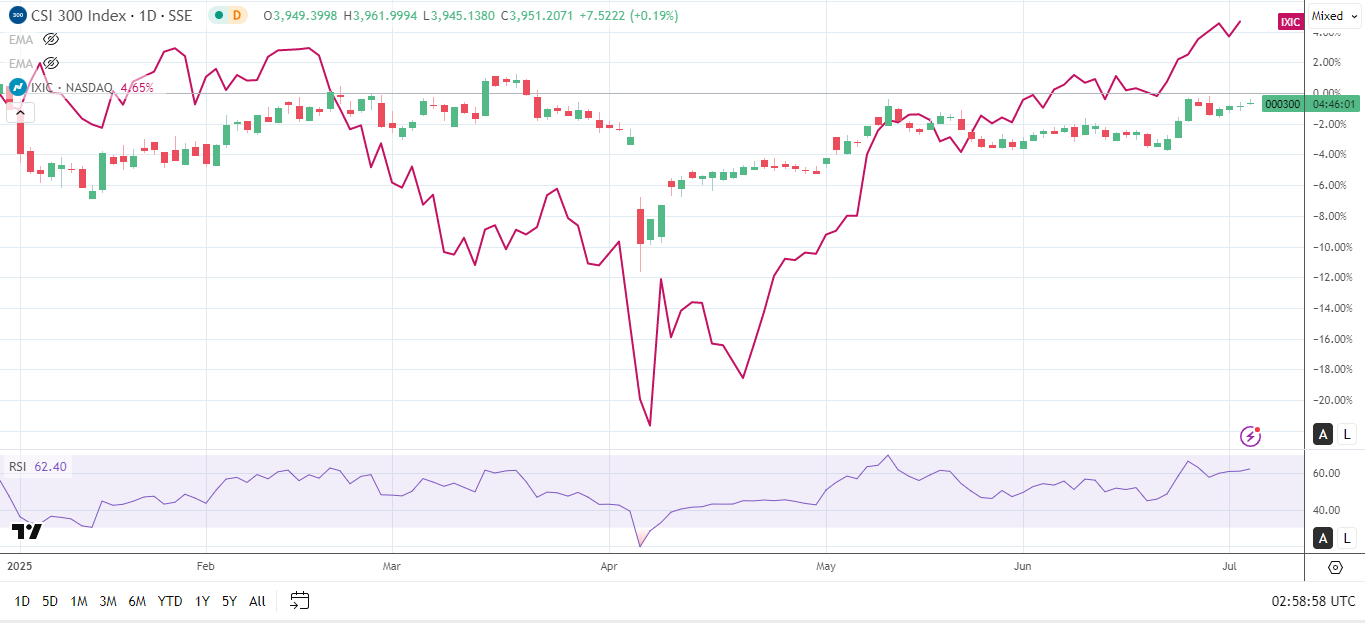
The Hang Seng Index dropped 1.09% to 23,955. However, Mainland China stocks had a mixed morning session. The CSI 300 gained 0.21%, while the Shanghai Composite Index fell 0.11% in early trading. Hopes for further stimulus from Beijing to bolster the labor market and boost domestic consumption cushioned the losses for the Hang Seng and Shanghai Composite Index.
Still, Mainland markets maintained modest YTD gains amid investor stimulus hopes. The CSI 300 was up 0.39% YTD, with the Shanghai Composite Index up 2.92%. While the mainland markets trailed the Nasdaq Composite Index, up 5.60% YTD, the Hang Seng Index led the way, soaring 19.29% YTD, benefiting from Mainland investor demand.
Outlook
Trade developments remain crucial as the US and China agree to ease restrictions on key exports, including rare earth minerals and tech. However, US tariffs on China could continue eroding external demand and profits. Signs of progress toward lifting tariffs and further stimulus from Beijing could drive demand for Mainland and Hong Kong-listed stocks. Conversely, breaches of the US-China trade agreement and an absence of fresh stimulus may weigh on sentiment.
Follow our coverage as US-China tech tensions reshape global markets and consult our economic calendar.