Market Overview
U.S. equities closed lower last week as the selloff in semiconductors and other AI-related shares outweighed strength in cyclical and defensive sectors. The Dow Jones Industrial Average settled at 52,146.42, down 490.59 points or 0.93% for the week. The S&P 500 Index closed at 7,457.69, down 117.70 points or 1.55%, while the Nasdaq Composite finished at 25,520.24, down 761.36 points or 2.90%.
The pullback followed a strong first-half rally in technology. Semiconductor stocks have taken the heaviest selling, with the SOX Semiconductor Index down about 20% from its June high, although it remains up roughly 64% for the year. Software and cloud shares, including Microsoft and Salesforce, have held up better while AI infrastructure stocks lag.
This week’s calendar is light on major economic reports, placing more attention on earnings. Alphabet, Tesla, ServiceNow, Texas Instruments and Intel lead a packed technology calendar. Their guidance on AI capital spending, cloud demand, server demand and returns on investment will be the week’s central market test.
S&P 500 earnings growth forecasts have risen from about 14% year-over-year to about 25%, led by energy and technology. Technology-sector earnings growth is forecast at about 63%, contributing more than half of overall S&P 500 earnings growth.
Economic Releases & Notable Earnings
Monday, July 20
Before the Open:
- Domino’s Pizza (DPZ), est. $4.17
Economic Releases:
- 14:00 GMT – CB Leading Index m/m, forecast -0.1%, prior 0.1%
After the Close:
- BOK Financial (BOKF), est. $2.68
- Steel Dynamics (STLD), est. $3.64
- W.R. Berkley (WRB), est. $1.08
- Zions Bancorp (ZION), est. $1.57
Tuesday, July 21
Before the Open:
- 3M (MMM), est. $2.25
- Charles Schwab (SCHW), est. $1.56
- D.R. Horton (DHI), est. $2.97
- Danaher (DHR), est. $1.84
- General Motors (GM), est. $3.19
- Halliburton (HAL), est. $0.54
- Northrop Grumman (NOC), est. $6.82
Economic Releases:
- 12:15 GMT – ADP Weekly Employment Change, prior 19.8K
- 20:30 GMT – API Weekly Statistical Bulletin
After the Close:
- Capital One (COF), est. $4.69
- Chubb (CB), est. $6.77
- Interactive Brokers (IBKR), est. $0.64
- Range Resources (RRC), est. $0.68
- Western Alliance Bancorp (WAL), est. $2.36
Wednesday, July 22
Before the Open:
- AT&T (T), est. $0.59
- CME Group (CME), est. $2.91
- GE Vernova (GEV), est. $3.19
- Moody’s (MCO), est. $4.24
- Philip Morris International (PM), est. $2.02
- PulteGroup (PHM), est. $2.36
Economic Releases:
- 14:30 GMT – Crude Oil Inventories, prior -1.7M
After the Close:
- Alphabet (GOOGL), est. $2.90 on $116.9 billion revenue
- Tesla (TSLA), est. $0.54 on $26.4 billion revenue
- IBM (IBM), est. $2.91
- ServiceNow (NOW), est. $0.86
- Texas Instruments (TXN), est. $1.92
- CSX (CSX), est. $0.52
- Kinder Morgan (KMI), est. $0.32
Thursday, July 23
Before the Open:
- American Airlines (AAL), est. $0.03
- Blackstone (BX), est. $1.33
- Comcast (CMCSA), est. $0.96
- Freeport-McMoRan (FCX), est. $0.61
- Honeywell (HON), est. $1.81
- Lockheed Martin (LMT), est. $7.22
- RTX (RTX), est. $1.66
- T-Mobile US (TMUS), est. $2.57
- Union Pacific (UNP), est. $3.25
Economic Releases:
- 12:30 GMT – Unemployment Claims, forecast 211K, prior 208K
- 14:30 GMT – Natural Gas Storage, prior 41B
- Treasury Currency Report – Tentative
After the Close:
- Intel (INTC), est. $0.22 on $14.4 billion revenue
- Newmont (NEM), est. $2.08
- SAP (SAP), est. $2.03
- United Rentals (URI), est. $11.52
- VeriSign (VRSN), est. $2.42
Friday, July 24
Before the Open:
- American Express (AXP), est. $4.41
- Charter Communications (CHTR), est. $10.00
- HCA Healthcare (HCA), est. $7.52
- NextEra Energy (NEE), est. $1.10
- SLB (SLB), est. $0.51
- Verizon Communications (VZ), est. $1.28
Economic Releases:
- 13:45 GMT – Flash Manufacturing PMI, forecast 54.5, prior 53.9
- 13:45 GMT – Flash Services PMI, forecast 51.4, prior 51.2
- 14:00 GMT – New Home Sales, forecast 604K, prior 580K
After the Close:
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecasts- No reports scheduled.
Central Bank Activity
No scheduled Federal Reserve speeches or publications were provided for this week. The next FOMC meeting is July 28-29.
Technical Outlook
Weekly Dow Jones Industrial Average Index
Dow Jones: 52,146.42 (-0.93%), support is 50,998.94, 50,458.41, 49,173.29, 48,201.91, 48,114.27 (52-week SMA). Resistance is 53,289.30.
Weekly Nasdaq Composite Index
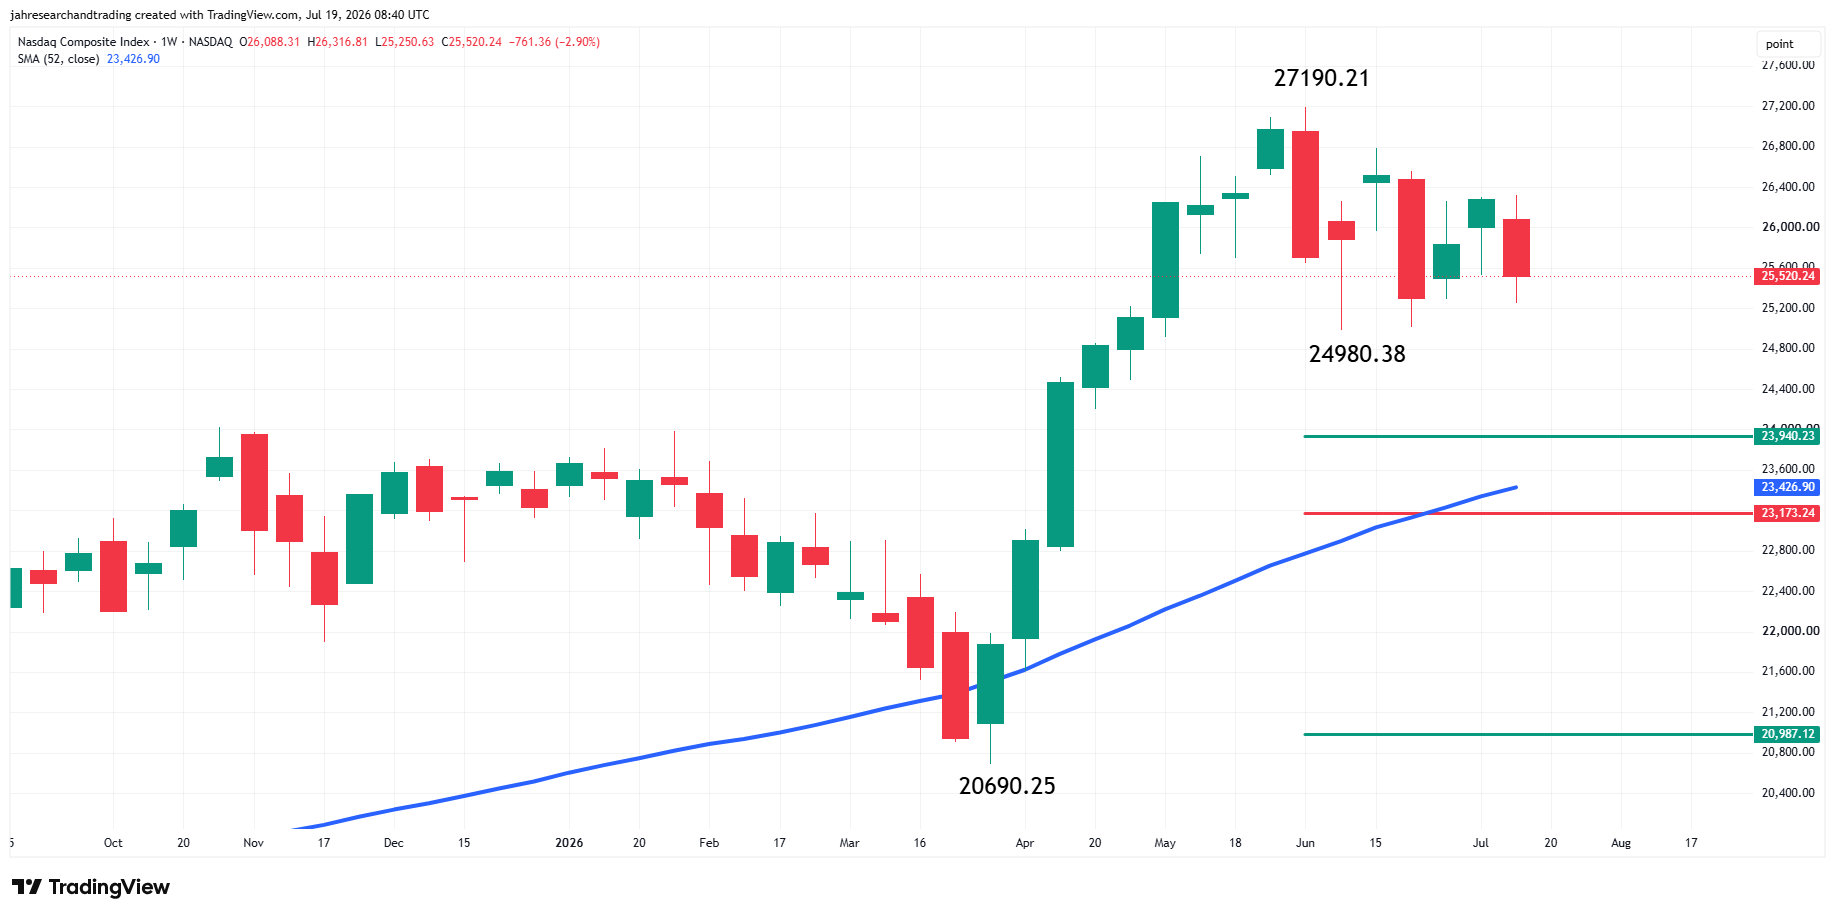
Nasdaq: 25,520.24 (-2.90%), support is 24980.38, 23,940.23, 23,426.90 (52-week SMA), 23,173.24. Resistance is 27,190.21.
Weekly S&P 500 Index
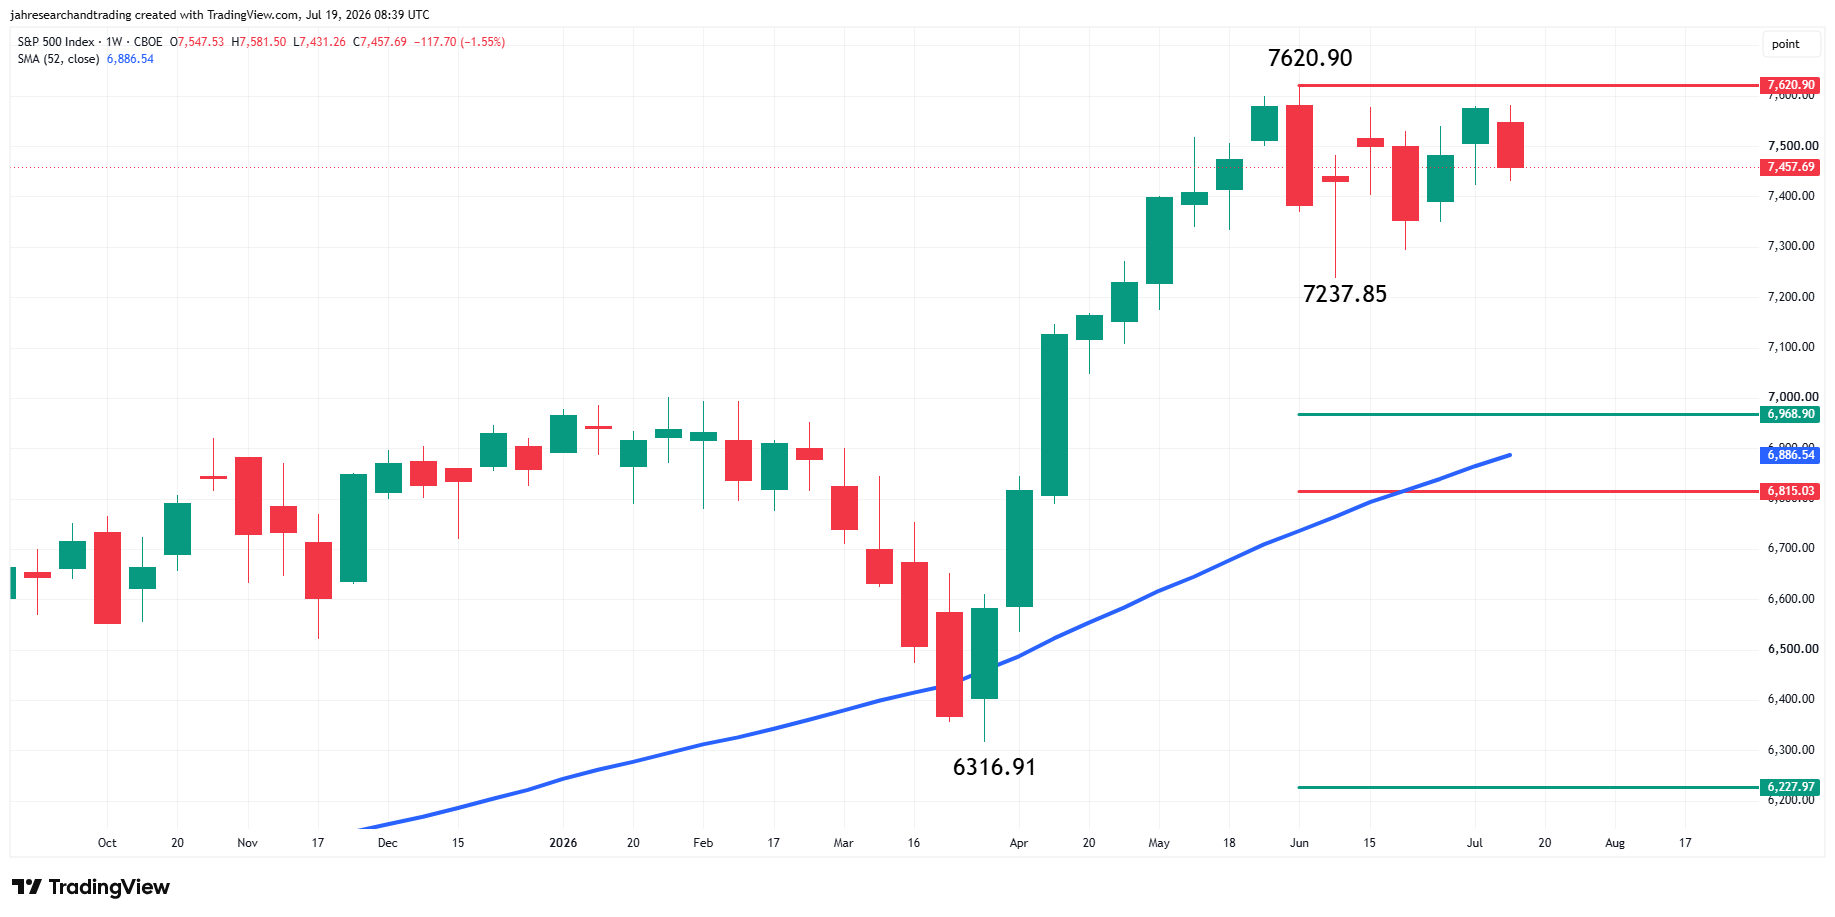
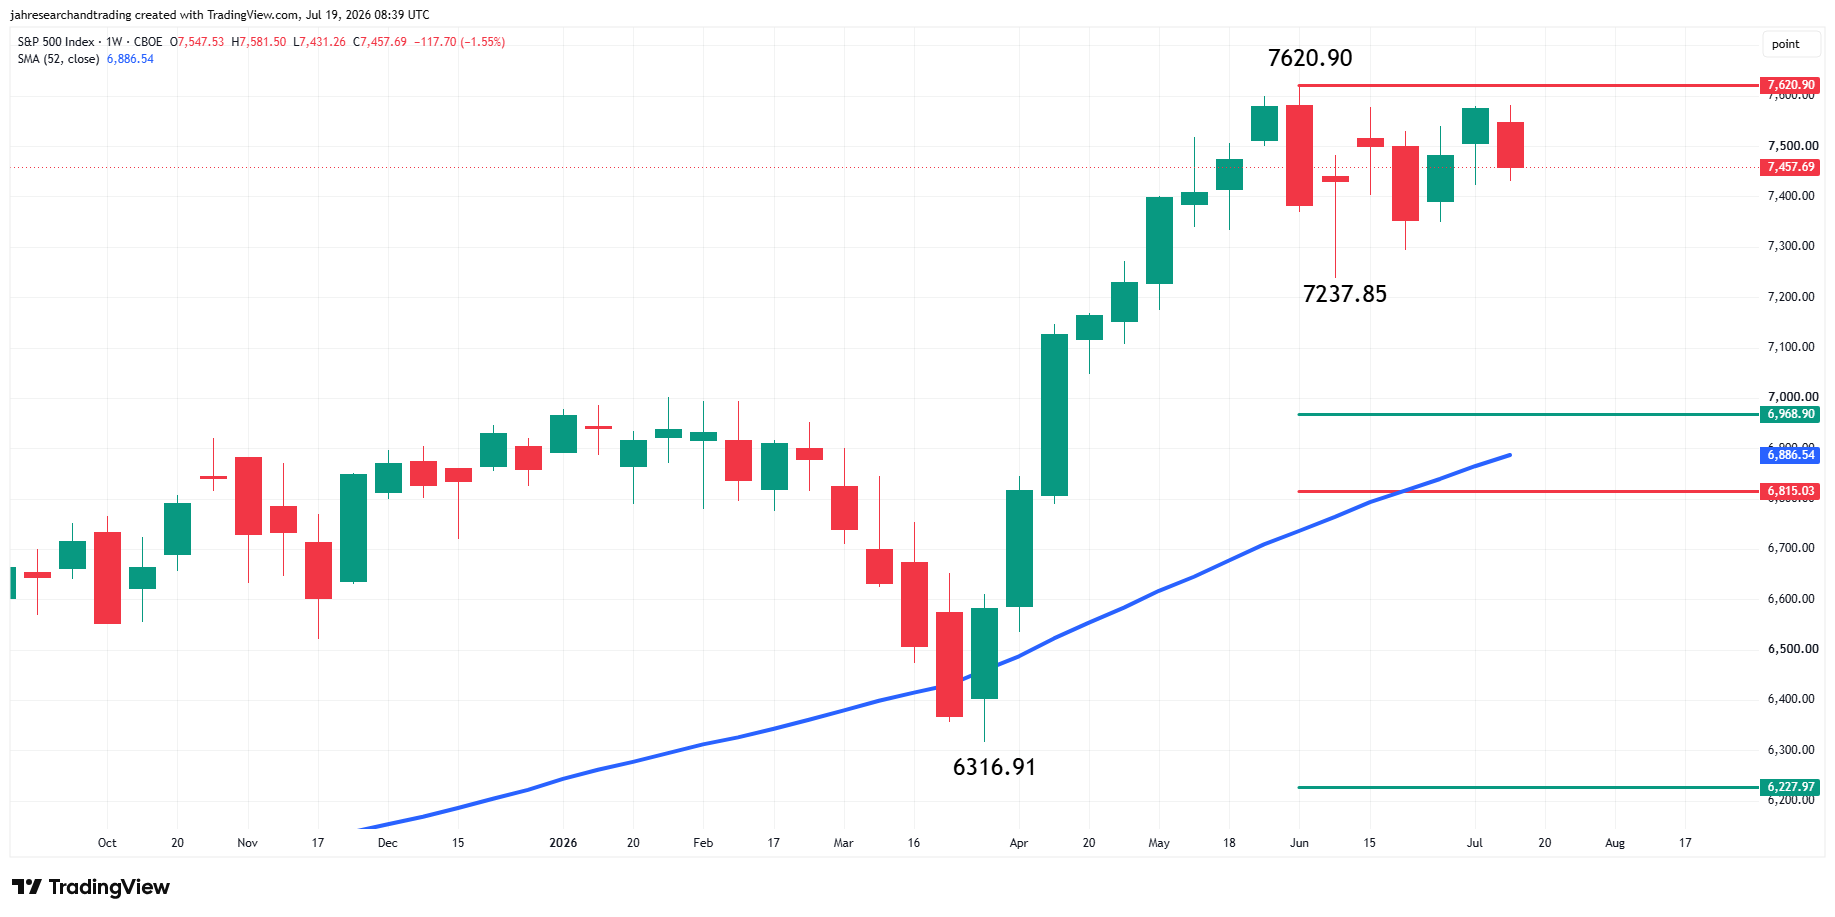
S&P 500: 7,457.69 (-1.55%), support is 7237.85, 6,968.90, 6,886.54 (52-week SMA) and 6,815.03. Resistance is 7,620.90.
All three major indices remain above their rising 52-week moving averages, confirming that the primary uptrend remains intact despite last week’s selling.
Outlook
The earnings calendar will set the tone this week. Alphabet, Tesla, ServiceNow, Texas Instruments and Intel will provide the clearest read on AI spending, cloud demand, memory and server demand, and whether corporate results support the technology sector’s elevated earnings expectations.
Thursday’s jobless claims and Friday’s PMI and new-home-sales reports are the main economic releases. The week’s market forecast rests on whether technology earnings and guidance stabilize the recent selling in semiconductors and other AI-related shares.
More Information in our Economic Calendar.