Broad Market Retreat Driven by Tech Slide and Data Uncertainty
The U.S. equity market moved lower on Tuesday, with major indexes extending the weakness that began late last week. A broad pullback in technology stocks and caution ahead of delayed economic releases kept risk appetite suppressed through mid-day trade.
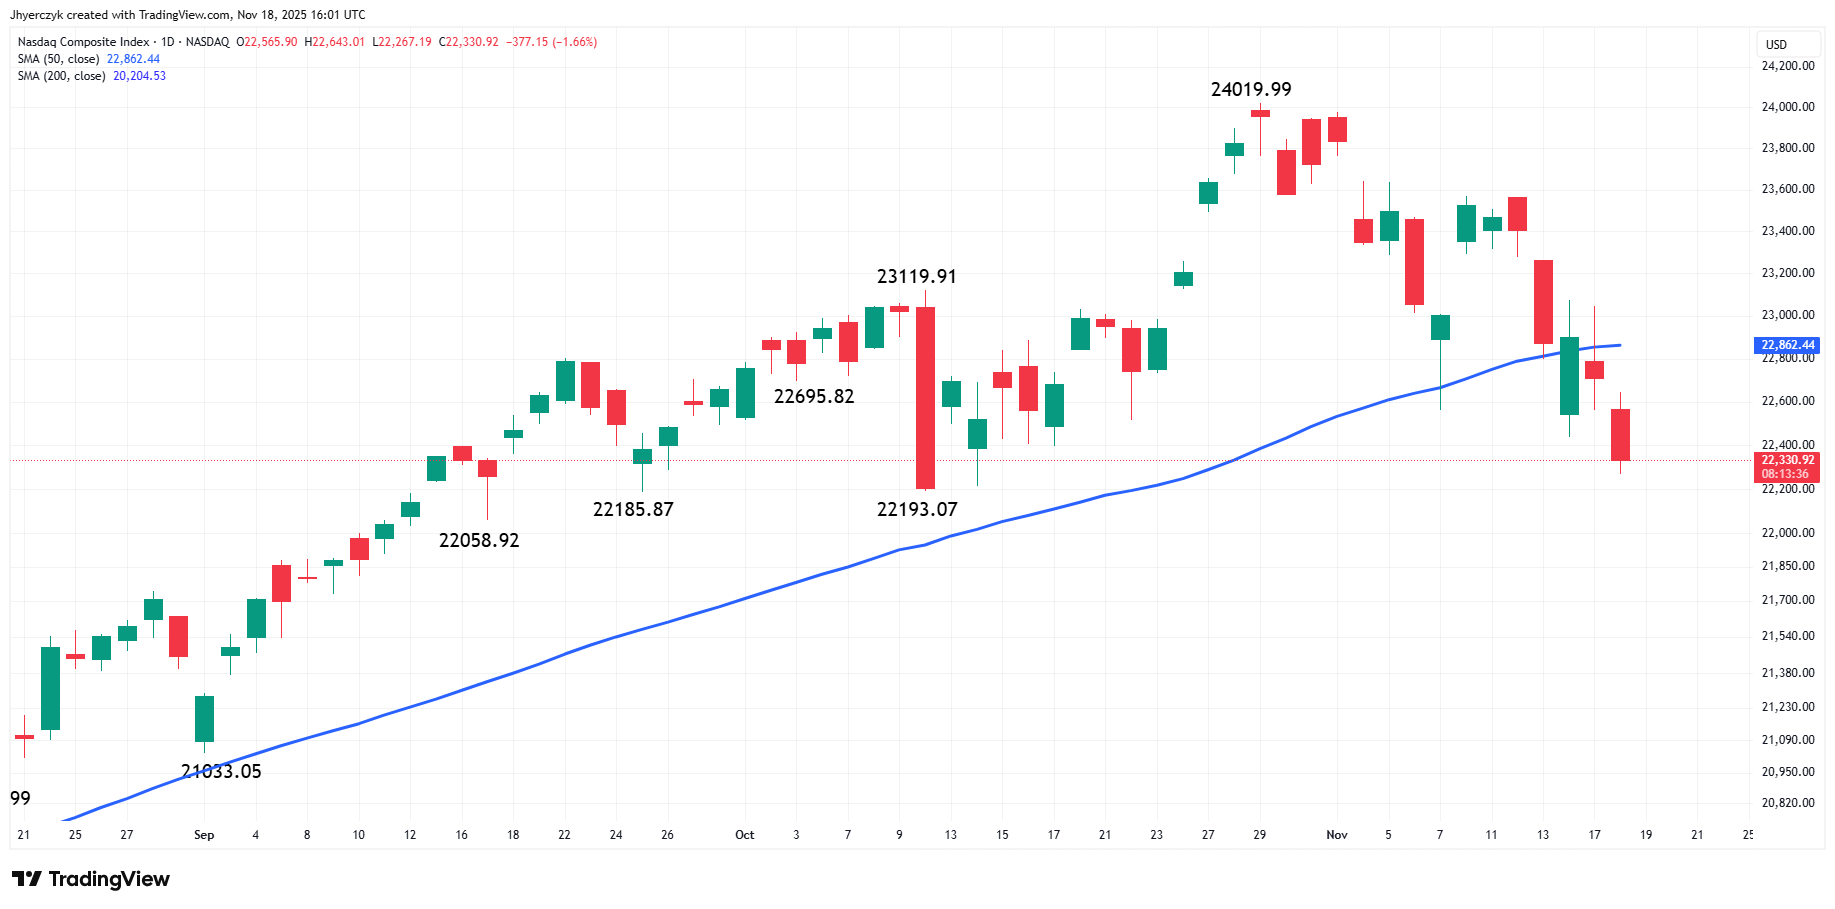
The S&P 500, Dow Jones Industrial Average, and Nasdaq Composite were all firmly in negative territory as investors reassessed stretched valuations in high-growth areas of the market.
Selling pressure remained concentrated in mega-cap technology and AI-linked names, which continued to correct following months of outsized gains. Traders also stayed defensive as they awaited a wave of postponed government reports that could reset expectations for Federal Reserve policy into year-end.
Is Tech Weakness Driving Broader Risk Aversion?
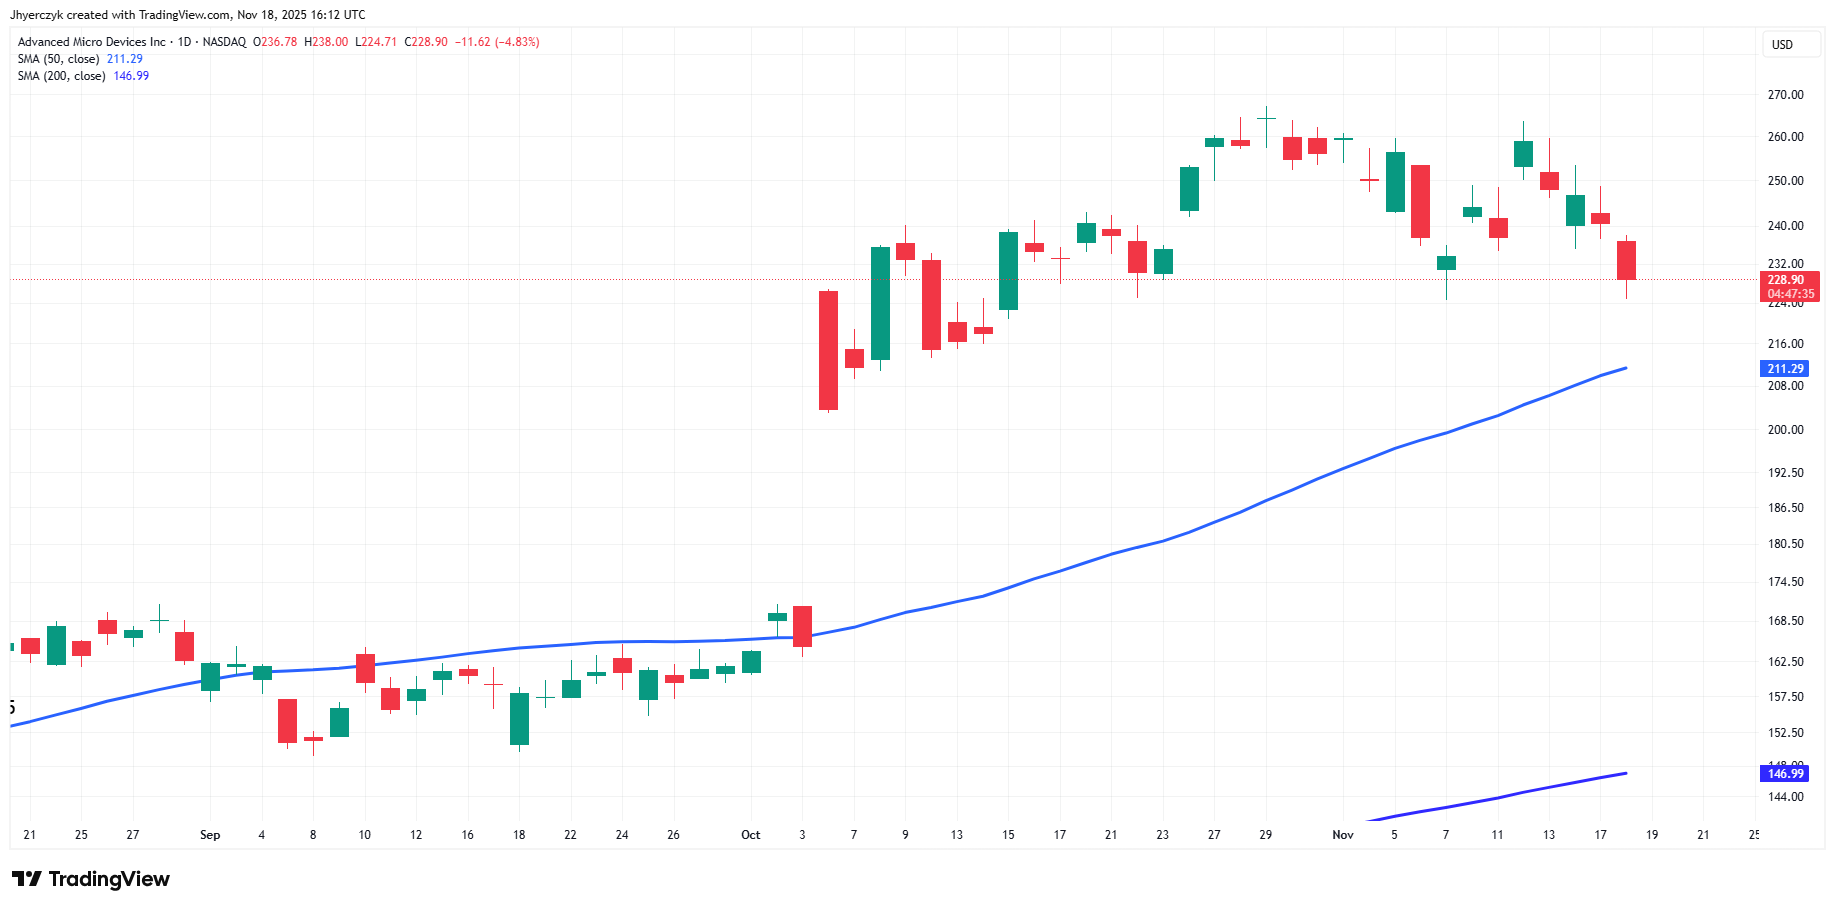
Technology was the worst-performing sector, down 1.95%. Nasdaq-linked heavyweights saw extended losses, with AMD, Micron, Microsoft, and Western Digital all among the session’s steepest decliners.
Concerns over extended valuations in the AI group continued to weigh on sentiment after global survey data flagged an “AI bubble” as a top risk. Recent analyst downgrades for enterprise hardware names reinforced the selling tone, and crypto-related equities slumped alongside Bitcoin.
How Did Other Sectors Perform Mid-Day?
Sector performance showed defensive resilience. Health Care gained 0.07%, and Consumer Staples rose 0.35%, while Industrials, Financials, and Energy posted moderate losses.
Consumer Discretionary fell sharply by 2.21% as Home Depot declined more than 4% following weaker earnings and a reduced full-year outlook.
NASDAQ 100 Price Forecast
Every new NASDAQ 100 analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all NASDAQ 100 forecastsReal Estate, Utilities, and Materials also traded softer but held closer to unchanged levels.
Which Stocks Stood Out?
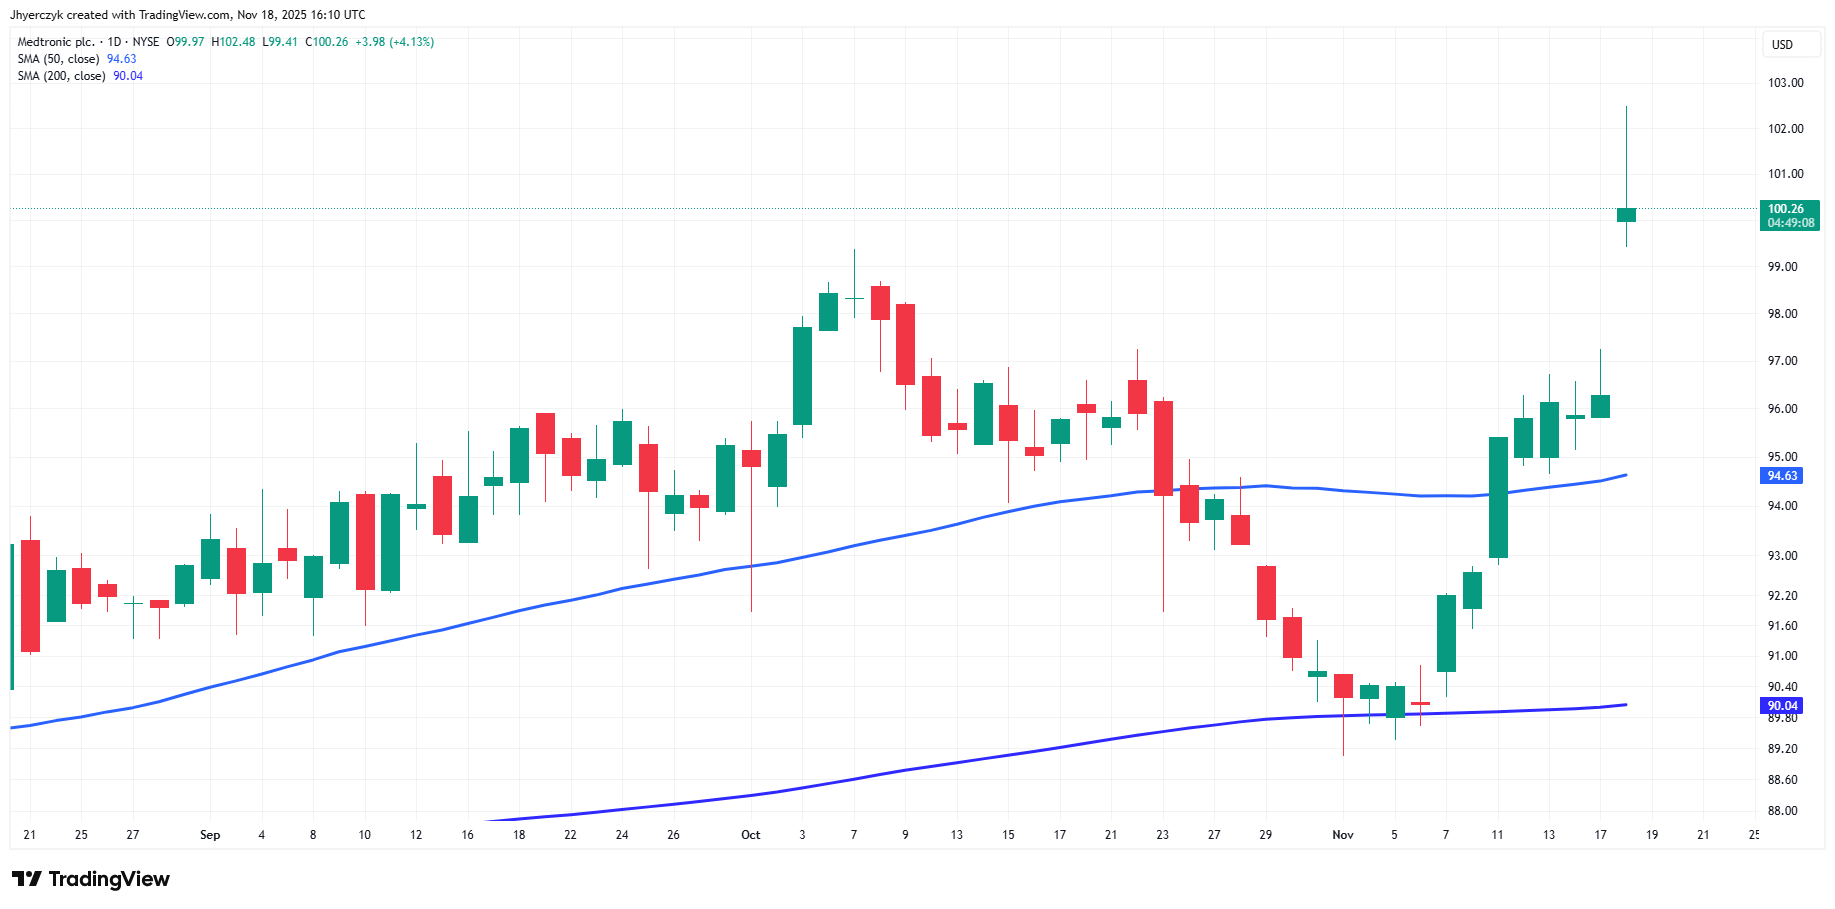
Gainers were concentrated in select defensive and value names. Medtronic, Merck, Freeport-McMoRan, Philip Morris, and Hershey all moved higher.
Amer Sports jumped 8% after topping earnings expectations, while James Hardie Industries rallied on stronger-than-expected quarterly revenue and improved guidance.
Axalta Coating Systems gained over 6% after announcing an all-stock merger with AkzoNobel valued at $25 billion.
Barrick Gold also firmed after reports that Elliott Management had accumulated a significant stake.
On the downside, top decliners were mostly tech-focused, including Western Digital, AMD, Micron, and Monolithic Power Systems.
Amazon and UnitedHealth also traded sharply lower. Helmerich & Payne dropped more than 7% following a surprise quarterly loss despite stronger-than-expected revenue.
Blue Owl Capital extended a three-day decline as investors monitored restrictions on fund redemptions.
What Should Traders Expect Next?
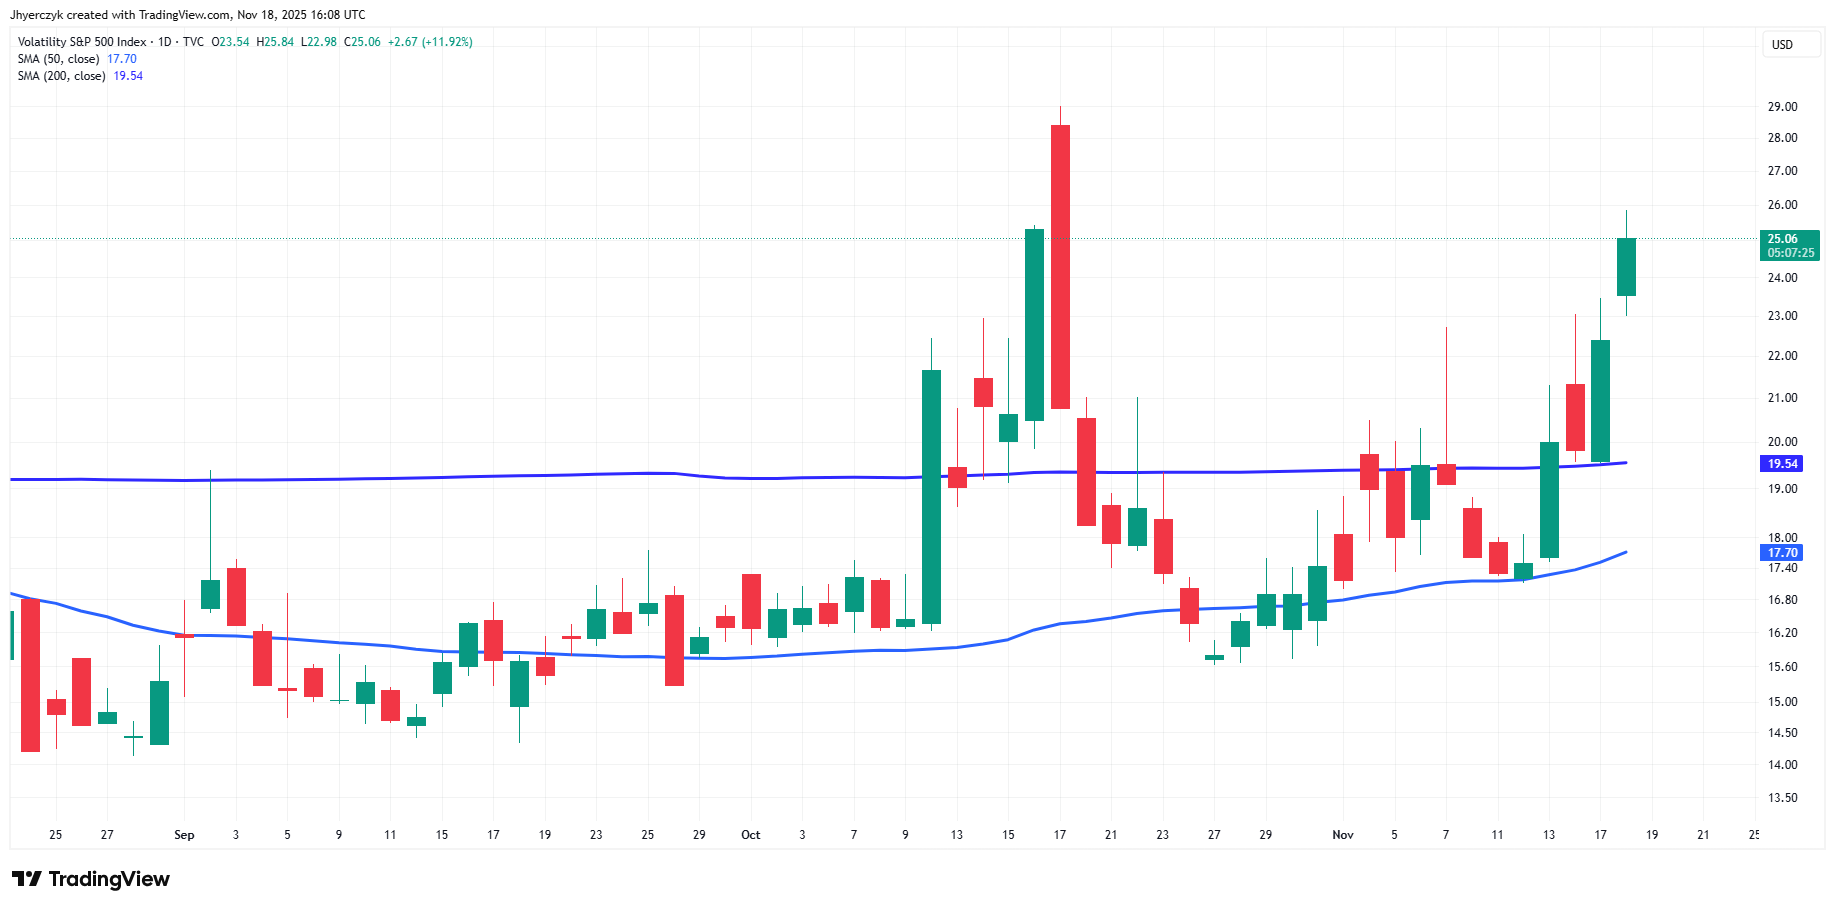
With crucial government data releases compressed into a short window following the prolonged shutdown, volatility is likely to stay elevated.
Traders will closely monitor incoming employment figures, factory orders, and durable goods data for clues on economic momentum and potential implications for December rate expectations.
Given the sector rotation toward defensives and persistent profit-taking in high-growth names, the short-term outlook leans bearish until the delayed reports provide clearer direction.
More Information in our Economic Calendar.