Delayed CPI Adds Weight to September’s Inflation Print
The September U.S. Consumer Price Index (CPI), released Friday following a delay due to the government shutdown, comes at a critical time for markets.
With few recent economic data points, the CPI has outsized importance as investors assess inflation pressure and Federal Reserve policy ahead of the October 29 meeting. Consensus estimates project a 0.4% month-over-month rise in headline CPI and a 3.1% annual increase.
Core CPI, excluding food and energy, is expected to climb 0.3% monthly and 3.1% year-over-year.
Tariffs Fuel Price Pressure, but Housing Offers Relief
Rising tariffs remain a persistent inflation driver in 2025, especially in consumer categories such as apparel, furniture, and sporting goods. This has kept core goods inflation elevated despite falling energy prices.
However, economists anticipate some offset from moderating shelter costs, driven by easing mortgage rates in recent months. This shift in housing input is seen as a partial cushion against tariff-driven price pressure, though overall inflation remains well above the Fed’s 2% target.
Fed Expected to Cut Rates Despite Above-Target Inflation
Futures markets are pricing in a 98.9% probability of a 25-basis-point rate cut at the Fed’s October meeting, with a 96.1% chance of another reduction in December. This signals the Fed’s growing emphasis on labor market weakness over inflation concerns.
BlackRock strategists point to employment softness as a more dominant variable now, suggesting that potential disinflation from labor market stress could outweigh goods-driven inflation.
Gold Price Forecast
Every new Gold analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Gold forecastsDollar and Treasury Yields React to CPI Trajectory
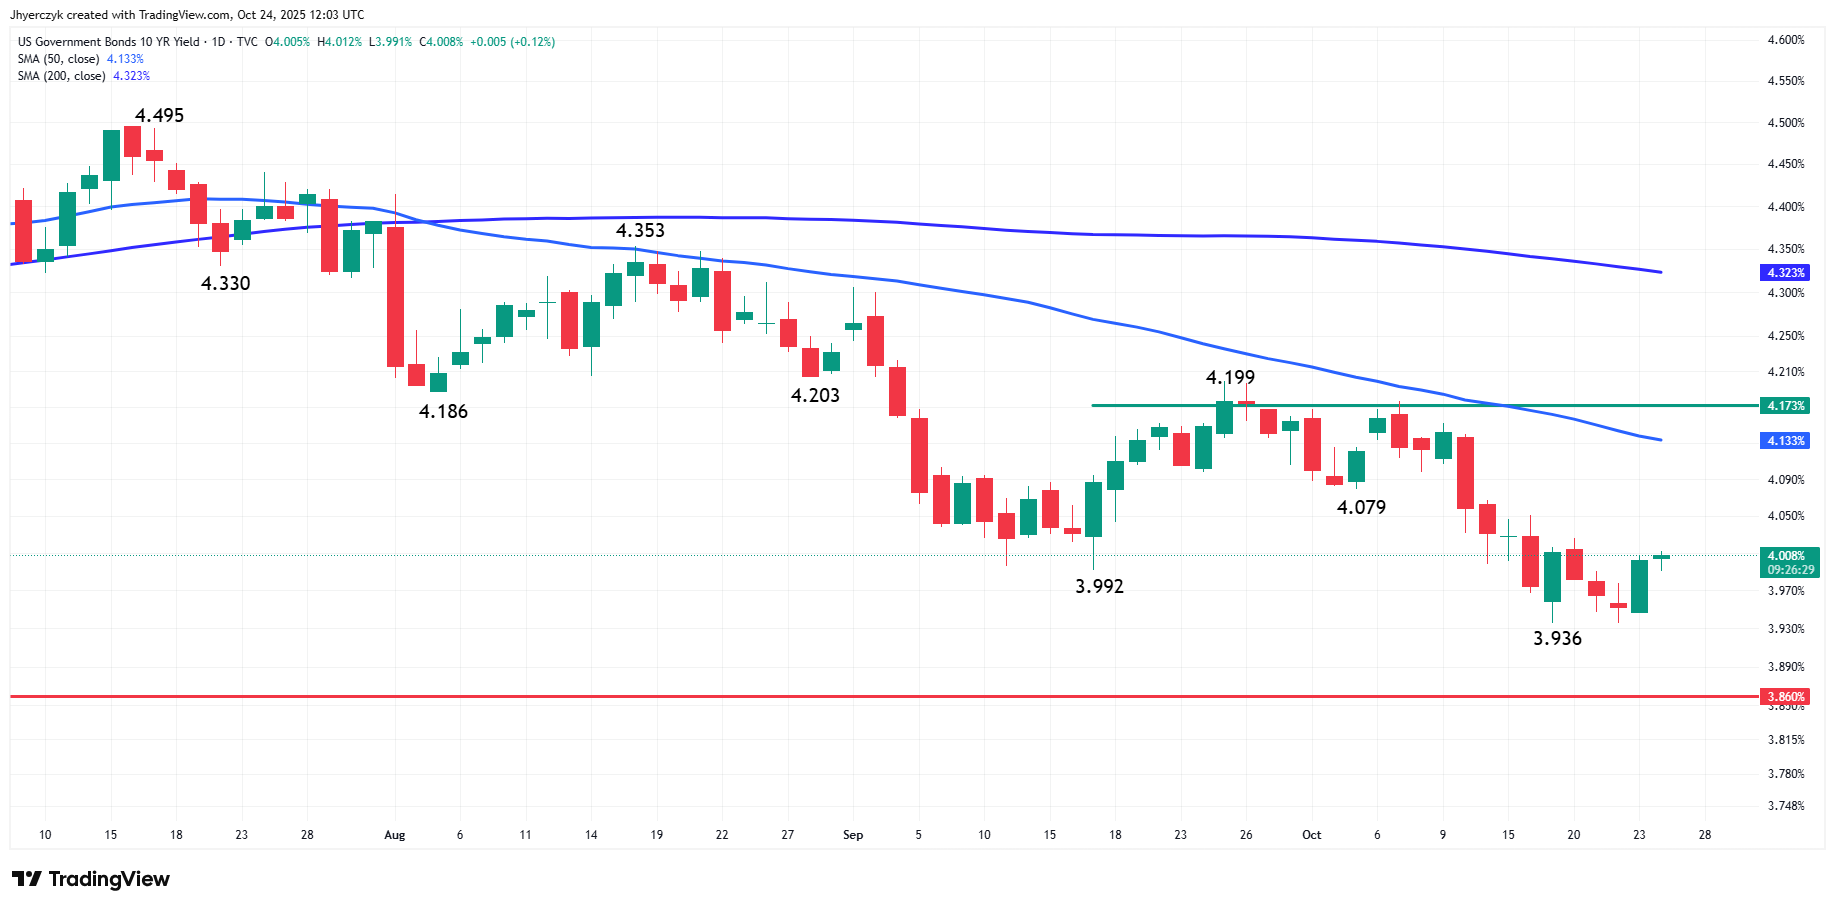
Treasury yields remain elevated, reflecting investor caution over stubborn inflation. Analysts at Charles Schwab expect continued steepening of the yield curve, favoring intermediate durations as inflation and growth expectations anchor long-end rates.
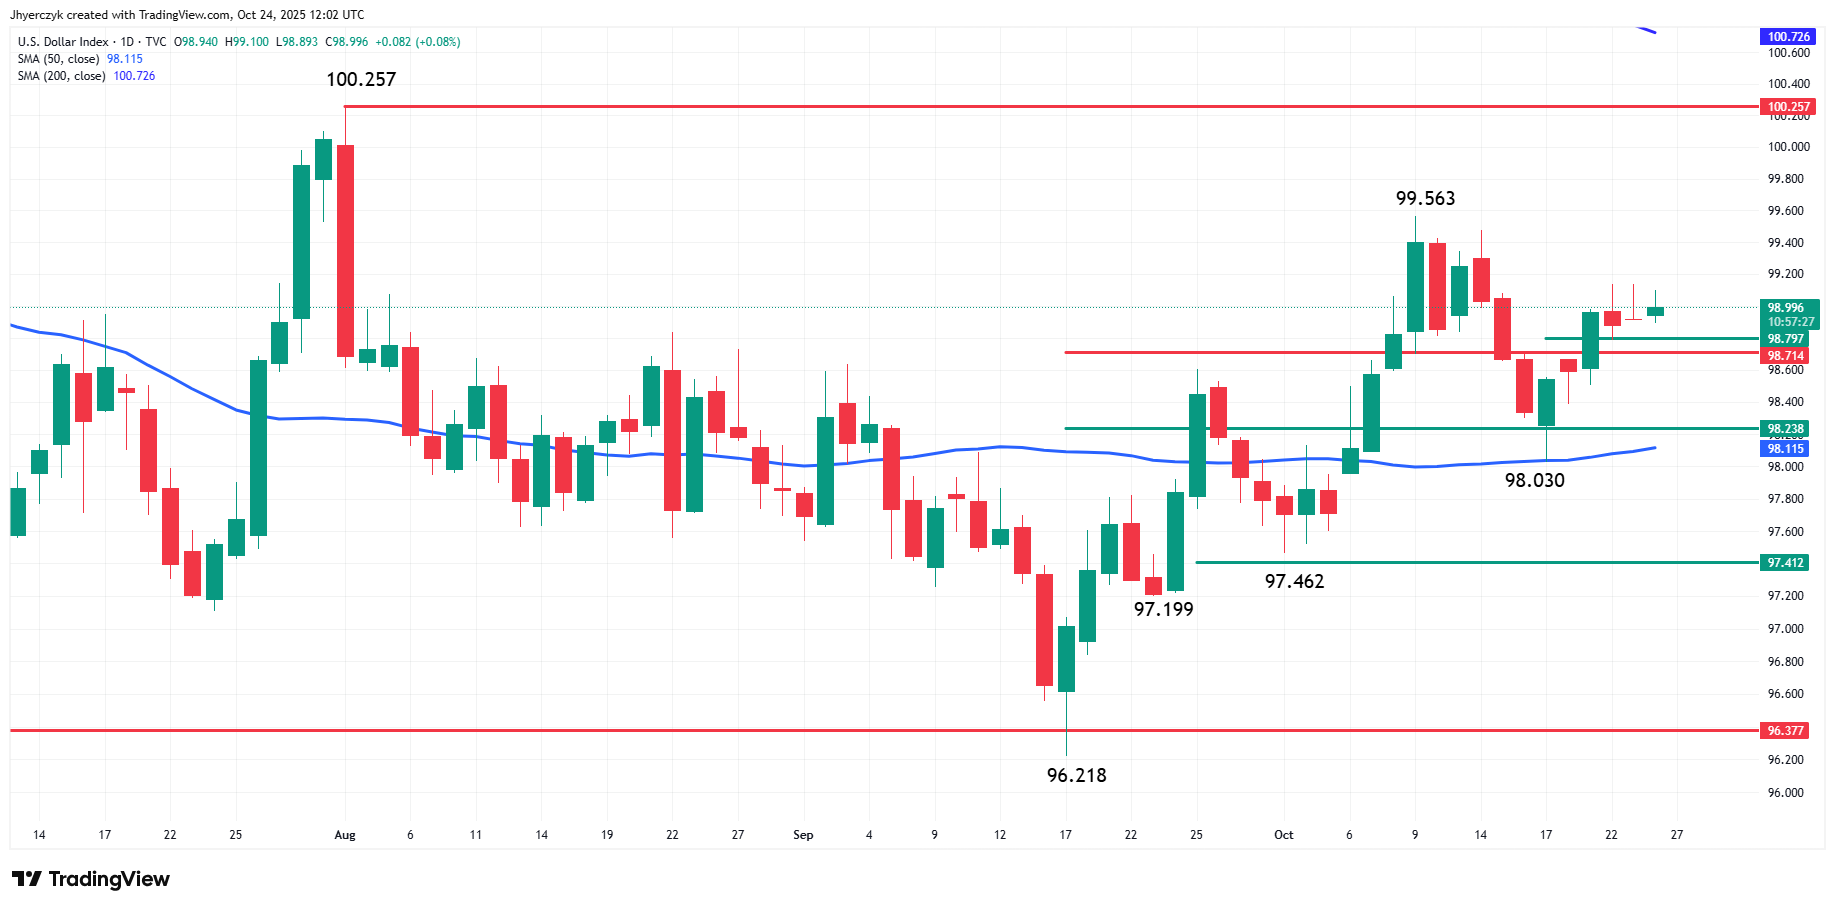
The U.S. dollar, down sharply in 2025, could firm if CPI overshoots and dampens rate-cut bets. However, a softer reading may accelerate dollar weakness, further supporting commodities and global risk assets.
Gold and Silver Face Mixed Signals from CPI and Fed Expectations

Gold remains caught between opposing forces. Expectations of U.S. rate cuts support the metal, lowering its opportunity cost, but high Treasury yields and a firm dollar continue to cap gains. A softer CPI could reinforce gold’s upside, while a hotter print may push yields and the dollar higher, pressuring bullion.
Silver, with its industrial exposure, remains more sensitive to economic growth trends, but would likely benefit from broader support for metals if monetary easing continues.
Stocks and Bonds Show Resilience on Rate Cut Confidence
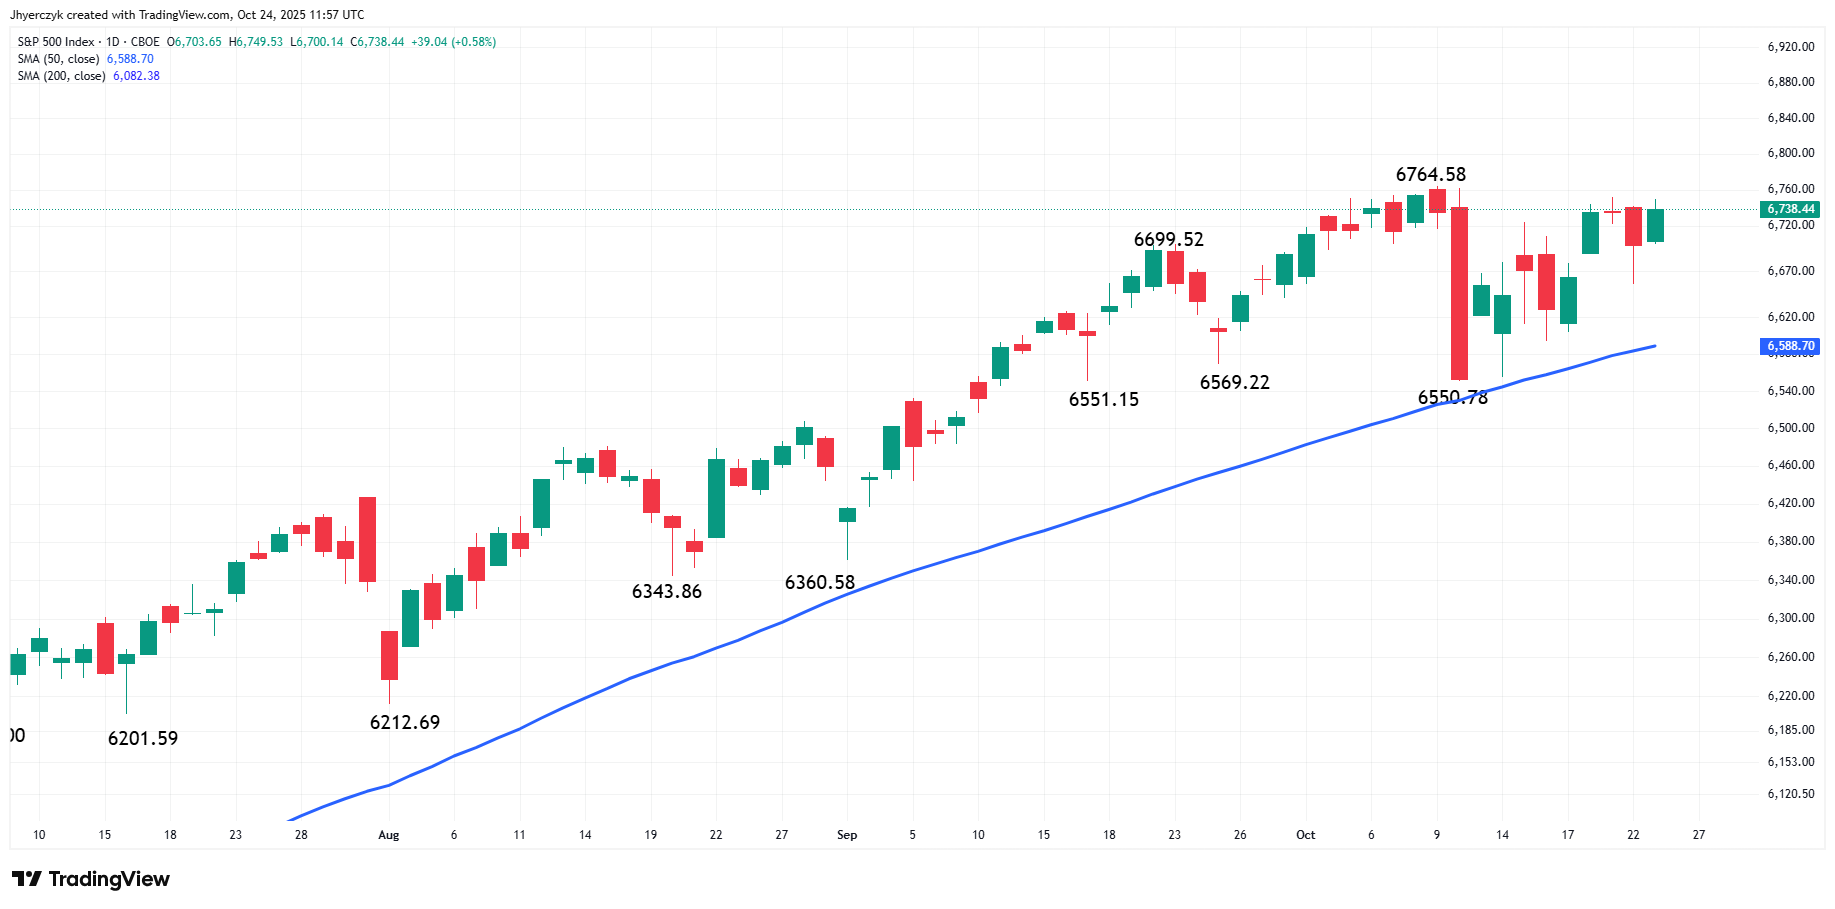
Equity markets are increasingly focused on Fed policy over near-term inflation prints. Despite high CPI projections, JPMorgan sees a 65% chance the S&P 500 will rise post-release, with historical data supporting bullish momentum around CPI events. Bond markets are also adjusting, with Charles Schwab favoring intermediate-term duration as yield curve steepening continues.
Short-Term Outlook: Bullish Bias Holds with Fed in Control
With markets pricing in two more rate cuts by year-end and inflation concerns well-telegraphed, the short-term outlook remains bullish. Gold may recover if CPI underperforms, and equities look set to extend gains unless data dramatically overshoots expectations. Traders should monitor core services inflation and Treasury market reaction for cues.
More Information in our Economic Calendar.