The 10-year yield touched 5.04 percent on eTuesday, its highest since 2007; Brent settled at $108.75 and WTI at $105.83 after Saudi Aramco canceled September cargoes to Europe with the East-West pipeline still shut, and stocks fell for the sixth time in seven sessions. Gold settled on Tuesday at $4,333.50, at the neckline, and has bounced about $50 overnight to trade near $4,383.
Silver is leading the bounce. That is the fourth time in eight sessions, and the other three ended the way they began.

The Bounce Before the Decision
Yesterday, I wrote: “That is the neckline, to the dollar. Not below it. At it.”
Gold held the line into the close and lifted off it overnight, which is what a market does the day before an event it has priced at 94 percent: it squares.
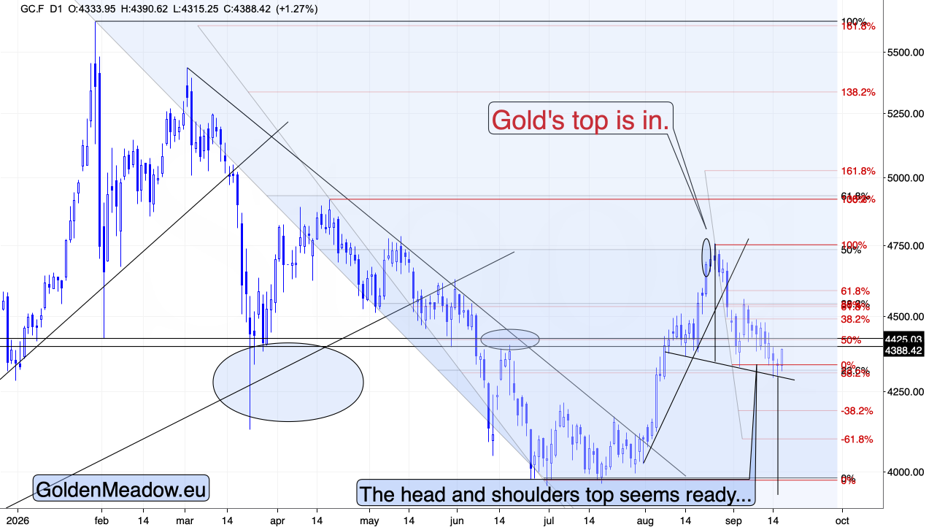
The profile of this morning’s move is the one I described in yesterday’s scenarios table for a “one and done” outcome, except that it has arrived before the outcome.
Silver is up more than gold, the miners are up a little, the dollar is flat rather than falling, and oil is easing from a four-month high rather than breaking. None of those is a reversal signature. Together they are a short-covering session ahead of a decision, and on September 3 and September 11 the same profile produced one higher close and no follow-through.
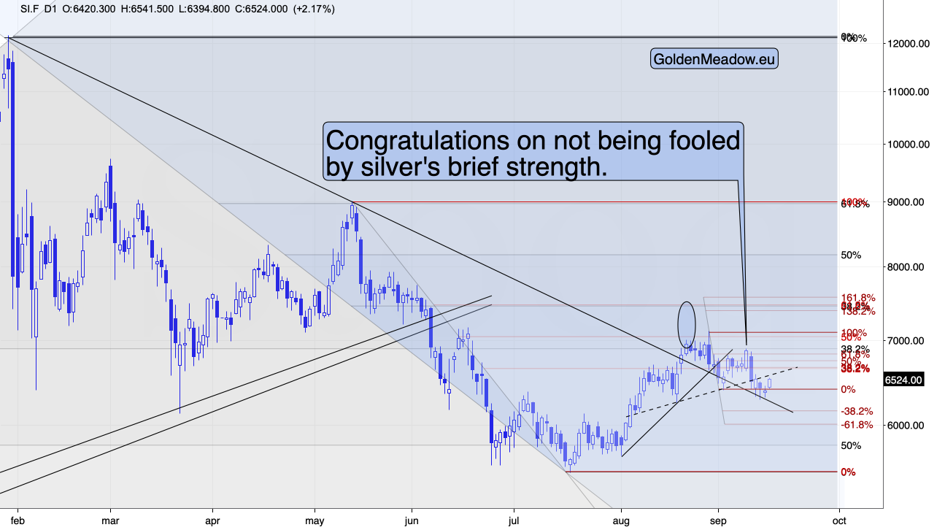
In silver’s case, today’s upswing is just a verification of the breakdown below the neck level of its own head-and-shoulders pattern. At the same time, it bounced off the declining, medium-term support line. Something will give in soon. The USD Index favors a bigger move to the downside.
The interest rate decision days tend to produce a lot of uncertainty, which tends to temporarily boost precious metals prices. After the decision, the uncertainty will decrease regardless of the decision itself.
Gold Price Forecast
Every new Gold analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Gold forecastsHow the Market Got to 94
Two weeks ago, the September hike was a 68 percent proposition. Here is the path from there to here, with the 10-year and gold’s settlement on each day.
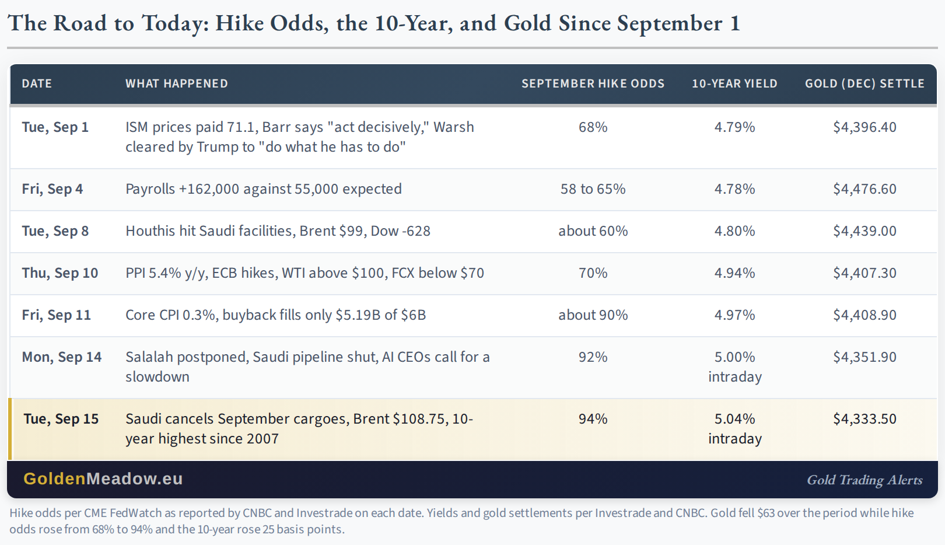
Read the last two columns together. Every step up in the odds came with a step up in yields, and every step up in yields took something out of gold, until the metal that settled at $4,476.60 on the Friday of the payrolls was settling at $4,333.50 on the eve of the decision. Yesterday I wrote that the rate channel “is no longer a forecast. It is the tape.” The table is the tape.
The one day the odds fell, September 4 to September 8, was the yen-driven dollar pullback that gold failed to rally on, and the dollar reversed from the late-May low as I expected it to. The one-day gold rose meaningfully in the period, September 3, was Waller’s coin flip, and it lasted one session.
What to Watch at 2:00 and 2:30
The 25 basis points are priced. The reaction will come from three other things: the dot plot, the wording on oil, and the two-year yield. On the dots, one detail sharpens the reading: the June median for the end of 2026 was 3.8 percent, which implied a single hike, and today’s move to 3.75 to 4.00 arrives at that median. So a September median of 4.1 percent or higher says more is coming, and a median at 3.9 or 4.0 says this was the hike the committee had planned. Chair Warsh does not submit a dot of his own, so the plot has 18 rather than 19.
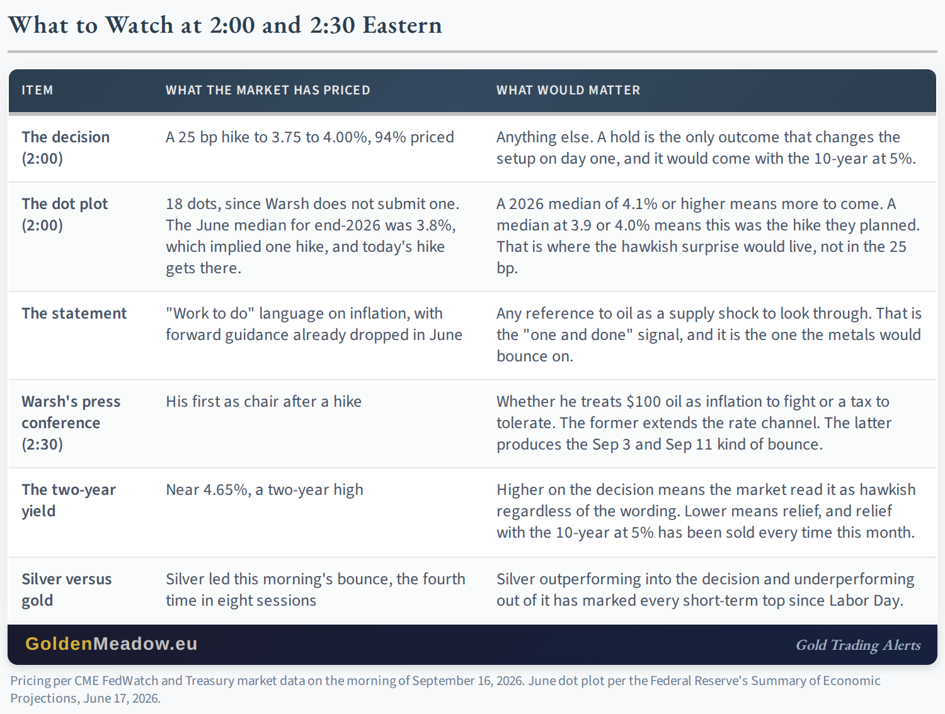
The items I would weigh most are the last two rows of the checklist rather than the first. The Fed’s decision is a headline. The market’s reaction to the headline is what the charts record, and the reaction that matters is whether gold closes above or below the neckline tonight and whether silver, which led on the way up this morning, leads on the way down after 2:30. If the two-year yield rises on the decision, the market read it as hawkish whatever the statement said.
If it falls and the metals bounce, that bounce arrives with the 10-year near 5 percent and Brent above $105, and every bounce in that configuration this month has been sold within a session or two. I will be monitoring the reaction in real time and will write to you if anything requires action.
Oil: Cargoes Canceled
The oil side did not wait for the Fed either. Saudi Aramco informed European customers on Tuesday that some September deliveries were canceled, loadings at Yanbu were suspended, and Argus quotes a source saying every Saudi shipment scheduled for the final ten days of September is at risk, with Yanbu holding about five days of crude. Commodity vessel traffic through Hormuz fell to four transits on Monday. Repair estimates for the East-West line still run from days to eight weeks, and Bernstein put $150 on the table as a scenario.
Brent settled at a four-month high on Tuesday and is easing about 1 percent this morning, which is the decision-day pattern in every market: a step back before the event, not a change of direction. Rystad’s line captures where the market is: the “relatively contained price reaction suggests the market still expects Saudi inventories to cushion exports in the near term,” and the cushion is five days deep.
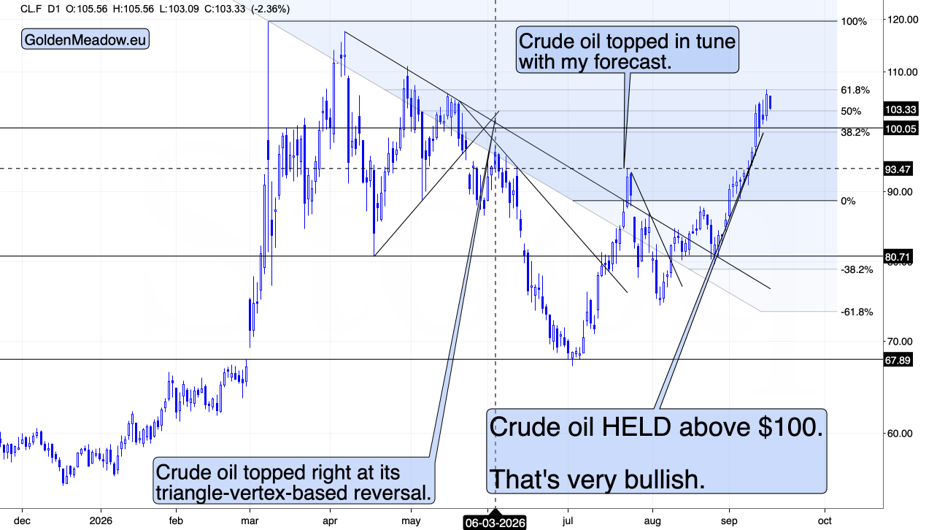
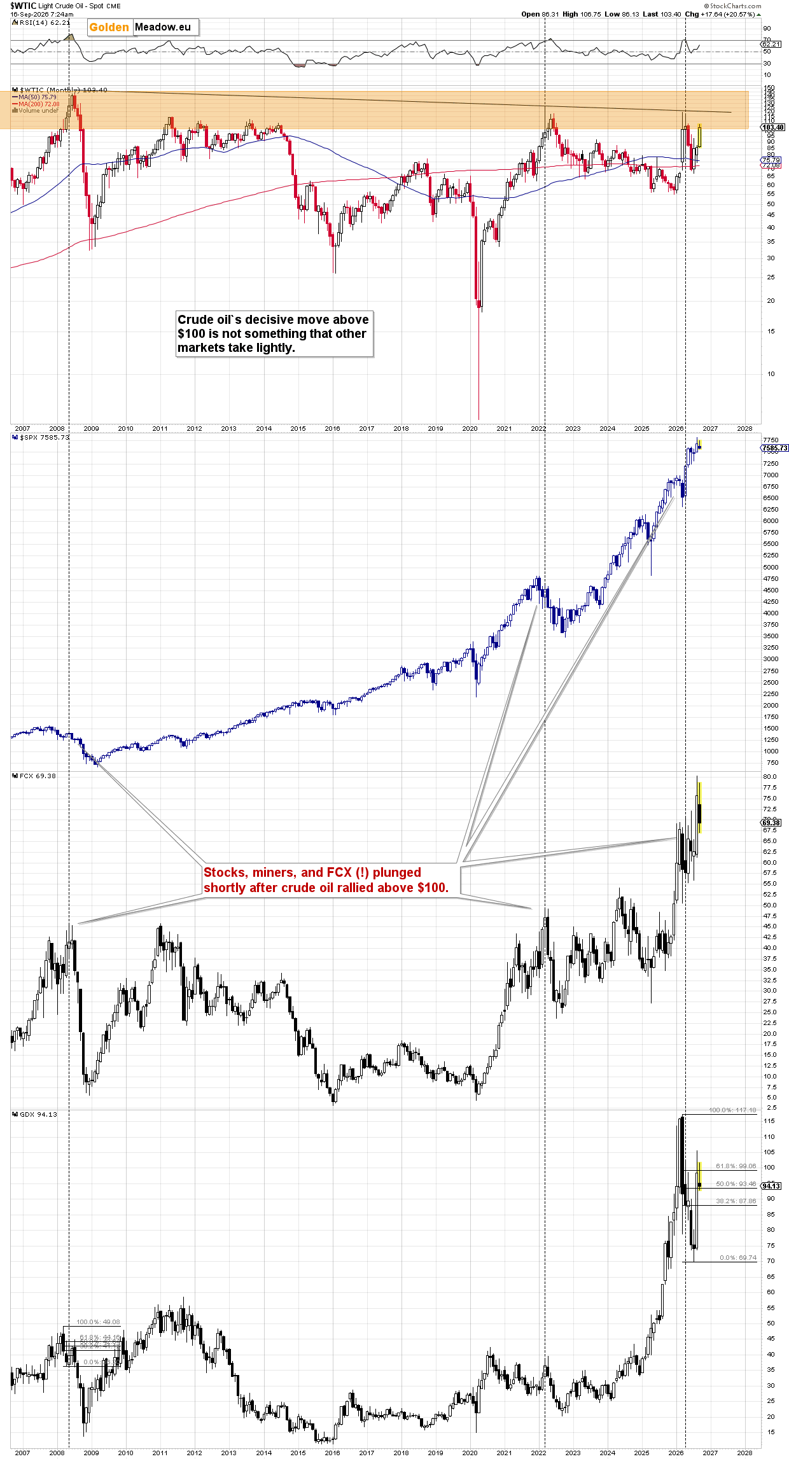
Crude oil declined a bit today, but this changes nothing. What matters is the fact that yesterday’s closing price was one of the highest daily closes of 2026.
If this persists – and that’s the likely outcome – it will put huge pressure on stocks and non-energy commodities.
Stocks
The S&P 500 fell 0.45 percent on Tuesday to 7,585.73, the Nasdaq 0.78 percent, and the Dow 328 points, with the 10-year at 5 percent into the close. Six declines in seven sessions, with the one exception being Friday’s bounce on the Salalah report that was canceled two days later. The AI names that fell on Monday bounced on Tuesday, AMD by 2 percent and Qualcomm by 4, which is the sector doing what gold is doing this morning: squaring before the decision. Futures are up about 0.2 percent.
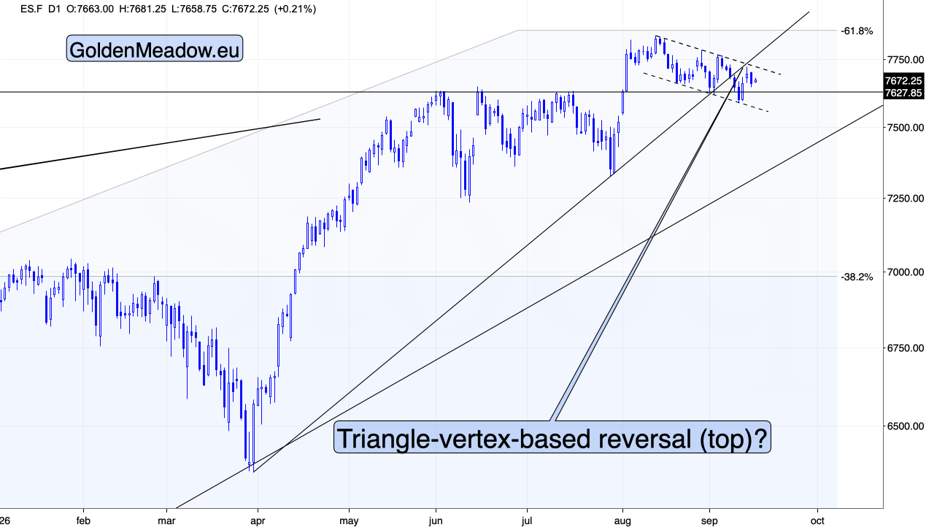
From the short-term point of view, the S&P 500 futures verified the breakdown below their rising support line.
From the long-term point of view, however…
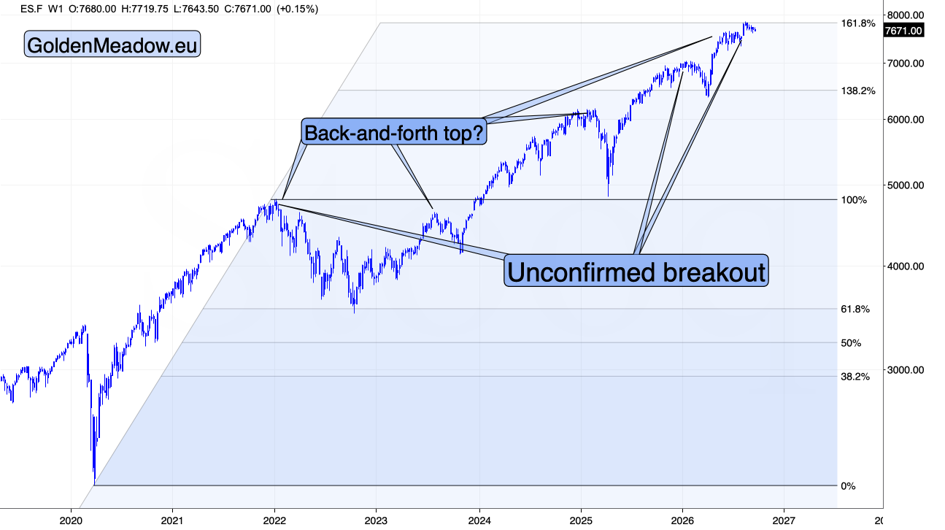
They reached the 1.618 Fibonacci extension based on the entire 2020 – 2022 rally. It makes perfect sense for the top to be in from the technical point of view.
The current prices of crude oil, the outlook for it, as well as recent comments from the AI CEOs all justify the above from the fundamental point of view.
Where This Leaves Us
My outlook and positions are unchanged, and the profit-take levels remain in place.
Gold bounced off the neckline into the decision with silver leading, which is the profile that has marked every short-term top since Labor Day, and the odds, the bond yields, and the settlements in the table above describe a market that has already done the Fed’s work. What happens at 2 p.m. is the announcement. What happens at the close is the analysis.
Yesterday, I wrote that the market is waiting for the Fed to agree. Today at 2 p.m., it finds out.
Thank you for reading today’s analysis – I appreciate that you took the time to dig deeper and that you read the entire piece. If you’d like to get more (and extra details not available to 99% investors), I invite you to stay updated with our free analyses – sign up for our free gold newsletter now.
Thank you.
Sincerely,
Przemysław K. Radomski, CFA