AI Infrastructure Is Taking the Money While Energy Gives It Back
The stock market is higher Friday but the buying is concentrated. Akamai is up 8.27% after its multiyear Anthropic deal.
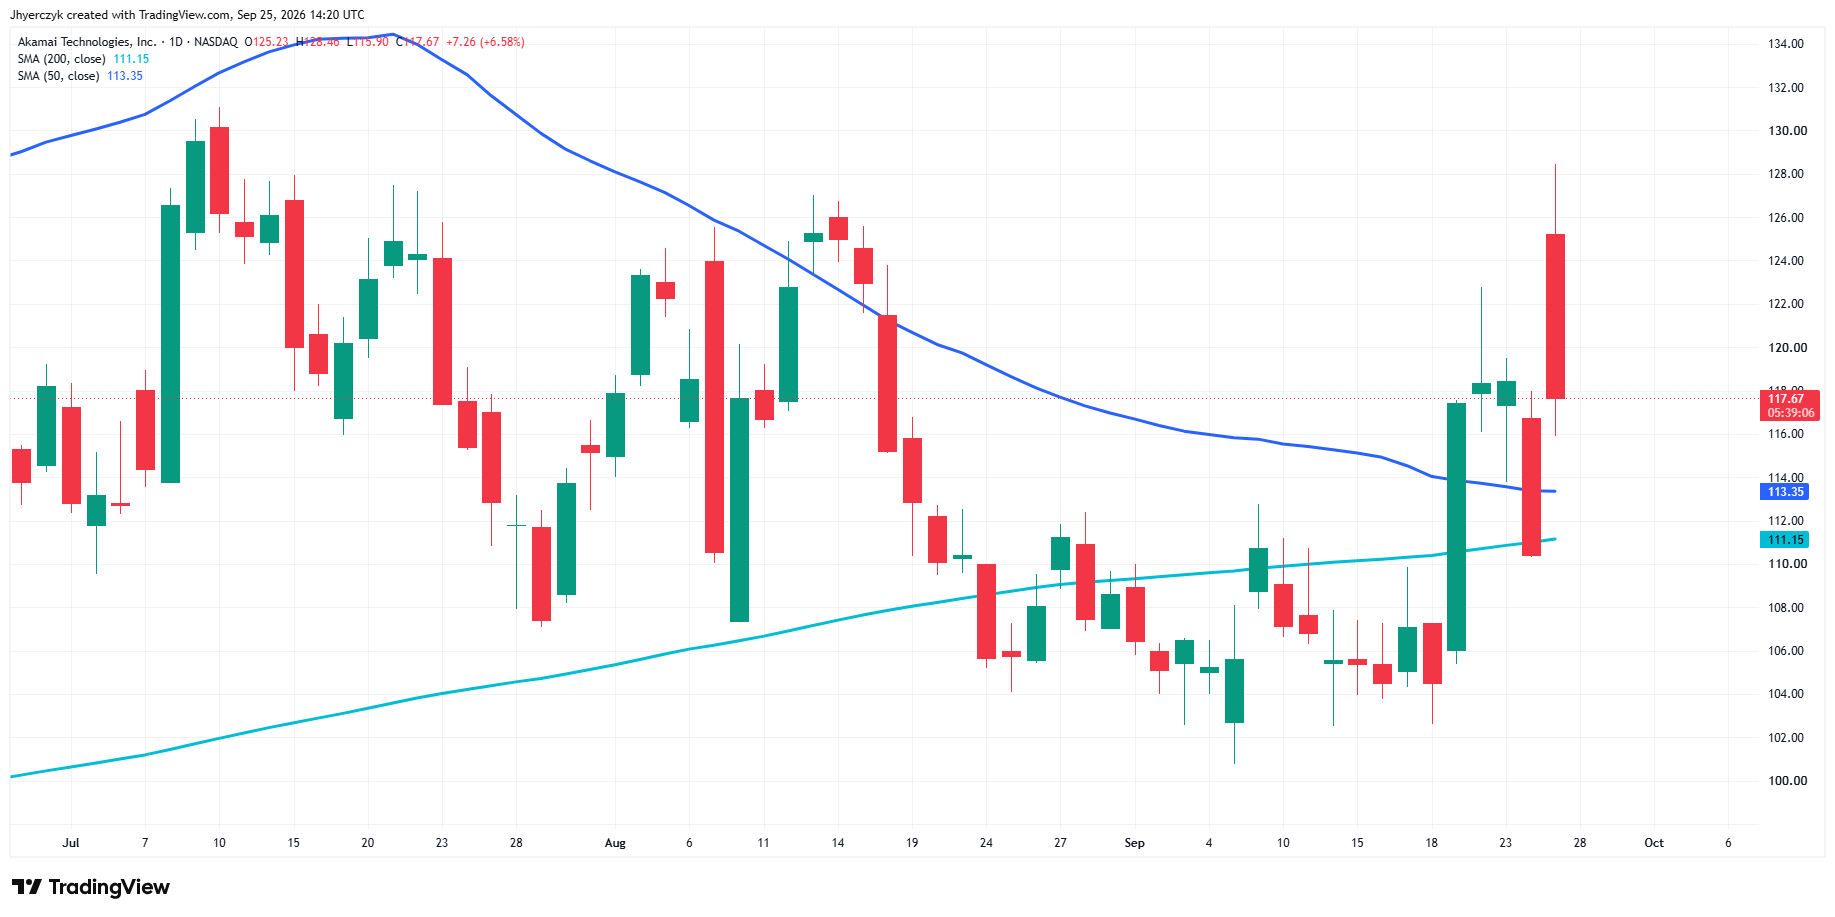
Dell is up 4.01%. Flex is up 3.95%. Synopsys, Microsoft, ON Semiconductor, Qualcomm, and Super Micro Computer are all up more than 3%. On the other side, Valero is down 2.82%, Devon Energy is down 2.46%, and Marathon Petroleum is down 2.40%. The money is rotating out of energy and into AI infrastructure on the same session.
At 13:48 GMT, the S&P 500 Index is trading 7,721.15, up 17.02 or 0.22%. The Dow Jones Industrial Average is trading 51,528.01, up 178.03 or 0.35%. The Nasdaq Composite Index is trading 27,018.78, up 79.41 or 0.30%.

Daily Nasdaq Composite (IXIC) Technical Analysis
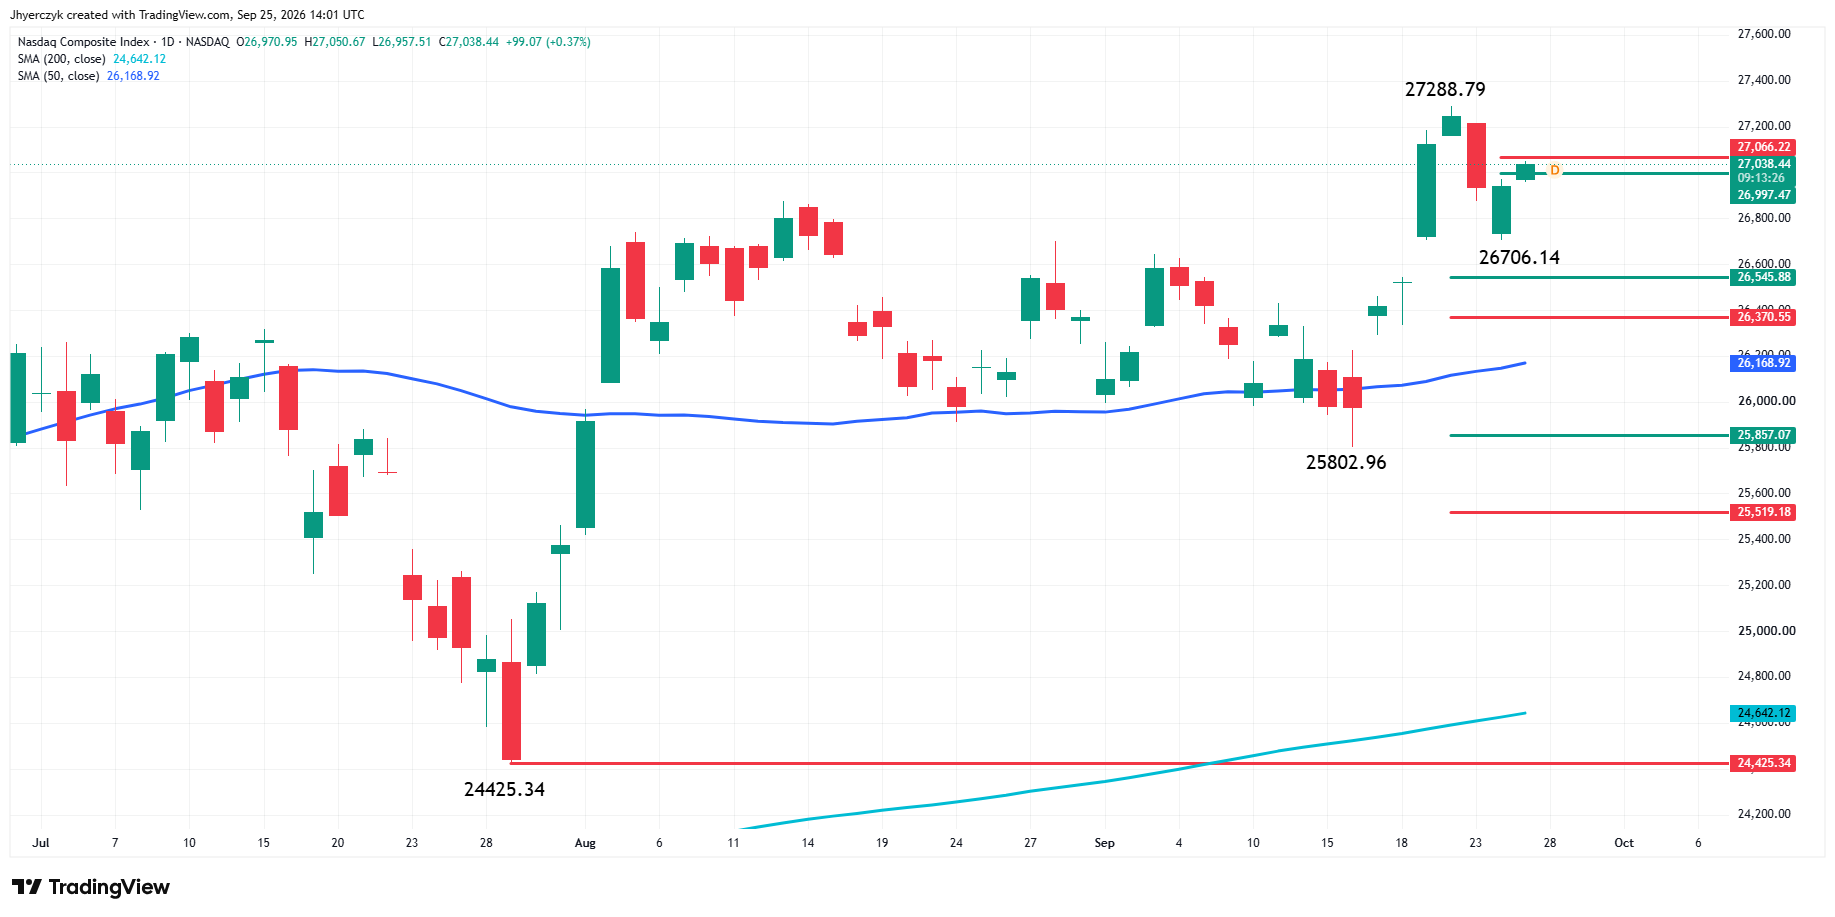
The Nasdaq Composite is testing the short-term retracement zone at 26,997.47 to 27,066.22 after Thursday’s break. Friday’s high at 27,050.67 stopped inside the zone, so buyers have not taken it out yet.
A sustained move over 27,066.22 would signal the presence of buyers and put the 27,288.79 main top back in play. A trade through that level would reaffirm the uptrend.
Failure to hold the lower end of the zone at 26,997.47 would put the recent bottom at 26,706.14 back on the chart. Below that, the next downside target is the 26,545.88 to 26,370.55 retracement zone. The 50-day moving average at 26,168.92 sits under it.
Daily S&P 500 (SPX) Technical Analysis
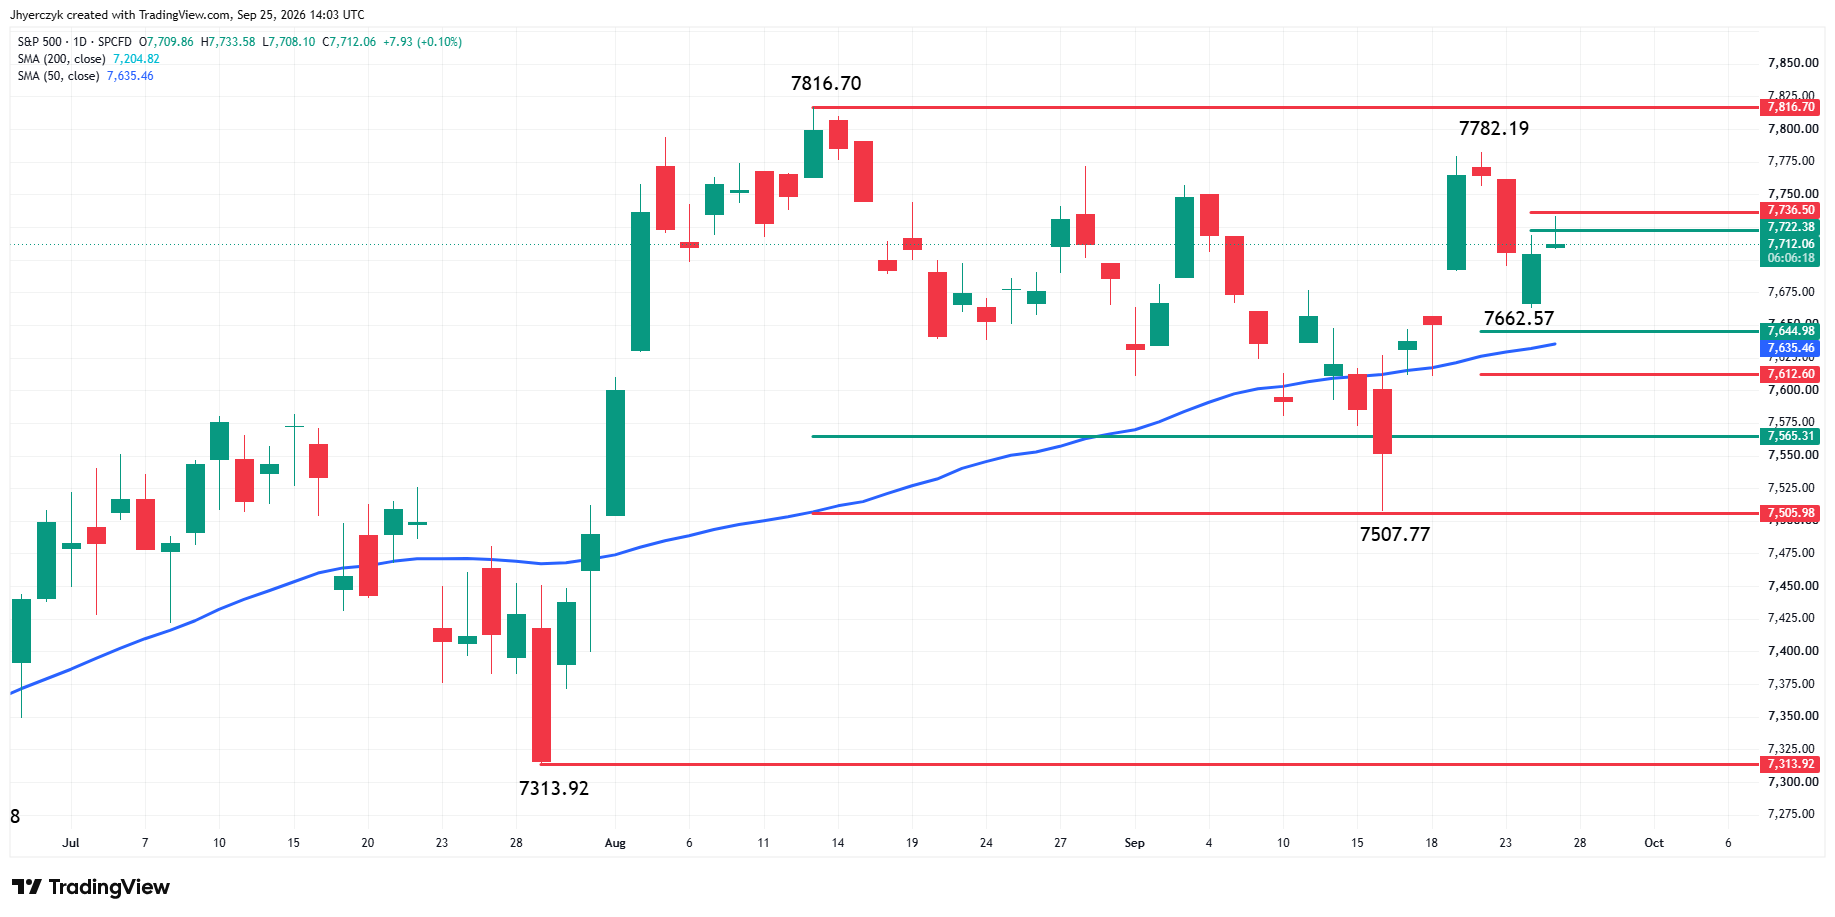
The S&P 500 bounced from Thursday’s low at 7,662.57 and reached the short-term retracement zone at 7,722.38 to 7,736.50. Friday’s high at 7,733.58 stopped inside the zone and the index is trading back below it.
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecastsA sustained move over 7,736.50 would signal buyers are taking control of the recovery. That could generate enough upside momentum to challenge the 7,782.19 minor top, followed by the 7,816.70 main top.
Failure to recover and hold 7,722.38 keeps the focus on the 7,662.57 low. A break through that level would put the 7,644.98 to 7,612.60 support zone back in play, with the 50-day moving average at 7,635.46 sitting inside it.
The Iran Headline Is Doing the Work for Technology
November WTI crude oil futures are near $93 after Iran offered to reopen the Strait of Hormuz and restart nuclear talks if the United States accepts its conditions. November Brent crude oil futures are near $105. The market is taking supply-risk premium out on the possibility of an agreement.
Crude coming down is enough to bring sellers into refiners and energy producers. It is also enough to give the AI names a better bid. Mosaic, LyondellBasell, and Dow are lower with the commodity and energy-cost trade.
The physical story has not changed. Hormuz transits are down to nine, far below normal. Houthi missiles and drones hit Saudi targets Friday. Iran’s offer is conditional and the June framework it refers to already failed once. Crude is trading hope. The energy stocks are paying for it. The market still has to see normal tanker flows and lower insurance costs before it can call the Strait open.
The AI Bid Is Specific, Not Broad
Meta is down 2.68% even after its recent run tied to the Muse AI agent. Palo Alto Networks is down 3.19%. Coinbase is down 2.31%. The buyers are not chasing every large technology name Friday morning. They are taking offers in the companies directly tied to AI infrastructure spending.
Akamai has a direct Anthropic catalyst. Dell, Flex, and Super Micro are trading the equipment side of the buildout. Synopsys is trading the design side. ON Semiconductor and Qualcomm are carrying the chip bid. That is money moving into specific parts of the AI supply chain, not a broad mega-cap rally.
The Dow is headed for a fourth straight losing week. The Nasdaq Composite Index is up 1.6% for the week. The S&P 500 Index is up 0.7%. The concentration tells the story.
The Bond Market Has Not Given Ground
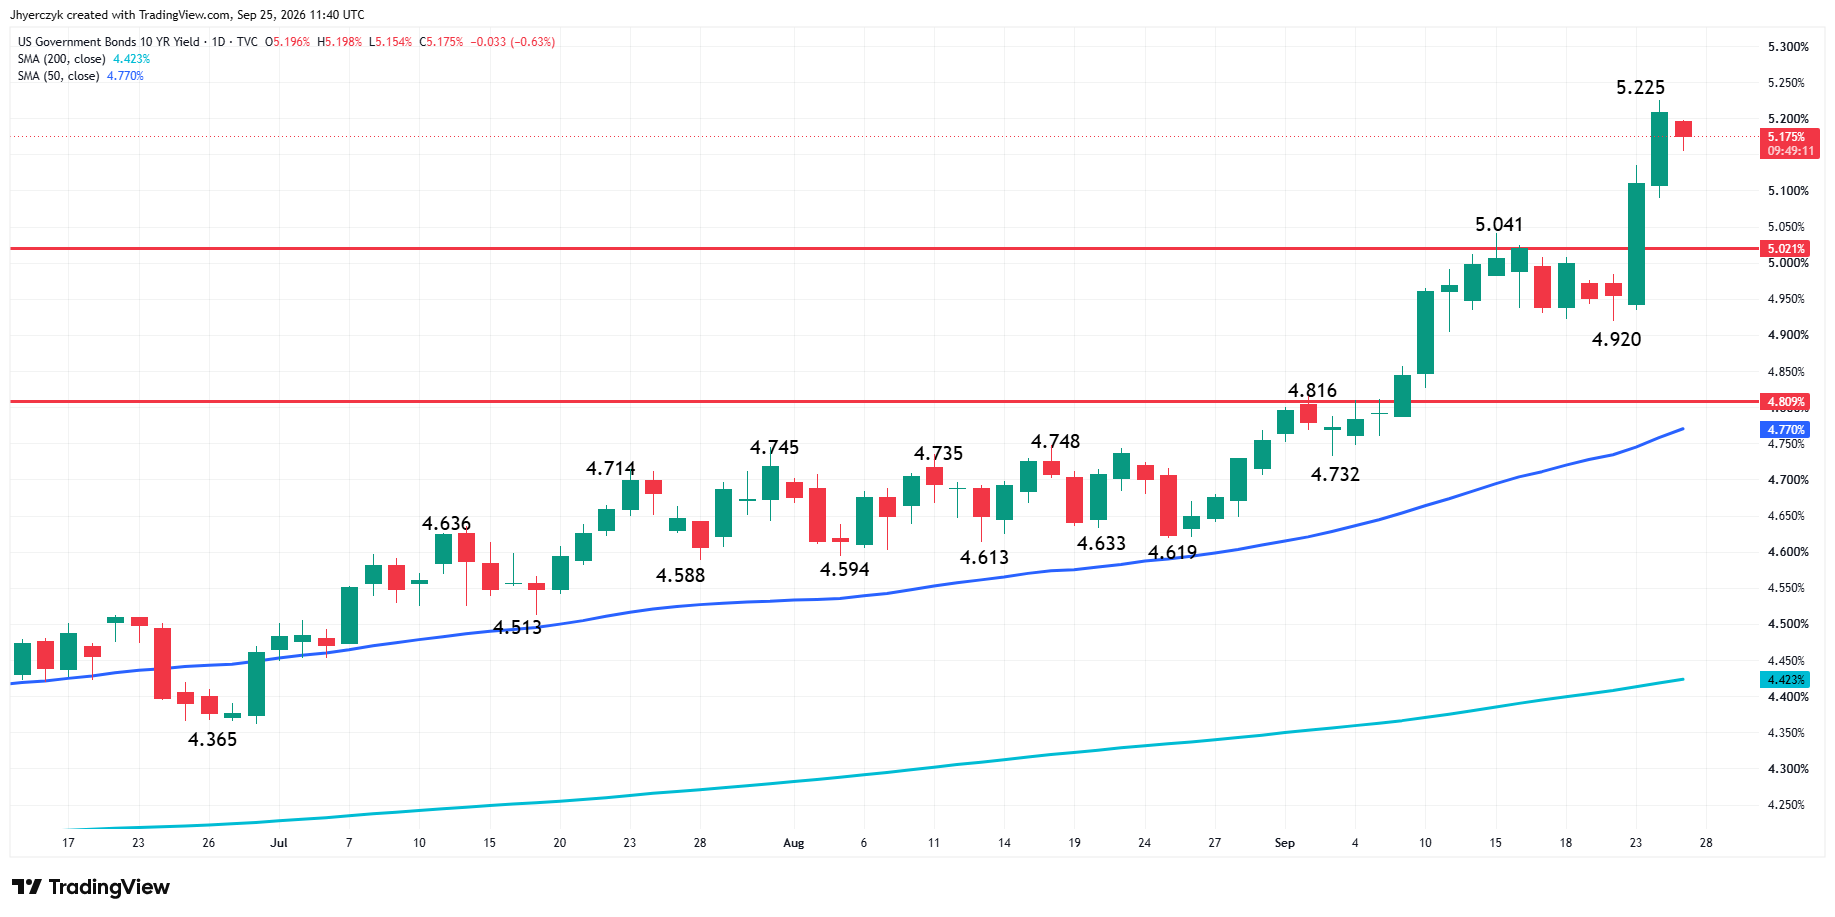
The 10-year Treasury yield is near 5.18% after reaching its highest since 2007 Thursday. The 30-year is near 5.48%, close to its highest since 2004. Fed funds futures are carrying about a 66% probability of another rate hike in October.
Durable-goods orders were flat in August, better than the expected 0.3% decline. Excluding transportation, orders rose 0.3%. That is not the kind of weak number that takes rate-hike odds out of the market.
Mortgage rates climbed to 7.45%. Regional banks, utilities, and homebuilders are already showing the pressure from the speed of the yield move this week. The indices are higher Friday. The rate trade underneath them has not reversed.
What to Watch
Friday’s trade is a rotation out of energy and into AI infrastructure. The move works as long as crude stays lower and buyers keep taking offers in the chip, server, and software names. The Hormuz headline has not fixed the Strait. Nine transits with Houthi strikes on Saudi targets Friday is not a normalized shipping lane.
The 10-year at 5.18% and October hike odds at 66% are still sitting over the tape. Durable goods came in flat, not weak enough to change the rate story. The Nasdaq Composite Index has 27,066.22 directly above. The S&P 500 Index stopped inside the 7,722.38 to 7,736.50 zone and backed off. The indices are higher. The bond market and the Strait are both unresolved. The AI names are carrying Friday’s session. The rest of the market is watching.
More Information in our Economic Calendar.