Current Movement: Futures Pull Back Ahead of Key Inflation Data
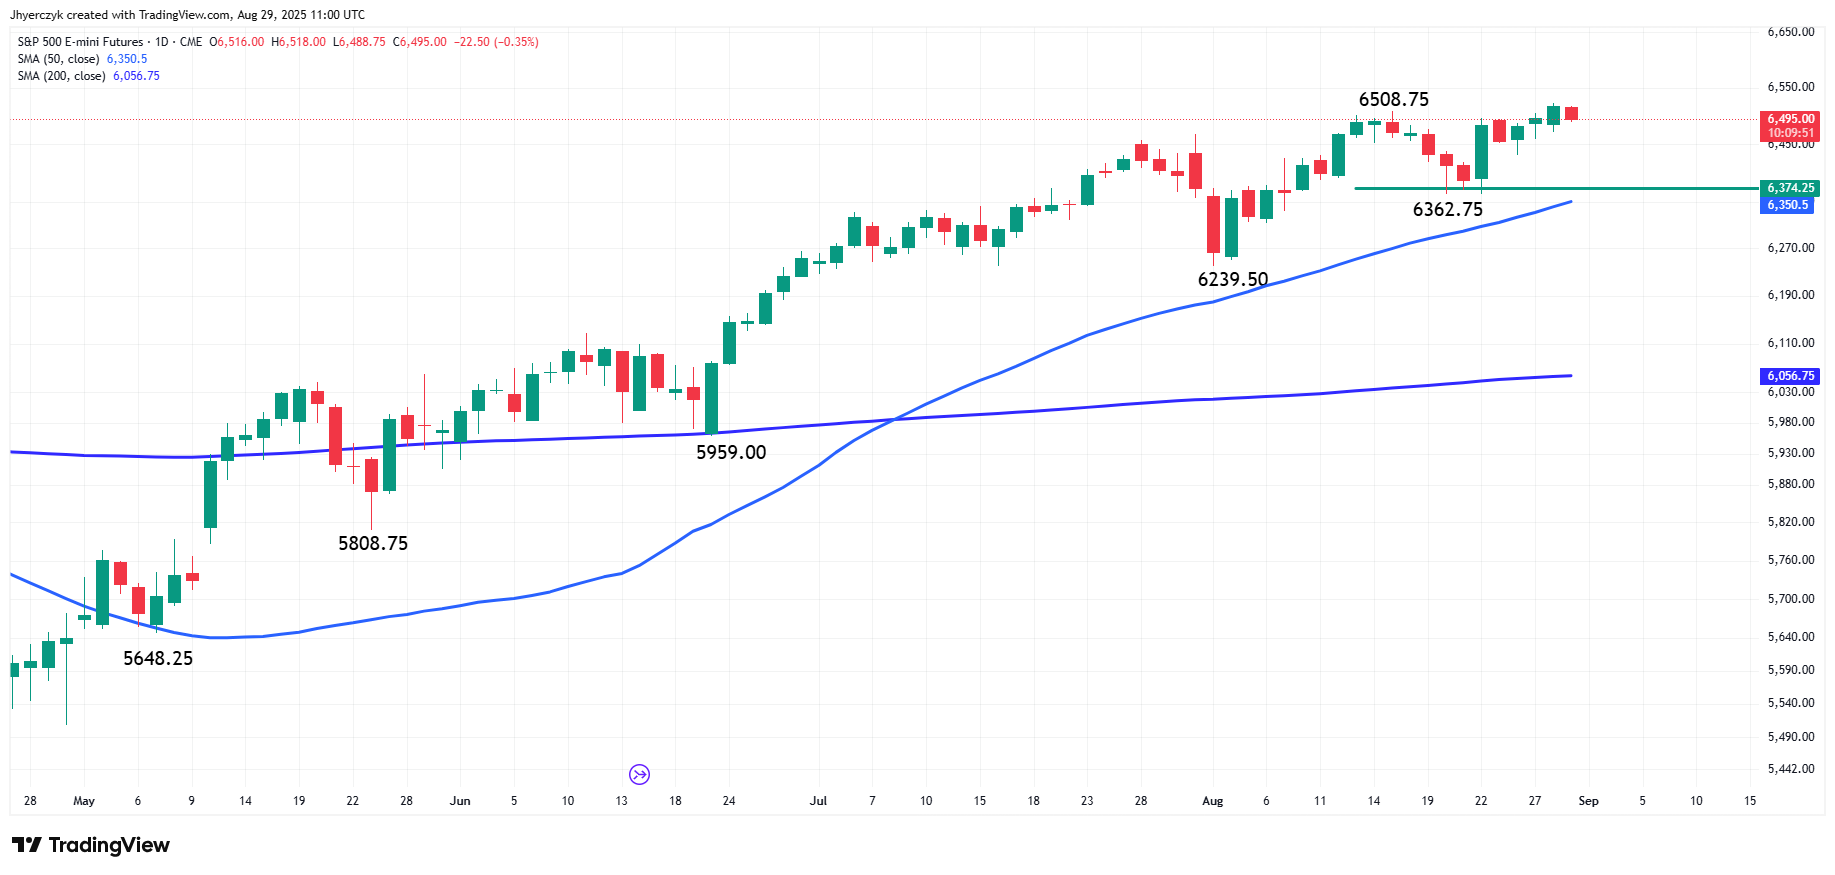
Heading into Friday’s session, equity futures are under pressure following Thursday’s record close for the S&P 500. Dow futures are down 154 points (-0.3%), with S&P 500 and Nasdaq 100 futures off 0.3% and 0.5%, respectively.
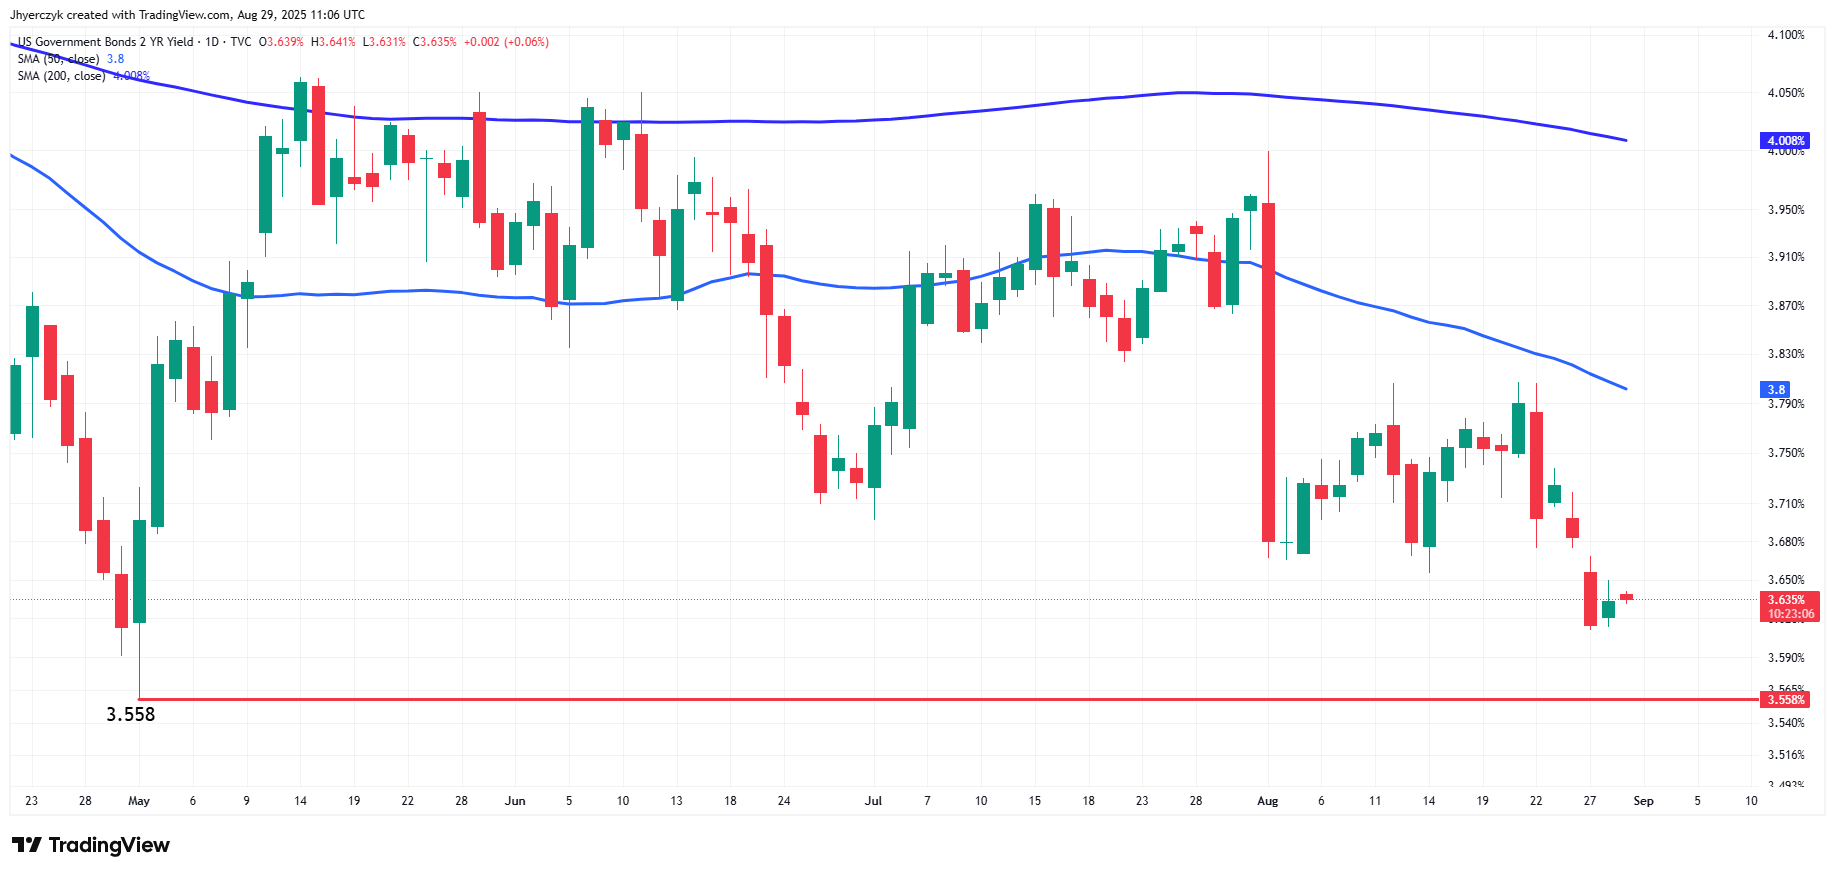
Yields are treading water—the 10-year holding around 4.22%, and the 2-year stuck near 3.635%. Traders are waiting on July’s PCE inflation, personal income, and spending numbers. This is the last inflation read before the September 16–17 FOMC, so it carries weight—but markets are playing it cautious for now.
Broader Context: Inflation Sticky, But Jobs Now the Focus
Economists are looking for a 0.2% rise in headline PCE and 0.3% in core, which would lift the year-on-year core rate to 2.9%—the hottest since February and a third straight monthly increase. Tariffs are still pushing prices higher, and some economists flag that core services—excluding energy and housing—are also running warm, which means this isn’t just about imports anymore.
But the Fed has a real dilemma. Inflation is firm, yes—but job growth has clearly slowed, and Powell said last week in Jackson Hole that the Fed is “less concerned about inflation right now” and more focused on employment softness. He already had a decent idea of this PCE report when he spoke, since it’s built on earlier CPI and PPI data.
Market Behavior: Fed Leaning Dovish, But Cuts Could Be Capped
Markets are still pricing in a cut for September, but expectations have pulled back a bit on how far the Fed can go. If today’s core PCE hits 2.9% or worse, that probably won’t block a cut—but it could limit how many bullets Powell’s team is willing to fire this year.
Fed minutes from July showed a “majority” of officials saw inflation risks as more pressing than jobs, though only “several” saw balanced risks, and just “a few” were really alarmed by inflation. That was before the soft labor data hit two days later. Since then, derivative markets have sharply increased odds of a rate cut.
S&P 500 Price Forecast
Every new S&P 500 analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all S&P 500 forecastsEconomists are hedging their bets. CIBC’s Avery Shenfeld says if it weren’t for all the political noise, the Fed probably wouldn’t be considering a cut here. Others, like Comerica’s Bill Adams, are watching core services inflation closely as a possible canary for 2025’s inflation trend.
Forward Outlook: PCE at 2.9% Keeps Cut Alive, But Slams the Door on More
So here’s the trade: a 2.9% core print likely doesn’t stop a September cut—but it makes back-to-back cuts less likely. If we get a 3% surprise, that could test nerves in the bond market and spark sellers at the long end.
On the flip side, if core holds steady or even dips? You could see buying in Treasuries, a pop in risk assets, and growing conviction that the Fed can ease again before year-end.
More likely than not, Powell sticks to one-and-done in September—unless August inflation or jobs completely roll over. Time will tell. For now, traders are buying dips, but nobody wants to be leaning too hard in either direction before the number hits.
More Information in our Economic Calendar.