Market Overview
U.S. equities finished last week higher as investors balanced a steady Federal Reserve policy decision against another strong round of corporate earnings. The Dow Jones Industrial Average closed at 52,485.03, up 1.04% for the week. The Nasdaq Composite finished at 25,373.85, up 1.59%, while the S&P 500 ended at 7,489.72, up 1.05%.
The Federal Reserve remained the primary market focus after leaving the federal funds target range unchanged at 3.50%–3.75% for a fifth consecutive meeting. Although the decision was widely expected, three policymakers dissented in favor of a quarter-point rate increase, reflecting continued concern that inflation remains above the Fed’s 2% target. Treasury yields moved higher following the meeting, particularly at the long end of the curve.
Earnings season continued to support equities despite mixed reactions among the largest technology companies. Microsoft and Amazon benefited from stronger cloud-computing revenue, while Apple and Meta Platforms declined as investors focused on capital spending, margins, and guidance. More than 86% of reporting S&P 500 companies have exceeded analyst estimates, with second-quarter earnings growth expectations rising to 37%, supported by broad participation across most sectors.
Attention now turns to another busy week featuring labor market data, manufacturing and services activity, and another round of high-profile earnings. Friday’s July employment report headlines the economic calendar, while earnings from Palantir, Caterpillar, AMD, SpaceX, Eli Lilly, Shopify and several other large-cap companies are expected to drive trading.
Key Economic Releases & Notable Earnings
Monday, Aug. 3
Before the Open
- Marriott International (MAR), est. $3.08
- Tyson Foods (TSN), est. $0.98
Economic Releases
- 13:45 GMT, Final Manufacturing PMI
- 14:00 GMT, ISM Manufacturing PMI
- 14:00 GMT, ISM Manufacturing Prices
- 14:00 GMT, Construction Spending m/m
- All Day, Omdia Total Vehicle Sales
- Tentative, Loan Officer Survey
After the Close
- Palantir Technologies (PLTR), est. $0.34. Investors will focus on AI software demand, commercial growth and continued momentum in government contracts.
- Vertex Pharmaceuticals (VRTX), est. $4.74
- Whirlpool (WHR), est. -$0.06
Tuesday, Aug. 4
Before the Open
- Caterpillar (CAT), est. $6.20. Investors will watch whether demand from AI-related data center construction continues to support growth following recent concerns over regulatory scrutiny.
- McDonald’s (MCD), est. $3.32
- Pfizer (PFE), est. $0.68
- Shopify (SHOP), est. $0.40
Economic Releases
- 12:30 GMT, Trade Balance
- 14:00 GMT, JOLTS Job Openings
- 14:00 GMT, Factory Orders m/m
- Tentative, RCM/TIPP Economic Optimism
- 20:30 GMT, API Weekly Statistical Bulletin
After the Close
- Advanced Micro Devices (AMD), est. $1.61. Analysts expect revenue of $11.3 billion, with attention focused on MI350 GPUs, EPYC processors, data center demand and AI guidance.
- SpaceX (SPCX), est. -$0.29. Revenue is expected to reach $6.8 billion in the company’s first earnings report as a public company. Investors will watch Starlink subscriber growth, AI pricing, the Cursor acquisition, Grok updates and broadband adoption.
- Arista Networks (ANET), est. $0.89
- Amgen (AMGN), est. $5.62
- Booking Holdings (BKNG), est. $2.43
- Pinterest (PINS), est. $0.36
Wednesday, Aug. 5
Before the Open
- CVS Health (CVS), est. $1.85
- Eli Lilly (LLY), est. $6.01
Economic Releases
- 12:15 GMT, ADP Non-Farm Employment Change
- 13:45 GMT, Final Services PMI
- 14:00 GMT, ISM Services PMI
- 14:30 GMT, Crude Oil Inventories
After the Close
- No reports scheduled
Thursday, Aug. 6
Before the Open
- No reports scheduled
Economic Releases
- 09:30 GMT, Challenger Job Cuts y/y
- 12:30 GMT, Initial Jobless Claims
- 12:30 GMT, Preliminary Nonfarm Productivity q/q
- 12:30 GMT, Preliminary Unit Labor Costs q/q
- 14:00 GMT, Final Wholesale Inventories m/m
- 14:30 GMT, Natural Gas Storage
After the Close
- No reports scheduled
Friday, Aug. 7
Before the Open
- No reports scheduled
Economic Releases
- 12:30 GMT, Average Hourly Earnings m/m
- 12:30 GMT, Non-Farm Employment Change
- 12:30 GMT, Unemployment Rate
- 15:00 GMT, Consumer Credit m/m
After the Close
- No reports scheduled
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecastsCentral Bank Activity
Wednesday, Aug. 5
- Lisa Cook (Federal Reserve Governor), 20:05 GMT
Thursday, Aug. 6
- Alberto Musalem (President, Federal Reserve Bank of St. Louis), 21:30 GMT
Friday, Aug. 7
- Thomas Barkin (President, Federal Reserve Bank of Richmond), 14:00 GMT
Markets will monitor comments from Federal Reserve officials for additional insight into the policy outlook following last week’s decision to leave interest rates unchanged while maintaining a strong focus on inflation.
Technical Outlook
Weekly Dow Jones Industrial Average Index
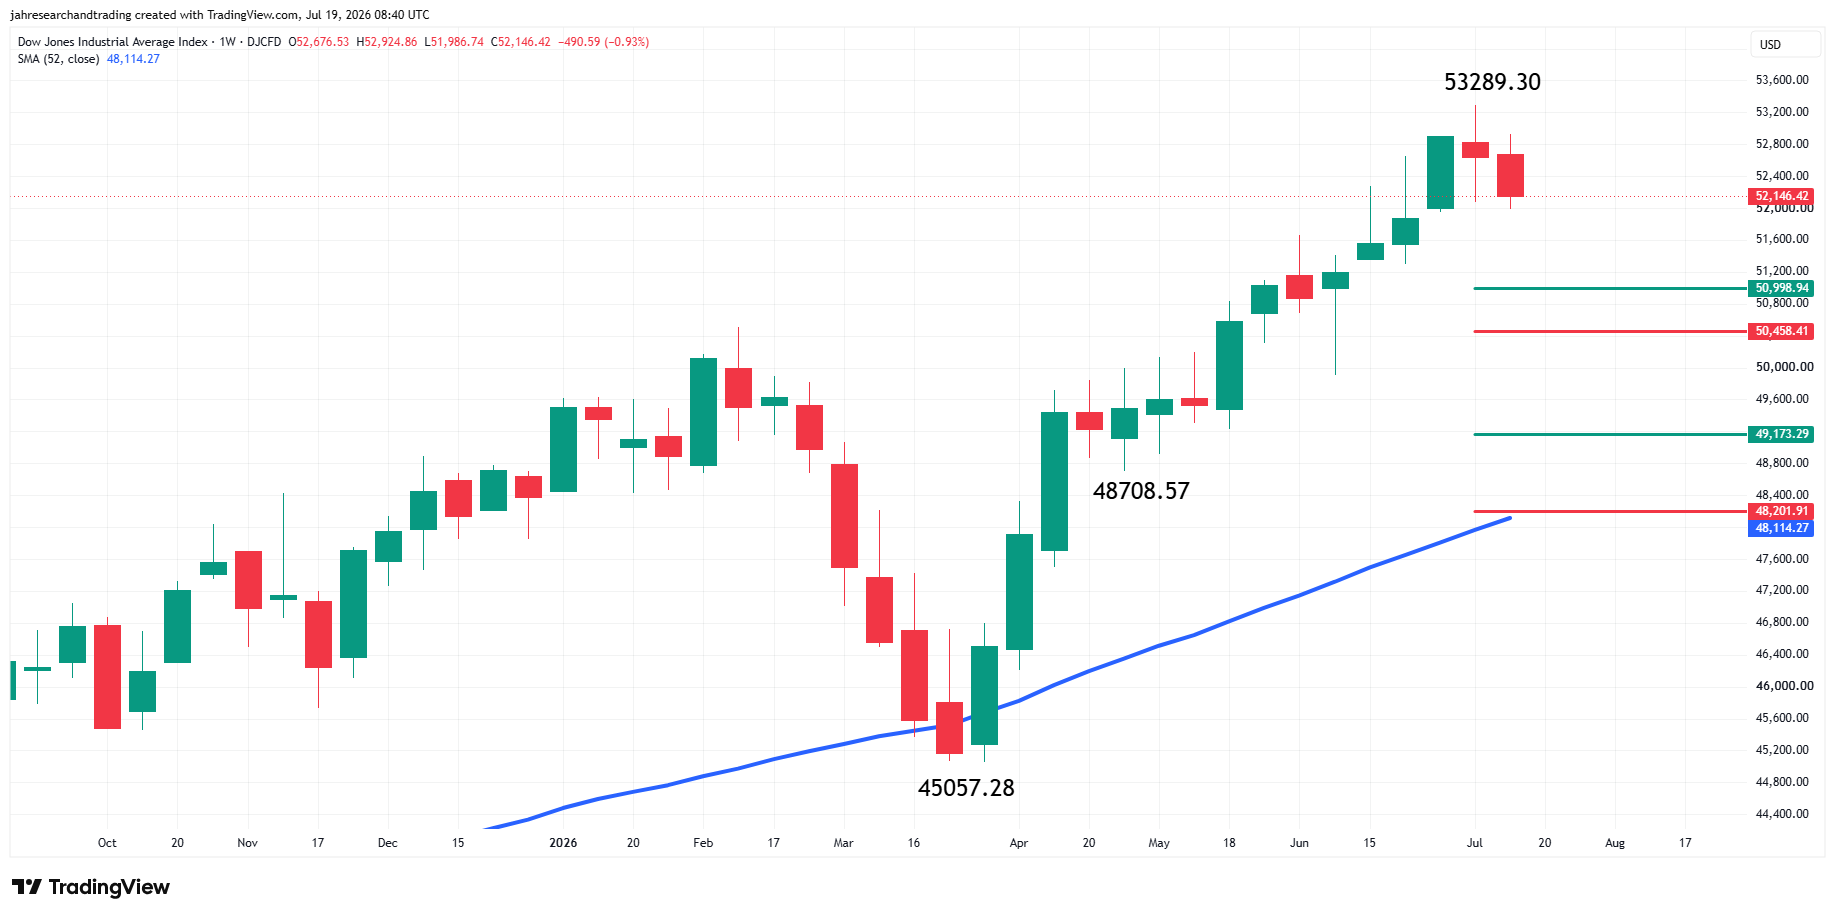
Dow Jones: 52,485.03 (+1.04%), support at 50,998.94, 50,458.41, 49,173.29, the 52-week SMA at 48,420.84, 48,201.91, 45,057.28 resistance at 53,289.30.
Weekly Nasdaq Composite Index
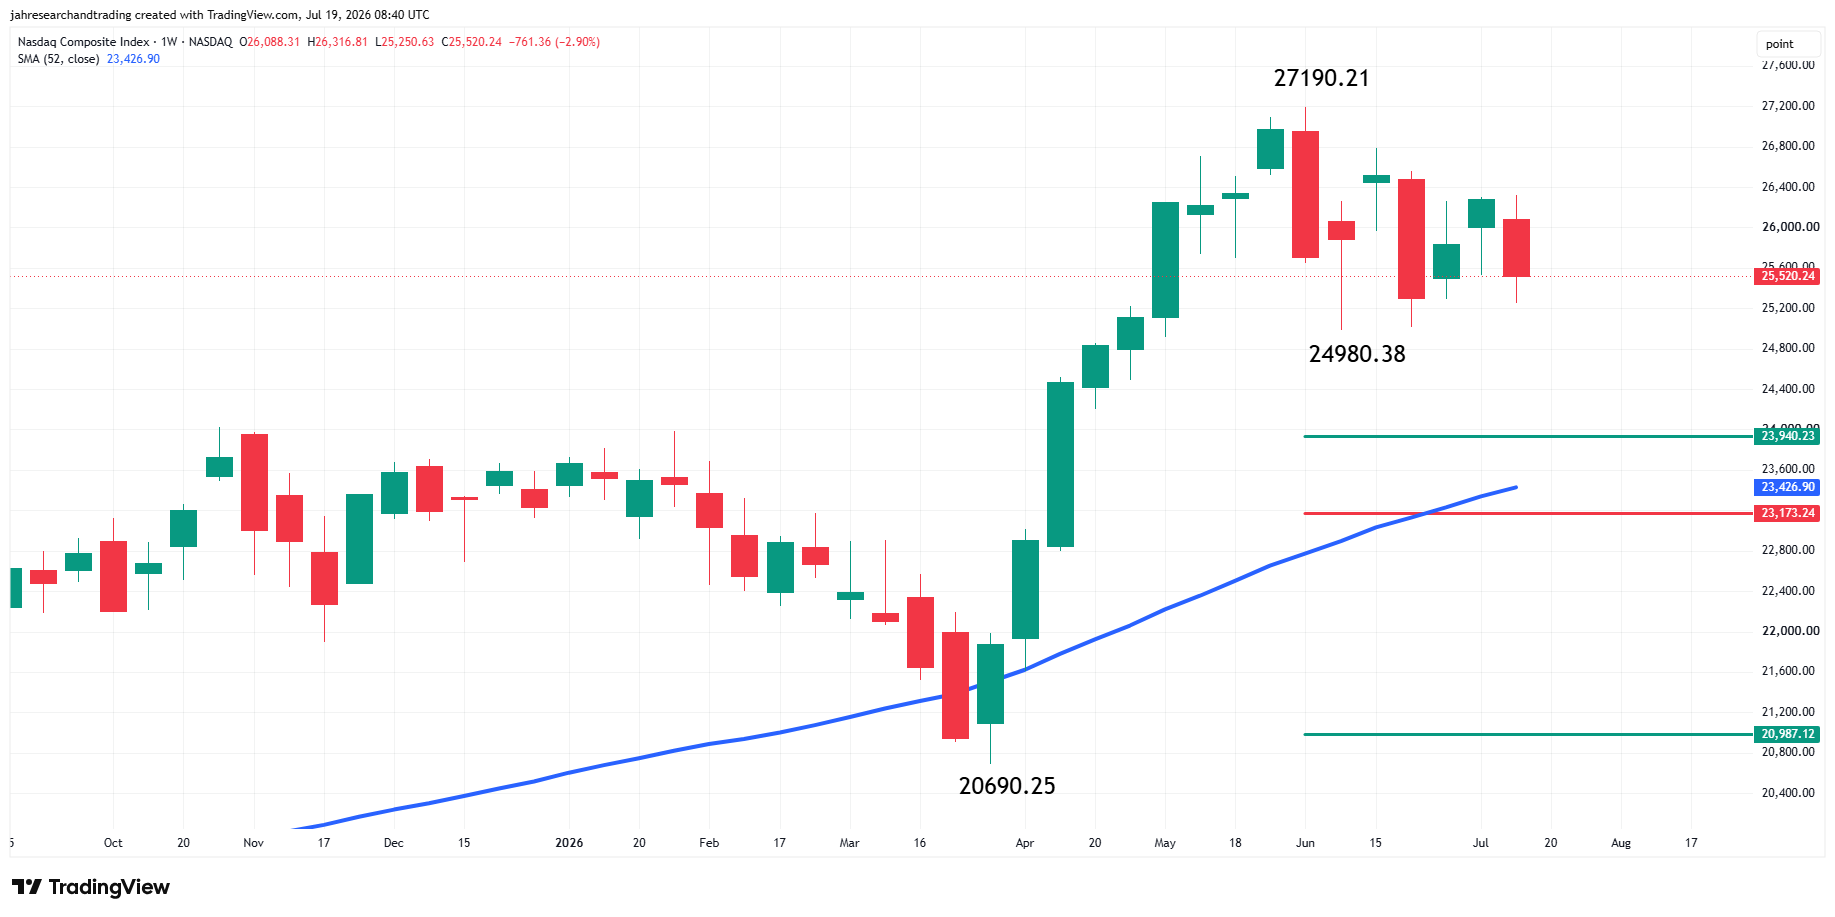
Nasdaq: 25,373.85 (+1.59%), support at 23,940.23, the 52-week SMA at 23,592.11, 23,173.24, 20,987.12, 20,690.25, 19,523.19, resistance at 27,190.21.
Weekly S&P 500 Index
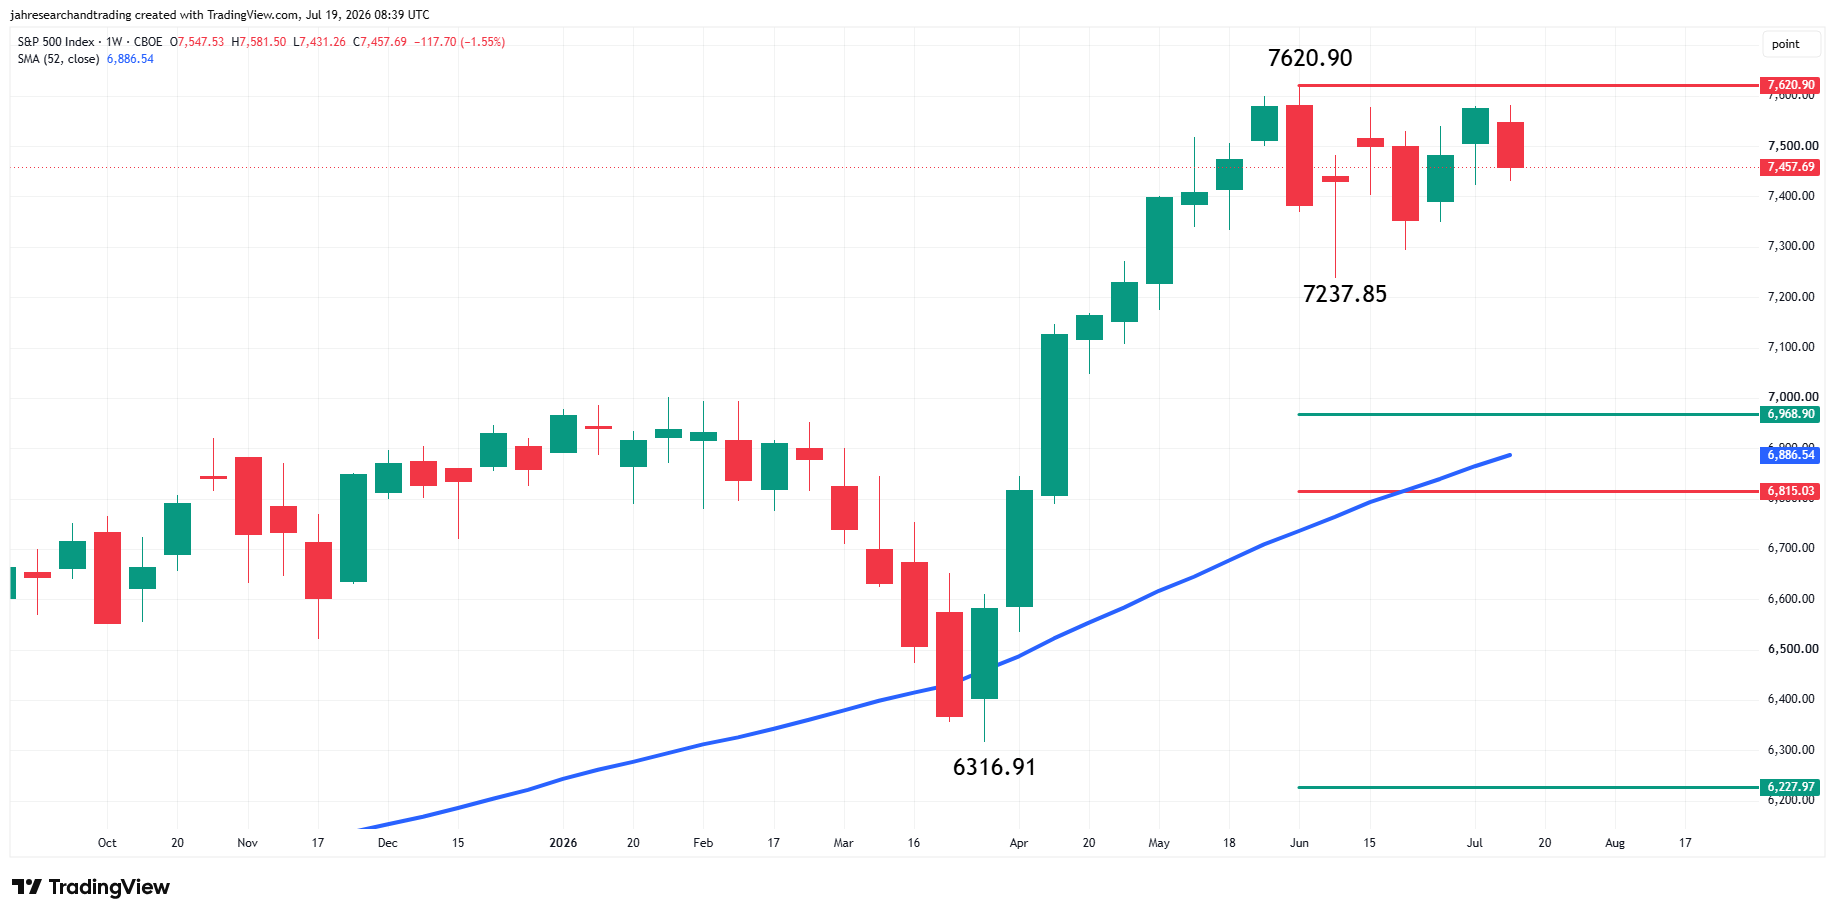
S&P 500: 7,489.72 (+1.05%), support at 7,429.38, 7237.85, 6,968.90, the 52-week SMA at 6,930.29, 6,815.03, 6,316.91, 6227.97, 5,899.24, resistance at 7,620.90.
All major indices remain above rising 52-week SMAs, confirming an intact long-term uptrend.
Outlook
The week’s primary catalysts are Friday’s employment report, manufacturing and services activity, JOLTS job openings, ADP employment, weekly jobless claims, and Federal Reserve commentary. Earnings from Palantir, Caterpillar, AMD, SpaceX, Eli Lilly, Shopify and other large-cap companies will also provide important insight into AI investment, enterprise demand, industrial activity and consumer spending.
The market enters the week with the longer-term technical trend remaining constructive as all three major indices continue to trade above their rising 52-week moving averages. Trading is likely to be driven by incoming economic data, Federal Reserve commentary and corporate earnings, with particular attention on whether labor market data and company guidance reinforce the current market trend or prompt a test of the support levels outlined above.